

Quick Answer: The IRS just lost $1.1 billion in base funding and 27% of its workforce — and if you owe back taxes, that makes your problem harder to solve, not easier. Automated collection systems that garnish wages and levy bank accounts run without human approval. The humans you need — the ones who negotiate payment plans, process Offers in Compromise, and answer phones — are the ones being cut. Your window to resolve IRS debt with a human being is shrinking right now.
If you’ve actually received a notice and you’re not sure what to do next, start here: The IRS Says I Owe Back Taxes. Here’s What to Do Right Now. — it walks you through your deadlines, your payment-plan options, and the one bankruptcy rule most tax-relief ads never mention.
For the full picture of how IRS collection works and every option you have — payment plans, the 10-year clock, settling for less, and when bankruptcy can erase tax debt — see our complete guide to IRS back taxes.
Expert Context: I’ve helped people navigate IRS debt for 30 years, and the hardest cases are always during periods of IRS understaffing — not because the IRS gets more aggressive, but because you literally cannot reach anyone to negotiate with. I watched this pattern during the 2013 sequester cuts and the 2018-2019 shutdown. What’s happening now is worse.
The IRS is being cut to the bone right now, and almost everyone is reading this story wrong. The assumption is that a weaker IRS means less enforcement — that if you owe money, the heat is off. After three decades of helping people with tax debt, I can tell you: the opposite is true.
What You Need to Know
Here’s what happened: The FY2026 spending deal cut the IRS budget to $11.2 billion — a 9% cut from last year. That includes a $439 million enforcement cut and a $941 million technology cut. On top of that, Congress clawed back $11.7 billion in Inflation Reduction Act funding that was supposed to modernize the agency through 2031.
Meanwhile, ABC News reported this week that President Trump is expected to drop a $10 billion IRS lawsuit in exchange for creating a $1.7 billion fund for people who claim they were victims of government “weaponization.”
The result: the IRS workforce has dropped from about 103,000 employees to 74,299 — a 29% reduction in a single year. Nearly two-thirds of senior leadership positions are vacant or filled with acting managers. The Taxpayer Advocate Service — the office that exists specifically to help people who can’t resolve their tax problems — lost 25% of its staff. (This mirrors what’s happening at the CFPB, which is being gutted at the same time.) The Appeals division lost 28%.
Why You Need to Know It
Everyone hears “IRS cuts” and thinks: good, maybe they’ll leave me alone. That’s not how the IRS works.
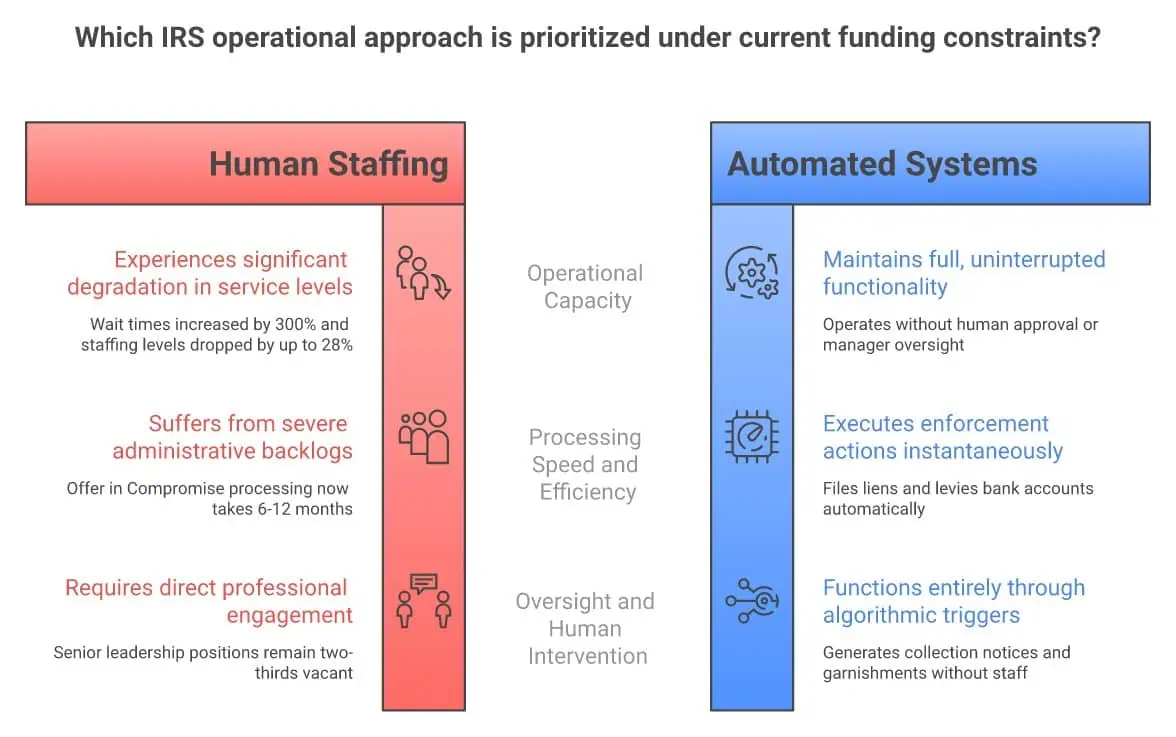
The IRS has two sides. One side is people — customer service reps who answer phones, revenue officers who negotiate payment plans, examiners who review Offers in Compromise. That side is being gutted.
The other side is computers. The Automated Collection System (ACS) sends notices, files tax liens, levies bank accounts, and garnishes wages. It doesn’t need a manager’s approval. It doesn’t need a full staff. It runs on autopilot.
The Claim: “IRS funding cuts mean less enforcement — if you owe taxes, the pressure is off.”
The Reality: Automated collection keeps running regardless of staffing. What gets cut is the human side — the people who answer phones, process payment plans, and negotiate settlements. You get the worst of both worlds: a machine that keeps garnishing and nobody available to help you stop it.
Here’s the math that should concern you. ACS phone wait times have increased over 300% — from about 5 minutes to 18 minutes. The main IRS phone line wait times jumped 70% year over year. The IRS lowered its own phone service target from 85% to 70%. Without investment, they warned it could drop to 11%.
Offer in Compromise submissions increased 15% from 2024 to 2025, while acceptance rates dropped by more than 25%. Processing already takes 6 to 12 months for straightforward cases. With fewer examiners, expect that to get worse.
The Squeeze: More people need IRS help (OIC submissions up 15%), fewer people are available to give it (staff down 27%), and the automated systems that garnish your wages keep running without interruption. If you wait, you may not be able to reach anyone at all.
Things to Consider
If you owe back taxes, the instinct is to wait — to assume that a weakened IRS means less risk. In my experience, that instinct is exactly backward.
During every previous period of IRS understaffing I’ve seen, the people who acted early got through. They reached a human, negotiated a payment plan, or settled their debt for less than they owed. The people who waited found longer hold times, slower processing, and automated levies they couldn’t get reversed because nobody was available to review the case.
What I’ve Seen Firsthand: The IRS doesn’t stop collecting when it’s understaffed. It stops negotiating. The automated system that garnishes your paycheck runs whether there are 103,000 employees or 74,000. The difference is whether there’s someone on the other end of the phone who can stop it.
There’s also a time-sensitive opportunity most people don’t know about. A court ruling in Kwong v. United States found that the IRS shouldn’t have assessed certain penalties and interest during the COVID disaster period (January 2020 through July 2023). The National Taxpayer Advocate says tens of millions of taxpayers may be eligible for refunds of improperly charged late-filing penalties, late-payment penalties, and interest.
The deadline to file a claim is July 10, 2026 — less than two months away.
What to Think About Doing
Here’s what I’d tell my own family right now:
- Check for COVID-era refunds immediately. If you filed late, paid penalties, or were charged interest on taxes due between January 2020 and July 2023, you may be owed money. File Form 843 (Claim for Refund) by July 10, 2026. Write “Protective Refund Claim Pursuant to Kwong Case” across the top. Send it by certified mail — you need proof it was mailed before the deadline.
- If you owe back taxes, start the Offer in Compromise process NOW. Processing already takes 6-12 months. With staff down 27%, that timeline is going to stretch. Every month you delay is a month further back in line. Go to IRS.gov/payments/offer-in-compromise to check if you qualify.
- If you’re getting automated collection notices, respond in writing immediately. Written responses preserve your appeal rights. Phone calls don’t create a paper trail. If ACS has issued a levy, you have 30 days to request a Collection Due Process hearing — miss that window and your options narrow dramatically.
- Call the IRS sooner rather than later — and budget your time. Expect 20-30 minute hold times minimum. Call early in the morning (7 AM local time) or late afternoon for shorter waits. If you can’t get through, the Taxpayer Advocate Service may be able to help — though they’re understaffed too.
- Consider hiring an Enrolled Agent — not a “tax resolution” company from a TV ad. Enrolled Agents are federally licensed tax practitioners who can represent you before the IRS. The tax resolution firms that advertise on TV charge $3,000-$10,000 upfront and often do less than you could do yourself. An Enrolled Agent at a local firm typically charges a fraction of that. Find one through the IRS directory or the National Association of Enrolled Agents.
Not sure where you stand? If tax debt is part of a larger debt problem — especially if you’re also carrying credit card or other consumer debt alongside IRS debt, take the free Find Your Path quiz to see how all your options compare — including some the IRS won’t tell you about.
Key Takeaways
- IRS funding was cut $1.1 billion (9%) for FY2026 and workforce dropped 27% — the largest cuts in modern history
- Automated collection (wage garnishment, bank levies) runs without human approval and continues regardless of staffing
- Phone wait times up 300% on collection lines; Offer in Compromise processing will slow further with fewer examiners
- COVID-era penalty refunds may be available — but the deadline is July 10, 2026 (file Form 843 by certified mail)
- Act now: the window to negotiate with a human at the IRS is closing, not opening
The Bottom Line
If you owe the IRS money and you’ve been putting off dealing with it, I understand the instinct. Tax debt feels like the scariest kind — the government has powers no credit card company can dream of. But here’s what 30 years have taught me: the worst time to deal with IRS debt is when you can’t reach anyone to negotiate with, and that’s exactly where we’re headed. The automated systems don’t care about your circumstances. The humans who could help are disappearing. This isn’t the moment to wait and hope — it’s the moment to pick up the phone, file the paperwork, and get in line while there’s still someone on the other end. You have options. Use them while the window is open.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Frequently Asked Questions
Will IRS budget cuts stop them from collecting my tax debt?
No. The IRS Automated Collection System (ACS) files liens, levies bank accounts, and garnishes wages without human involvement. What gets cut is the staff who answer phones, negotiate payment plans, and process settlements. Automated enforcement continues regardless of staffing levels.
What is the Kwong v. United States ruling and does it affect me?
The court ruled that IRS deadlines were automatically postponed during the COVID disaster period (January 2020 through July 2023). If you were charged late-filing penalties, late-payment penalties, or interest on taxes due during that period, you may be owed a refund. File Form 843 by July 10, 2026 to preserve your claim.
How long does an IRS Offer in Compromise take to process?
Currently 6 to 12 months for straightforward cases, longer for complex situations involving multiple tax years or business debts. With IRS staffing down 27% and OIC submissions up 15%, processing times are expected to increase further in 2026.
Should I hire a tax resolution company I saw on TV?
I’d avoid them. Those firms typically charge $3,000 to $10,000 upfront and often do less than you could do yourself. Instead, hire an Enrolled Agent — a federally licensed tax practitioner who can represent you before the IRS at a fraction of the cost. Find one through the IRS directory or the National Association of Enrolled Agents.
What should I do right now if I owe back taxes?
Three things, in order: (1) Check if you’re eligible for a COVID-era penalty refund and file Form 843 by July 10, 2026 if so. (2) Start the Offer in Compromise or installment agreement process immediately — every month you wait is a month further back in a growing line. (3) If you’re receiving automated collection notices, respond in writing to preserve your appeal rights.
This is what I’m seeing from 30 years of watching IRS cycles. I’d tell my own brother the same thing — act now, not because the sky is falling, but because the people who can help are leaving and the machines that collect don’t care about your story. Take this as one informed voice. You know your situation better than I do, and only you get to decide what’s right for your family.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



