

Quick Answer: The LIRR strike is stranding 300,000 daily commuters and threatening paychecks across Long Island and New York City. If you depend on the LIRR to get to work, call every creditor today — before you miss a payment, not after. Most credit card companies, mortgage servicers, and auto lenders have hardship programs that can defer payments and waive late fees, but they almost never advertise them. The difference between a temporary disruption and a debt spiral is almost always timing.
Expert Context: I’ve been helping people with debt since 1994 — and I ran a credit counseling organization where I watched, over and over, how the same financial disruption destroyed one family and barely dented another. The difference was never income. It was always timing — who called their creditors before the first missed payment, and who waited until collections started.
The Long Island Rail Road shut down at 12:01 a.m. Saturday — the first strike in more than 30 years — and if you’re one of the 300,000 daily riders staring at Monday’s commute, the biggest financial danger isn’t the strike itself (I covered the full playbook for work stoppages and financial crises earlier this year). It’s what you do in the next 48 hours.
What’s Actually Happening With the LIRR
Five unions representing roughly 3,500 LIRR workers — about half the workforce — walked off the job after contract negotiations with the MTA stalled over wages and healthcare premiums. The workers haven’t had a raise in years and are seeking roughly 5% to keep pace with inflation.
The MTA has suspended all LIRR service systemwide. Governor Hochul has activated limited shuttle buses during peak hours for essential workers, but she’s been blunt: “These alternatives are not business as usual.” Commute times that normally take 40 minutes could stretch to two and a half hours.
The National Mediation Board has stepped in, and MTA Chair Janno Lieber says he’s “cautiously optimistic” — but even if a deal is reached today, service wouldn’t resume until tomorrow at the earliest.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Financial Danger Nobody’s Talking About
Here’s what the news coverage is missing: the strike itself is temporary, but the financial damage it triggers can compound for months.
When you can’t get to work, you don’t just lose a day’s pay. You trigger a cascade:
- Missed shifts mean reduced income on your next paycheck
- A late credit card payment triggers a penalty APR — often jumping from 18% to 29.99%
- One missed mortgage payment starts a 30-day clock that hits your credit report
- Late fees on auto loans, student loans, and utilities stack up simultaneously
- If you use a payday loan or cash advance to bridge the gap, you’re converting a 3-day problem into a 3-month problem
I’ve counseled thousands of people who came to me after a temporary income disruption turned into unmanageable debt. Almost every single one said the same thing: “I thought the strike/layoff/shutdown would only last a few days, so I didn’t call anyone.”
Why You Need to Call Your Creditors Today — Not Tomorrow
Most major creditors have hardship programs. Credit card companies, mortgage servicers, and auto lenders all offer some version of temporary relief — reduced interest rates, waived late fees, deferred payments, or short-term payment suspensions.
But there’s a catch that nobody tells you about:
Critical Timing Rule: These programs are almost always easier to access BEFORE you miss a payment. Once a payment is 30 days late, your options narrow dramatically. Calling proactively — while your account is still current — gives you the most leverage and the best terms. This is the single most important financial move you can make during a transit disruption.
Here’s exactly what to say when you call: “I’m an LIRR commuter affected by the transit strike. I may experience a temporary income disruption. What hardship accommodations do you offer?”
Document the name of every person you speak with and any case or reference number. If they offer you something, get it in writing — even an email confirmation counts.
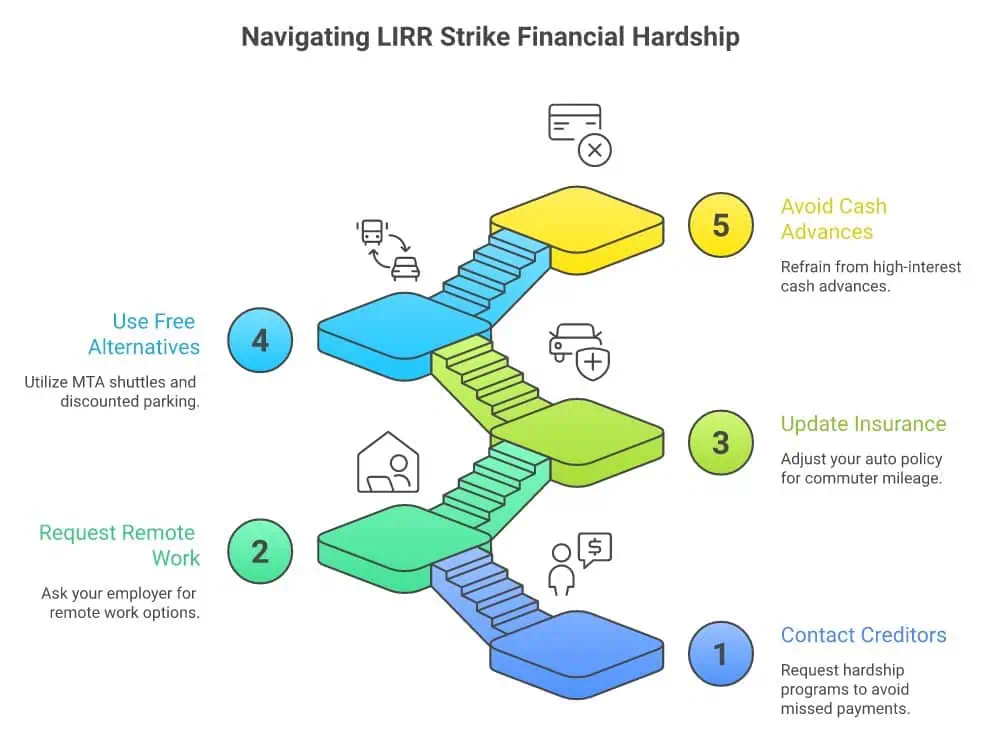
The 5-Step Hardship Playbook for LIRR Commuters
Do this today — not Monday, not “when the strike ends.” The window for proactive action is right now.
1. Call every creditor and request hardship accommodation
Start with the highest-stakes obligations: mortgage, auto loan, credit cards. Use the exact language above. Most major lenders have formal hardship programs with options including:
- Payment deferral (1-3 months, added to end of loan)
- Late fee waiver
- Temporary interest rate reduction
- Skip-a-payment programs
2. Talk to your employer before Monday morning
If your company has any remote work or schedule flexibility policy, request it in writing now. An email saying “Due to the LIRR strike, I’m requesting to work remotely on Monday” creates documentation that protects you later. If your employer refuses and you lose shifts, keep your pay stubs showing the reduction — you may need them for hardship applications.
3. Check your insurance — your coverage may need updating
If you normally commute by train but now need to drive, your auto insurance may not reflect the additional mileage. Contact your insurer and ask about commuter mileage adjustments. Your premium may change, but it’s better than discovering a coverage gap after an accident on the Long Island Expressway during strike-related traffic.
4. Know the alternative transportation options
The MTA’s contingency plan includes:
- Free shuttle buses from Bay Shore, Hicksville, Mineola, and Lakeview to Howard Beach-JFK Airport
- Shuttles from Ronkonkoma and Huntington to Jamaica-179th Street
- $6 parking at Citi Field connecting to the 7 train at Mets-Willets Point
- NICE bus routes with increased service
Plan for significantly longer commute times. The MTA estimates shuttle buses will carry about 13,000 riders each way — a fraction of normal capacity.
5. Do NOT use payday loans or credit card cash advances to bridge the gap
The Temptation: “I’ll just take a cash advance to cover this week and pay it back when the strike ends.”
The Math: Credit card cash advances typically charge 3-5% upfront fees PLUS a higher interest rate (often 25-29%) with no grace period — interest starts accruing immediately. A $500 cash advance to cover a week of expenses could cost you $75-100 in fees and interest. Payday loans are even worse. You’re converting a temporary 3-day disruption into expensive debt that follows you for months.
What If the Strike Drags On?
If this extends beyond a few days, the financial pressure escalates quickly. Here’s your escalation plan:
- Days 1-3: Call creditors, document everything, use alternatives, request remote work
- Days 4-7: If income loss is confirmed, contact your utility companies for payment arrangements. My 30-day recession checklist covers the full triage sequence. Call 211 (United Way helpline) for local emergency assistance programs
- Beyond one week: If you’re facing serious income loss (I wrote a similar hardship playbook for federal workers during the DHS shutdown — many of the same creditor strategies apply), talk to Damon Day for a free phone call about your full financial picture. He’ll walk through your options honestly — including ones most advisors won’t mention
The New York State Comptroller estimates the strike costs the regional economy more than $60 million per day. That’s not just an abstract number — it represents real paychecks, real missed shifts, and real bills coming due.
Your Employer Can’t Fire You for a Transit Strike
One fear I want to address directly: you won’t lose your job because the train stopped running. New York employment law protects workers from termination due to circumstances beyond their control. There’s even pending state legislation (S938) that would eliminate the presumption that an employee participated in a strike just because they were absent on a strike day.
That said, documentation matters. Email your supervisor explaining the situation, save any news articles about the strike, and keep records of your attempts to find alternative transportation.
The Bottom Line
The LIRR strike is temporary. (If your family faces a different kind of disruption — like the sudden loss of a breadwinner to detention or deportation — the same creditor-hardship playbook applies, but with even more urgency.) The financial damage from doing nothing about it doesn’t have to be. I’ve watched thousands of people turn a temporary income disruption into a permanent debt problem — and every single time, the turning point was the same: they waited too long to pick up the phone. Call your creditors today, while your accounts are current and your leverage is strongest. One 15-minute phone call now can prevent months of penalty rates, late fees, and collection calls later. The strike will end. What you do before it ends is what matters.
Frequently Asked Questions
Can I get a refund on my LIRR monthly pass during the strike?
Yes. The MTA has confirmed that monthly ticket holders will receive pro-rated refunds for May based on the number of strike days. Check the MTA’s strike information page for details on how refunds will be processed.
Will calling my creditor about a hardship program hurt my credit score?
No. Requesting information about hardship programs does not appear on your credit report. What does appear is a late payment — which is exactly what you’re trying to prevent by calling proactively. Some creditors will notate your account as “in hardship” which can actually protect you from negative reporting during the arrangement period.
What if my employer won’t let me work remotely during the strike?
Document the refusal in writing. If you lose wages as a result, keep your pay stubs showing reduced income — you’ll need this documentation for creditor hardship applications, and potentially for any future legal claims. If you’re an hourly worker who loses shifts, contact the New York Attorney General’s worker rights hotline for guidance specific to your situation.
Should I use my emergency savings to cover bills during the strike?
This is exactly what emergency savings is for — a temporary, unexpected income disruption. But call your creditors first. If they offer a payment deferral, you may not need to tap savings at all. Save your cash reserves for essential expenses like groceries and childcare, and let the hardship programs handle the creditor payments.
What if the strike ends quickly — should I still call creditors?
Yes. Even if service resumes tomorrow, your next paycheck may already reflect lost hours. And having a hardship accommodation on file gives you a safety net if the dispute resurfaces. It takes 15 minutes and costs nothing. There’s no downside to being prepared.
This is what I’m seeing after 30 years of helping people navigate financial disruptions. Take this as one experienced perspective — but only you know your full situation. Use these steps as a starting point, not a mandate. Nobody — including me — gets to tell you what to do with your money. You’re the only one who knows what’s at stake for your family this week.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



