

Quick Answer: If you need to talk to your spouse about bankruptcy but you’re dreading it, you’re not alone. This is one of the hardest conversations in any marriage — not because the math is complicated, but because it touches everything: shame, failure, fear, and the future you planned together. Here’s what I’ve learned after helping people with debt since 1994 and filing bankruptcy myself in 1990: your spouse’s reaction probably isn’t about the bankruptcy. It’s about grieving the plan that didn’t work. And there’s a way through that conversation that brings you closer instead of pulling you apart.
Expert Context: I filed bankruptcy in 1990. I remember the shame like it was yesterday. And I remember the conversation with the people who mattered to me — the moment where you have to say out loud, “the plan we had isn’t working.” That conversation is harder than the filing itself. But I’ve also watched thousands of couples come out the other side, and the ones who navigate this conversation well almost always end up stronger. Not because bankruptcy is fun, but because honesty under pressure is the foundation of everything that comes after.
Every week, people come to our site ready to explore bankruptcy as an option — but terrified of one thing that has nothing to do with the law or the math. They’re terrified of telling their spouse. Some have been carrying the weight of impossible debt alone, shielding their partner, hoping it will get better. It hasn’t. And now the conversation can’t wait any longer.
Why This Conversation Feels Impossible
Let me tell you what I hear from people every single week: “I brought up bankruptcy and my spouse cried.” “They said it feels like failing.” “They think it means we did something wrong.” “They said it makes them want to throw up.”
Here’s what I want you to understand: your spouse is not crying about the bankruptcy. They’re mourning the life they thought they had. The house, the stability, the plan — the story they told themselves about how things were supposed to go. When you say the word “bankruptcy,” you’re not just suggesting a legal filing. You’re saying the old story is over.
That’s grief. And grief is a normal, healthy response to loss — even the loss of a plan that wasn’t working anyway.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Your spouse isn’t crying about the bankruptcy. They’re mourning the life they thought they had. Once you understand that, you can stop defending the decision and start grieving together.
What Your Spouse Is Actually Afraid Of
In three decades of helping people, I’ve found that the fear almost always comes from one of these places:
Fear #1: “We’ll lose everything.”
Reality: Most people who file Chapter 7 keep their home, their car, their retirement accounts, and their personal belongings. Bankruptcy exemptions protect these assets. Your 401(k) and IRA are completely untouchable — federal law protects them no matter what. The “lose everything” image comes from movies, not courtrooms.
Fear #2: “Our credit will be destroyed forever.”
Reality: Your credit recovers faster after bankruptcy than it does after years of missed payments, collections, and charge-offs. Most people see their credit score start climbing within 12-18 months after a Chapter 7 discharge. The bankruptcy stays on your report for 7-10 years, but its impact fades quickly — especially compared to the damage that ongoing unmanageable debt does every single month you don’t file.
Fear #3: “Everyone will know.”
Reality: Bankruptcy filings are technically public record, but nobody casually browses bankruptcy court databases. Your employer won’t be notified. Your neighbors won’t find out. The only people who know are you, your spouse, your attorney, and the court. I filed in 1990 — the only people who found out were the ones I told.
Fear #4: “It means we failed.”
Reality: Debt is what’s left over when the math is broken. A medical emergency, a job loss, a divorce, a pandemic, a business that didn’t make it — these aren’t moral failures. They’re math problems. Bankruptcy is the legal tool designed to solve them. The same legal system that created bankruptcy created it because they knew life doesn’t go according to plan. Using it isn’t failure. It’s the system working as intended.
How to Actually Have the Conversation
Don’t ambush your spouse with “I think we should file bankruptcy” over dinner. That’s not a conversation — that’s a verdict. And it will feel like one.
Here’s a framework that actually works:
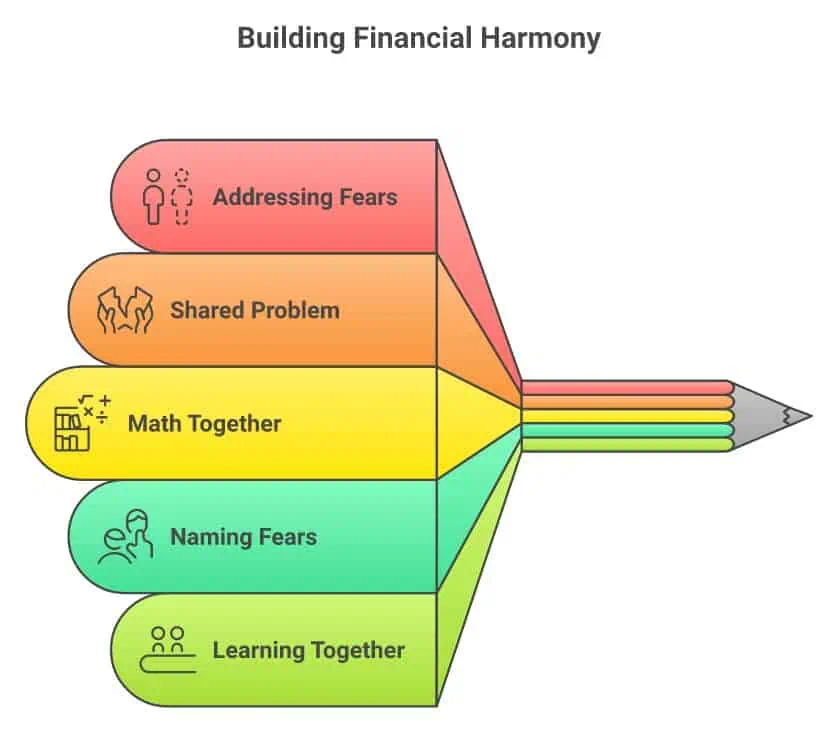
- Start with the shared problem, not the solution. “I need to talk to you about where we are financially. I’ve been carrying this, and I shouldn’t be doing it alone.” Don’t lead with bankruptcy — lead with honesty about the situation
- Show the math together. Lay out the numbers: what you owe, what you make, what the minimum payments are, and how long it would take to pay off at the current rate. Let the math speak. When your spouse sees that paying minimums for 15 years costs $400,000+ and eats their retirement, the conversation shifts from emotion to reality
- Name the fear before they do. “I know this sounds scary. I was scared too when I first looked at the numbers. Here’s what I learned that changed how I see it.” This shows you’ve done the work and aren’t being impulsive
- Give them time to process. This is probably the first time they’re hearing this. You’ve had weeks or months to sit with it. They need at least a few days. Don’t push for an answer in the same conversation
- Suggest learning together. “I’m not asking you to decide tonight. I’m asking you to look at this with me so we can make a decision together.” Offer to take the 2-minute bankruptcy quiz together, or to read through all the options side by side
What NOT to Say
- “We have no choice.” You always have choices. Framing it as inevitable makes your spouse feel powerless. Instead: “Here are the options I’ve found, and here’s why this one makes the most sense for us”
- “It’s not a big deal.” It IS a big deal — to them. Minimizing their feelings will make them feel unheard. Instead: “I know this is heavy. It’s heavy for me too”
- “I’ve already talked to a lawyer.” Even if you have, leading with this makes it feel decided. Instead: “I’ve been researching, and I’d like us to talk to someone together”
- “Dave Ramsey says…” or “My friend says…” — Your spouse needs to hear what’s right for YOUR family, not what worked for someone else’s. Different situations call for different approaches
When One Spouse Wants to File and the Other Doesn’t
This happens constantly. One partner has reached the breaking point. The other is still holding onto hope that something will change — a raise, an inheritance, a miracle. They’re not wrong to hope. But hope isn’t a financial strategy.
Here’s what I’d suggest: agree to a timeline together. “Let’s give it 90 days. If we can’t reduce the debt by $X or find a way to increase income by $Y, we revisit this conversation with all the options on the table.” This isn’t kicking the can — it’s giving the reluctant spouse ownership of the timeline while making sure the conversation doesn’t die.
And here’s something most people don’t know: one spouse can file bankruptcy without the other. If you have separate debts, it’s possible for one person to file individually while the other’s credit remains untouched. A bankruptcy attorney can explain whether this makes sense for your situation. If you need help finding one, NACBA (the National Association of Consumer Bankruptcy Attorneys) has a free attorney finder.
The Conversation Nobody Talks About: Retirement
Here’s the thing that keeps me up at night about couples who avoid this conversation: while they’re arguing about whether bankruptcy “feels right,” they’re bleeding retirement savings.
I see it every week — people pulling from their 401(k) to make credit card minimums. That’s a $400,000+ mistake when you factor in the taxes, penalties, and lost compound growth. Your retirement accounts are 100% protected in bankruptcy. Every dollar you withdraw to pay unsecured debt is a dollar you’ll never get back.
When you have the conversation with your spouse, this is the number that changes everything. It’s not about whether bankruptcy “looks bad.” It’s about whether you’ll be able to retire. Frame it that way and the conversation shifts from shame to survival.
If that conversation goes well, there is a second one worth having with your kids. The money conversation wealthy families pay advisors to run for them costs nothing to copy — and protecting the retirement account you did not cash out is the first line of it.
Stop-the-Bleeding Check: If either spouse is currently withdrawing from retirement accounts (401(k), IRA, pension) to pay credit cards, medical bills, or other unsecured debt — this is an emergency. That money is legally protected from creditors in bankruptcy. Every withdrawal is permanent. Talk to a bankruptcy attorney or call Damon Day for a free phone consultation before making another withdrawal.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
What Happens After You Both Agree
Once you’re on the same page — or at least willing to explore together — here’s the path forward:
- Take the Find Your Path quiz together — it takes 2 minutes and gives you a recommendation based on your actual numbers, not generic advice
- Review all your debt relief options side by side — bankruptcy, settlement, debt management plans, and doing nothing. Each has real trade-offs
- Talk to a bankruptcy attorney for a free consultation — most offer free initial consultations. NACBA has a directory by state. Or call Damon Day for a free phone call to help you understand all the options before you commit to any of them
- Make the decision together. Whether you file or find a different path, the decision should be joint. The couples who navigate this well are the ones who stop seeing debt as one person’s fault and start seeing it as one family’s math problem to solve
The Bottom Line
The hardest part of bankruptcy isn’t the filing, the paperwork, or the court appearance. It’s the conversation with your spouse. But here’s what I know after 30+ years: the couples who have this conversation — honestly, together, with all the facts — come out stronger. The ones who avoid it keep bleeding. If you’re dreading this talk, you’re normal. If your spouse cries, that’s normal too. It’s not about the bankruptcy. It’s about the life you’re building next. Have the conversation. Show them the math. Give them time. And know that millions of families have been exactly where you are and come out the other side. If someone you know is struggling with this, send them this — sometimes the hardest step is knowing it’s okay to take it.
I filed bankruptcy in 1990. I know what it feels like to say those words out loud for the first time. This is the conversation I wish someone had coached me through. Take it as one perspective from someone who’s been there — not as a prescription. Only you and your spouse know your full situation. But I’ll tell you what I tell everyone: the conversation you’re avoiding is almost always less painful than the silence.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



