
Written by Steve Rhode, consumer debt expert since 1994 • Last updated May 28, 2026
If it’s your own bank draining the account through overdraft and NSF fees rather than a creditor levy, that’s a different fix — here’s how to stop overdraft fees under Regulation E.
Quick Answer: A frozen bank account means a creditor with a court judgment — or a government agency like the IRS — sent a legal order to your bank directing them to hold your money. Federal law under 31 CFR Part 212 requires your bank to automatically protect two months of direct-deposited federal benefits (Social Security, SSI, VA). Beyond that, you typically have 10 to 21 days to file an exemption claim before the frozen funds are turned over to the creditor. Filing bankruptcy triggers the automatic stay under 11 U.S.C. § 362, which can force release of the frozen funds. Don’t move money to a new account — that can be reversed and makes things worse.
What Just Happened to Your Money
Your bank received a legal order — called a levy, garnishment order, or writ of execution depending on your state — directing them to freeze the funds in your account. Your bank has no choice. They must comply or face penalties.
There are two stages to this process, and the difference matters. First, the bank freezes your account — your money is still there, but you can’t access it. Then, after a waiting period (usually 10 to 21 days), the bank turns the frozen funds over to the creditor unless you take action. That waiting period is your window. Right now, your money is frozen but not gone.
In most cases, this happened because a creditor sued you, won a judgment, and then obtained a court order to levy your bank account. If you didn’t know about the lawsuit, a default judgment was likely entered against you — which happens in 70% to 90% of debt collection lawsuits where the debtor doesn’t respond. Sometimes, before or after freezing an account, the creditor also orders you into court to answer questions about your income and assets under oath — here’s what to do if you’re facing a debtor’s examination.
The Mistake You’re About to Make: Don’t open a new bank account and try to move your money or redirect your paycheck. Creditors can discover new accounts, and transferring assets after a judgment can be treated as a fraudulent transfer — making your legal situation significantly worse. Don’t withdraw cash from other accounts to hide it. And don’t ignore the notice — you have a deadline to claim exemptions, and that clock is already running.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
Your Options Right Now
What to Do in the Next 48 Hours
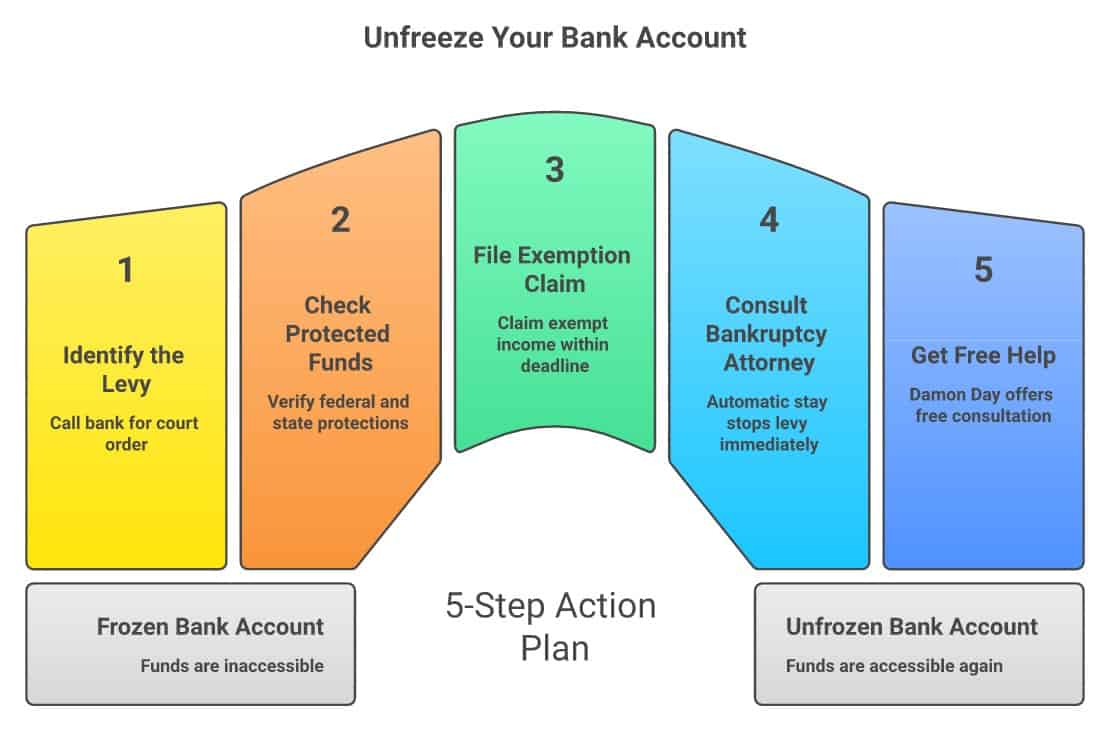
- Find out who froze your account and why. Call your bank immediately and ask for a copy of the levy or garnishment order. This tells you: which creditor, the judgment amount, which court issued the order, and your deadline to respond. Check whether this is a creditor levy (court judgment), IRS levy, child support order, or student loan offset — each has different rules and different deadlines. And if a merchant cash advance froze your account, the mechanism is usually a confession of judgment, which works differently from a normal creditor levy.
- Check if your funds are protected. If you receive Social Security, SSI, VA benefits, or other federal benefits by direct deposit, your bank must automatically protect two months of those deposits under 31 CFR Part 212. You should already have access to the protected amount — if your bank froze everything, call them and cite this federal regulation. Some states also protect a minimum balance automatically: New York protects $3,840 to $4,080, California protects $2,170, and Oregon protects $2,500. Use the free Judgment-Proof Checker to see what’s protected in your state.
- File an exemption claim immediately. Most states give you 10 to 21 days from the date of the levy to file a claim of exemption with the court. Protected income sources include Social Security, disability benefits, workers’ compensation, unemployment, veteran benefits, retirement distributions, and in many states, a percentage of wages deposited in the last 60 days. Get the exemption forms from your local court clerk or legal aid office. Do not wait — if you miss this deadline, you lose the right to claim exemptions and the money is turned over.
- Talk to a bankruptcy attorney this week. Filing bankruptcy triggers an automatic stay — a federal court order under 11 U.S.C. § 362 that stops all collection activity, including bank levies. The automatic stay takes effect the moment you file. Not weeks later. Not after a hearing. The same day. Your attorney can then move to have the frozen funds released. Consultations are usually free. Find a bankruptcy attorney through NACBA. Take the 2-minute bankruptcy quiz to see if the math favors it.
- If you’re on fixed income, disabled, or retired, talk to Damon Day for free about your situation before making any decisions. You may be judgment-proof — meaning collectors legally cannot reach your income or assets.
How to Actually Stop It — Your Four Paths
- File bankruptcy. This is the fastest and most complete option. Chapter 7 or Chapter 13 bankruptcy triggers the automatic stay immediately under 11 U.S.C. § 362, which stops the levy and can force the return of frozen funds that haven’t been turned over yet. If funds were already seized, your attorney may be able to recover them as a preference under 11 U.S.C. § 547 if taken within 90 days of filing. Federal Reserve research shows bankruptcy filers recover faster financially than those who struggle through years of payments.
- File a claim of exemption. If your account holds exempt funds — federal benefits, retirement income, wages below state thresholds, child support you received, or disability payments — file an exemption claim with the court before your deadline. The creditor can object, and a hearing will be scheduled, but your funds remain frozen (not turned over) until the court decides.
- Vacate the default judgment. If you were never properly served with the original lawsuit, or if you had a valid reason for not responding, you can ask the court to vacate (cancel) the judgment. If successful, the levy is released. This works best when you can show you never received notice of the lawsuit.
- Debt consolidation and settlement won’t stop it. Only a court order, exemption claim, or bankruptcy filing releases a bank levy. A debt settlement company cannot unfreeze your bank account.
What the Law Protects — Federal and State Limits
Federal law under 31 CFR Part 212 requires banks to automatically protect two months of direct-deposited federal benefits when they receive a garnishment order. This means the bank must look back at the last two months of deposits, identify any federal benefit payments (Social Security, SSI, VA, federal retirement), and make those funds available to you — no action required on your part. This only applies to direct deposits. If you deposit benefit checks manually, the bank does not have to protect them automatically — you must file an exemption claim yourself.
Beyond the federal protection, state laws vary dramatically. Some states automatically protect a minimum balance; others protect nothing unless you file paperwork:
| State | Automatic Bank Account Protection | Notes |
|---|---|---|
| Federal baseline | 2 months of direct-deposited benefits | Social Security, SSI, VA, federal retirement only |
| New York | $3,840 – $4,080 (varies by region) | 240 times state minimum wage; bank must protect automatically |
| Oregon | $2,500 | Family Financial Protection Act (2024); automatic |
| California | $2,170 | One account per debtor; plus you must file exemption for more |
| Connecticut | $1,000 | Checking accounts only |
| Texas | Current wages exempt | Wages deposited in bank keep exempt status; strong protections |
| Most other states | $0 automatic | You must file an exemption claim to protect any funds |
If you live in a state with no automatic protection — which is most states — the only thing standing between you and losing your money is filing that exemption claim before the deadline. This is why Step 3 above is urgent.
If a creditor froze funds that should be protected, or if you were never properly served with the original lawsuit, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov. You can also find a consumer attorney through NACA.
IRS Bank Levies Are Different
If the IRS froze your account, the rules are different from a creditor levy. The IRS has a 21-day holding period — your bank holds the funds for 21 days before sending them to the IRS. During that window, you can contact the IRS to set up a payment plan, request an Offer in Compromise, or show the levy is causing economic hardship. Call the number on your IRS notice (Form 668-A) immediately. Unlike creditor levies, the IRS can levy without a court judgment — but they must send you a Final Notice of Intent to Levy at least 30 days before the levy.
Steve’s Take
I filed bankruptcy in 1990. I remember exactly what it feels like to check your bank balance and see that your money is just gone. Your stomach drops. You can’t pay rent. You can’t buy groceries. It feels like the financial system has turned against you. Here’s what I learned after helping thousands of people through this: the panic is worse than the problem. A bank levy is just a creditor using the legal system to collect a debt — and that same legal system gives you tools to fight back. If your funds are exempt, file the claim. If the math is broken and this levy is just the beginning, bankruptcy stops it cold and protects everything the creditor is trying to take. The people who come through this best don’t freeze up — they act.
Were the frozen funds federal benefits? If your account holds direct-deposited Social Security, SSI, SSDI, or VA money, you may be judgment-proof, and up to two months of those benefits are automatically protected from garnishment.
Frequently Asked Questions
My bank account was frozen — is my money gone?
Not yet. A freeze means your money is being held — the bank hasn’t turned it over to the creditor. You have a window (typically 10 to 21 days depending on your state) to file an exemption claim or take other legal action. If you file bankruptcy during this window, the automatic stay can force the bank to release the freeze. But you must act before the deadline — once funds are turned over, getting them back is much harder.
My bank account was frozen but I have Social Security direct deposit — are those funds protected?
Yes. Federal law under 31 CFR Part 212 requires your bank to automatically protect two months of direct-deposited federal benefits — including Social Security, SSI, and VA payments. The bank must calculate this amount and keep it accessible to you without you filing anything. This only works for direct deposits. If you cash your check and deposit the cash, the automatic protection does not apply — you would need to file an exemption claim to protect those funds.
Can I open a new bank account to protect my money?
This is the most common mistake. Opening a new account and transferring money after a judgment can be treated as a fraudulent transfer — which makes your legal situation worse and can extend the creditor’s ability to collect. Creditors can also discover new accounts through post-judgment discovery (they can subpoena financial records). Instead of hiding money, protect it legally: file an exemption claim or consult a bankruptcy attorney.
I filed bankruptcy — will that unfreeze my bank account?
Yes. Filing bankruptcy triggers the automatic stay under 11 U.S.C. § 362, which halts all collection activity including bank levies. Your bankruptcy attorney will notify the creditor and the bank. Frozen funds that haven’t been turned over should be released. If funds were already seized within 90 days of filing, your attorney may recover them as a preference under 11 U.S.C. § 547.
Can a creditor freeze my bank account without suing me first?
For most consumer debts (credit cards, medical bills, personal loans), no — a creditor must first sue you, obtain a court judgment, and then get a court order to levy your bank account. The exception is government debts: the IRS can levy your account without a court judgment (though they must send a 30-day notice first), and student loan servicers and child support agencies have special authority to garnish without the typical court process. And if the collector is threatening you but your income is Social Security, read my guide on what to do when a debt collector threatens you on Social Security — they likely cannot touch it at all.
My bank account is frozen — can they take my spouse’s money too?
If it’s a joint account, the entire account may be frozen — even if the judgment is only against one spouse. In community property states (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, Wisconsin), marital funds may be reachable for debts incurred during the marriage. Your spouse may need to file a third-party claim of exemption to release their portion of the funds.
The IRS froze my bank account — what do I do?
An IRS bank levy has a 21-day holding period before funds are turned over. Call the IRS immediately at the number on your levy notice (Form 668-A). You can request a release by setting up an installment agreement, submitting an Offer in Compromise, or demonstrating the levy is creating an economic hardship under 26 U.S.C. § 6343. Unlike creditor levies, bankruptcy may not permanently stop IRS collection if you owe recent tax debts — but it can provide breathing room.
How do I prevent this from happening again?
If a creditor has a judgment against you, they can levy your bank account repeatedly. Each levy is a new order, and they can keep doing it until the judgment is paid. The only ways to stop future levies permanently are: pay the judgment in full, negotiate a settlement (get it in writing), file bankruptcy to discharge the debt, or if you’re judgment-proof, formally notify the creditor that collection efforts are futile.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Bank accounts are often frozen to collect on a default judgment. If a default judgment was entered without your knowledge and then used to freeze your account, you may have grounds to challenge both. See: A Default Judgment Was Entered Against Me. Here’s What to Do Right Now.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A frozen bank account feels like the end, but it’s actually a starting gun — you have a window to act before the money is gone. Check if your funds are automatically protected (federal benefits, state minimums), file an exemption claim before your deadline, and talk to a bankruptcy attorney this week. The automatic stay can unfreeze your account the same day you file.
The Bottom Line
Waking up to a frozen bank account is terrifying — but the legal system that allowed the freeze also gives you tools to fight it. Federal benefits are automatically protected. Many states require a minimum balance to remain untouched. And bankruptcy exists specifically for moments when the math is broken beyond repair. I’ve watched people stare at a frozen account for weeks, paralyzed, while their deadline to act quietly passes. Don’t be that person. The ones who came through this best were the ones who picked up the phone, talked to an attorney, and made a decision within 48 hours. You can do the same. If someone you know just had their account frozen, send them this page — it might be the thing that gets them to act before the deadline passes. Start with the Judgment-Proof Checker to see if collectors can reach you at all, or take the Find Your Path quiz to see all your options side by side.
If it was the IRS that levied your account over back taxes, your options include some the page above doesn’t cover — read The IRS Says I Owe Back Taxes. Here’s What to Do Right Now. for the tax-specific path.
Related: If it is your paycheck rather than your bank account being taken, read the state levy on your paycheck guide — the source and the fix are different.
If you’re retired on a fixed income and your bank account was frozen, federal law protects two months of directly-deposited benefits automatically — see I’m Retired on Fixed Income and Debt Collectors Won’t Stop Calling.
Dealing with a joint account after a split? See what to do when your ex stops paying a joint debt and collectors come after you.
If the account that got frozen was drained by a homeowners association rather than an ordinary creditor, the process and your deadlines are different — see what to do when your HOA is foreclosing on your home.
If you’re also facing eviction while your account is frozen, here’s how to handle both at once — the two cases run on completely different clocks.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
A frozen account often lands hardest on people already squeezed by a job loss or lost income. If that’s you, it helps to understand why the falling unemployment rate is hiding a weaker job market than the headline suggests — so you plan your recovery around reality, not the rosy number.
Part of the Crisis Guide Series: This guide covers what to do when your bank account is frozen. See all available Crisis Guides for other emergency financial situations, including wage garnishment.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



