

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 2, 2026
Quick Answer: A notice from the IRS is scary, but it is not the end. The IRS has only 10 years from the date your tax was assessed to collect it — and it cannot seize anything until it sends you a Final Notice of Intent to Levy and gives you 30 days to request a hearing. You almost certainly qualify for a payment plan, a hardship pause, or in some cases a settlement for less than you owe. And income taxes old enough can even be wiped out in bankruptcy. Don’t ignore the letter — that’s the one move that turns a manageable problem into a levy.
What Just Happened With Your Taxes
The IRS sends a series of letters before it ever takes anything, and the letter you got tells you exactly where you are in that process. The first one is usually a CP14 notice — the official “you have a balance due” letter. It’s a demand for payment, not a seizure. Next comes a CP504, which the IRS calls a “Final Notice” and which warns it can take your state tax refund. The one that matters most is the Letter 1058 or LT11 — the Final Notice of Intent to Levy and Your Right to a Hearing. That is the letter that starts the clock on the IRS’s power to garnish your wages or empty your bank account.
Here’s the part most people miss: the IRS cannot just take your money out of nowhere. By law it has to send that Final Notice of Intent to Levy and wait 30 days first. If you act inside that window, you control what happens next.
The Mistake You’re About to Make: Hiring a “tax relief” company off a late-night ad before you’ve read your own options. The IRS offers payment plans and hardship status for free, directly, in about 15 minutes online. Many tax-relief firms charge thousands of dollars to set up the exact same plan you could get yourself — and some take the fee and do nothing. Before you pay anyone a dime, read your options below. If a company promises to “settle for pennies on the dollar” before reviewing your finances, that’s the sound of your wallet opening.
Your Options Right Now
What to Do in the Next 48 Hours
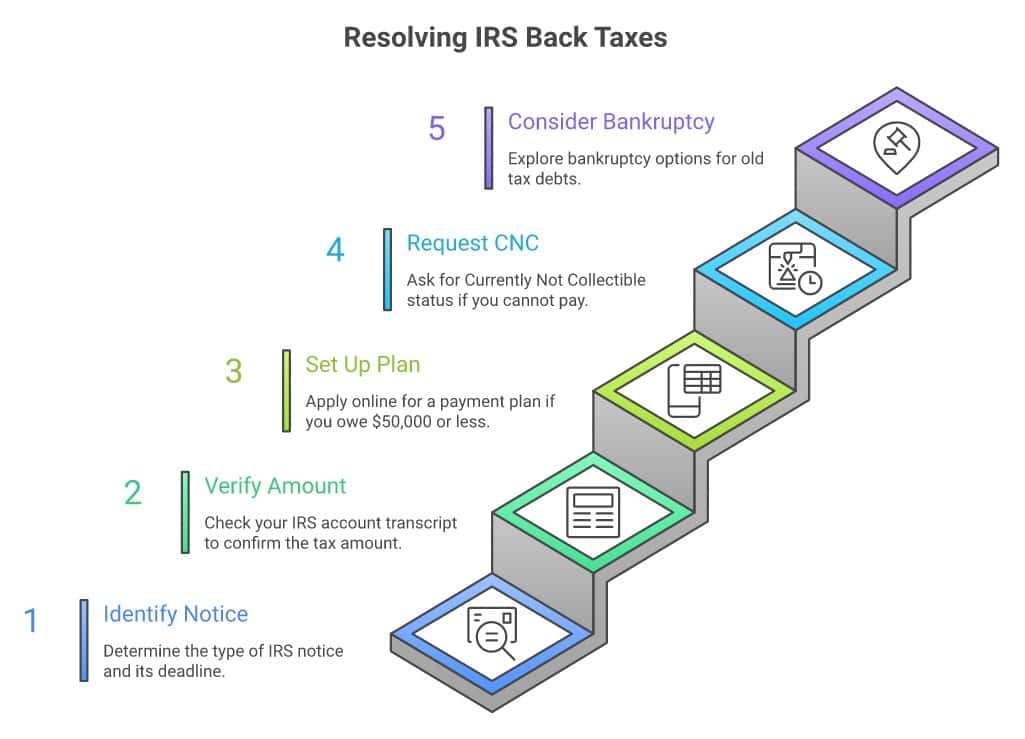
- Find out which notice you have and the deadline on it. If it’s a Letter 1058 or LT11, you have 30 days from the date on the letter to request a Collection Due Process hearing — and the IRS says that deadline cannot be extended for any reason. Circle the date.
- Confirm the amount is even correct. Pull your account transcript at IRS.gov/account. If you have unfiled returns, the IRS may have filed a “substitute return” for you — one that counts all your income but leaves out every deduction, credit, and exemption you’re owed. Substitute returns routinely show a balance two or three times higher than reality. Before you agree to pay anything on a big number, file your actual return first — the balance often drops sharply.
- Set up a payment plan if you can pay over time. If you owe $50,000 or less in combined tax, penalties, and interest, you can apply online in minutes and stretch payments up to 72 months. The setup fee is $22–$178 and is reduced or waived for low-income taxpayers. If you owe less than $100,000 and can pay within 180 days, the short-term plan has no setup fee.
- Ask for “Currently Not Collectible” status if you genuinely can’t pay anything. If paying the IRS would leave you unable to cover rent, food, and utilities, the IRS can mark your account Currently Not Collectible and pause collection — no levies, no garnishment — until your situation improves.
- If the tax is old, ask whether bankruptcy can discharge it. Income taxes that are at least three years old can sometimes be wiped out entirely in bankruptcy. The moment you file, an automatic stay stops every IRS levy and garnishment cold. Find a bankruptcy attorney through NACBA, or talk to Damon Day for free first.
How to Actually Stop It — Your Real Options
- Bankruptcy (the fastest stop, and it can erase old tax debt). Filing triggers an automatic stay that halts IRS levies and wage garnishment the same day. And income tax debt that meets the timing rules below can be discharged — gone, not just paused. Federal Reserve research shows people who file recover financially faster than those who keep struggling.
- Installment agreement (a payment plan). The IRS will almost always say yes. If you owe $50,000 or less, you can set up a long-term monthly plan online in minutes. If you owe less than $100,000 and can clear it within 180 days, there’s a short-term plan with no setup fee at all. Either way, you don’t need to pay a company to do it.
- First-Time Penalty Abatement (ask for it — it’s free). If you’ve filed on time and had no penalties for the prior three years, you can ask the IRS to wipe out your failure-to-file and failure-to-pay penalties under its First Time Abate program. The failure-to-pay penalty alone can reach 25% of what you owe, so this one phone call can shrink the bill significantly — and it costs nothing.
- New for 2025-and-later returns: some penalties are now automatic — no phone call needed. If the penalty is on a tax year 2025 return, or a 2026 quarterly return, ask whether the IRS’s new Automatic Exemption from Penalty (AEP) program already covers you. Starting summer 2026 the IRS says it applies this relief on its own, with no request required, if you have the same clean three-year filing-and-payment history First-Time Abate requires — it’s not a request-based program at all. It’s still being phased in through the rest of 2026, so if a penalty notice shows up anyway on a 2025-or-later return, First-Time Abate above is still your fallback: call and ask. Older tax debt isn’t affected by any of this — it still runs through First-Time Abate as described above. Full breakdown of AEP vs. First-Time Abate.
- Currently Not Collectible status. If you truly can’t pay, this pauses all collection. Interest still adds up, but the IRS leaves your paycheck and bank account alone while you get back on your feet.
- Offer in Compromise (settle for less). The IRS will sometimes accept less than the full amount — but only if you’ve filed all your returns and aren’t in an open bankruptcy. It’s real, but it’s not the “pennies on the dollar” miracle the ads promise. Use the IRS’s free pre-qualifier before you ever pay a firm to apply.
- What WON’T work: Ignoring it (the levy comes), or rolling tax debt into a new high-interest loan or settlement program (you’ve just swapped a debt that can expire and may be dischargeable for one that won’t).
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What You Need to Know About Your Rights
Two federal protections matter most here. First, the Collection Statute Expiration Date: the IRS has 10 years from the date your tax was assessed to collect it, after which the debt legally expires (certain events like bankruptcy or an Offer in Compromise can pause that clock). Second, before the IRS can levy, it must send a Final Notice of Intent to Levy under 26 U.S.C. § 6331 and give you 30 days to request a Collection Due Process hearing.
And here is what the tax-relief ads will never tell you: income tax debt can be discharged in bankruptcy if it clears three timing tests under 11 U.S.C. § 523 and 11 U.S.C. § 507:
| The Rule | What It Means | Why It Matters |
|---|---|---|
| 3-Year Rule | The tax return was originally due (with extensions) at least 3 years before you file bankruptcy | Recent tax debt can’t be discharged — older debt can |
| 2-Year Rule | You actually filed the return at least 2 years before filing bankruptcy | Unfiled returns reset the clock — file them |
| 240-Day Rule | The IRS assessed the tax at least 240 days before you file | A recent audit or assessment delays eligibility |
If all three are met, the income tax can be wiped out like any other debt. This is the single most important thing most people with old tax debt never learn — and it’s why talking to a bankruptcy attorney is worth it even if you think bankruptcy “isn’t for tax debt.” It often is.
One catch worth knowing: if the IRS already filed a tax lien before you file bankruptcy, that lien can survive your discharge. Your personal liability disappears — the IRS can no longer chase you for the money — but the lien may remain attached to property you owned before filing. That’s exactly the kind of detail a good bankruptcy attorney sorts out, and another reason to talk to one before you assume bankruptcy either will or won’t help. A federal IRS lien is different from a county property tax lien — if your county sold your property tax debt to a private investor, here is what to do about that.
If you believe the IRS amount is wrong, or a notice violated your rights, you can file a complaint with the CFPB if a private collector is involved, contact your state attorney general about any “tax relief” company that took your money, and get free help from the Taxpayer Advocate Service, an independent organization inside the IRS. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov, and many law schools run free Low Income Taxpayer Clinics.
Steve’s Take
I filed bankruptcy in 1990, so I know exactly what that pit in your stomach feels like when an official letter shows up. Here’s what 30 years has taught me about IRS debt: the agency is far more reasonable than the late-night ads want you to believe, and far less patient with people who hide. The folks who got hurt weren’t the ones who owed money — they were the ones who threw the envelopes in a drawer until a levy hit their paycheck. The IRS has a payment plan for almost everyone, a pause button for people in real hardship, and a 10-year clock that’s quietly ticking in your favor. This is math, not morality. You’re not a bad person because you owe taxes. Open the letter, learn your options, and act inside the deadline.
Frequently Asked Questions
The IRS says I owe back taxes — can they really take my house or paycheck?
Not immediately, and not without warning. The IRS must first send a Final Notice of Intent to Levy and give you 30 days to request a Collection Due Process hearing under 26 U.S.C. § 6331. If you respond within that window — with a payment plan, a hardship request, or a hearing request — you can stop a levy before it starts.
I can’t afford to pay the IRS anything right now — what are my options?
Ask for Currently Not Collectible status. If paying would leave you unable to cover basic living expenses, the IRS pauses all collection — no levies, no garnishment — and reviews your situation once a year. The debt doesn’t disappear, but the pressure stops.
Can bankruptcy get rid of IRS tax debt?
Sometimes, yes — and this surprises almost everyone. Income tax debt can be discharged in bankruptcy if the return was due at least 3 years ago, you filed it at least 2 years ago, and the IRS assessed it at least 240 days ago (11 U.S.C. § 523). Newer taxes and unfiled returns don’t qualify, so timing is everything. A bankruptcy attorney can pull your transcripts and tell you exactly which years are dischargeable. (Here’s exactly how the timing rules work.)
I filed bankruptcy — how fast does it stop the IRS?
The same day. The moment you file, the automatic stay under 11 U.S.C. § 362 takes effect and halts IRS levies and wage garnishment immediately — not weeks later. Whether the tax itself gets discharged depends on the 3-year, 2-year, and 240-day rules above.
Should I hire a tax relief company to settle my IRS debt?
Be very careful. The IRS offers payment plans and hardship status for free, and you can apply yourself in about 15 minutes. Many “tax relief” firms charge thousands to set up the same plan you could get directly, and some take your money and disappear. Run any company through the Scam-O-Meter first, and use the IRS’s free Offer in Compromise pre-qualifier before paying anyone.
How long can the IRS come after me for old taxes?
Generally 10 years from the date the tax was assessed. After that Collection Statute Expiration Date, the debt legally expires and the IRS must stop collecting. Certain events — filing bankruptcy, submitting an Offer in Compromise, or leaving the country — can pause and extend that clock, so check your transcript to find your real expiration date.
What’s the difference between all these IRS letters I keep getting?
A CP14 is the first “you owe” notice. A CP504 warns the IRS can take your state refund. The one to watch for is a Letter 1058 or LT11 — the Final Notice of Intent to Levy that starts your 30-day clock to request a hearing before the IRS can garnish wages or empty a bank account.
What if the amount the IRS says I owe is wrong?
It happens more than you’d think, often because the IRS filed a “substitute return” for you that left out your deductions. Pull your account transcript at IRS.gov/account, and if the number is wrong, the free Taxpayer Advocate Service can help you fix it without paying anyone.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal or tax advice. Tax law is complex, and your situation may have details that change what options are available to you. For advice specific to your case, consult a tax attorney or enrolled agent. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, the free Taxpayer Advocate Service can help with IRS disputes, or talk to Damon Day for free about your situation.
Key Takeaway: Back taxes are serious but not permanent. The IRS has a payment plan for almost everyone, a hardship pause for those who can’t pay, a 10-year clock that’s running in your favor, and — for old enough taxes — bankruptcy can erase the debt entirely. Use the Find Your Path quiz to see which option fits your numbers, and read the complete guide to IRS back taxes for the full detail on every option. Act inside the deadline on your letter. The longer you wait, the closer a levy gets.
The Bottom Line
Owing the IRS doesn’t make you bad with money — it makes you one of millions of Americans who hit a hard year. Congress built protections into the system precisely because they knew this happens: payment plans, hardship status, a collection clock that expires, and a bankruptcy code that can discharge old tax debt. The people who came through this best weren’t the ones who owed the least — they were the ones who opened the letter and acted before the deadline. If someone you know is panicking over an IRS notice, send them this page — it could be the difference between a payment plan and a garnished paycheck. Start with the Find Your Path quiz to see your real options.
Related: If the levy is from your state rather than the IRS, see what to do when a state levy hits your paycheck — the source and the fix are different.
Related: Can bankruptcy wipe out tax debt — without touching your retirement? The timing rules, the 401(k)/IRA protections, and the expensive mistake to avoid.
Also on this topic: They Said the IRS Will Take Your House and Throw You in Jail for Back Taxes — the common fear about IRS home seizure and jail, and what the law actually says.
The IRS isn’t the only body that can put a lien on your home. A homeowners association can do it over unpaid assessments, and can foreclose on that lien — here’s what to do if your HOA is foreclosing.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



