

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 3, 2026
Quick Answer: A “state levy” on your paycheck means a government agency — almost always a state or local tax authority — is taking money directly from your wages to collect a debt. Unlike a regular creditor, a tax authority usually doesn’t need to sue you first, and the normal 25% garnishment cap may not protect you. Your first move is not to panic — it’s to find out who issued it by calling your payroll/HR department today. Once you know the source, you can almost always set up a payment plan that releases the levy. Don’t ignore it — it keeps coming out every paycheck until the debt is paid or you act.
What Just Happened to Your Paycheck
Your employer received a legal order — a wage levy — directing them to withhold part of your pay and send it to a government agency. Because it came through as a “state levy,” it’s most commonly one of three things: unpaid state income tax, a local tax (in some states, this can include personal property tax on a vehicle, though most property-tax debt is collected through liens rather than wage levies), or a debt that a court turned over to the state for collection.
Here’s why it can blindside you: state and local tax agencies generally don’t have to sue you and win a judgment before they levy — they can do it administratively after sending notices. If those notices went to an old address, or got lost in a stack of mail, the first you hear of it is money missing from your check.
The Mistake You’re About to Make: Guessing what the levy is for and reacting to the wrong thing — or worse, draining your savings or a retirement account to “make it stop” before you even know what you owe or to whom. Don’t. The single most powerful thing you can do in the next 24 hours costs nothing: find out exactly who issued the levy. Everything else depends on that one answer.
Your Options Right Now
What to Do in the Next 48 Hours
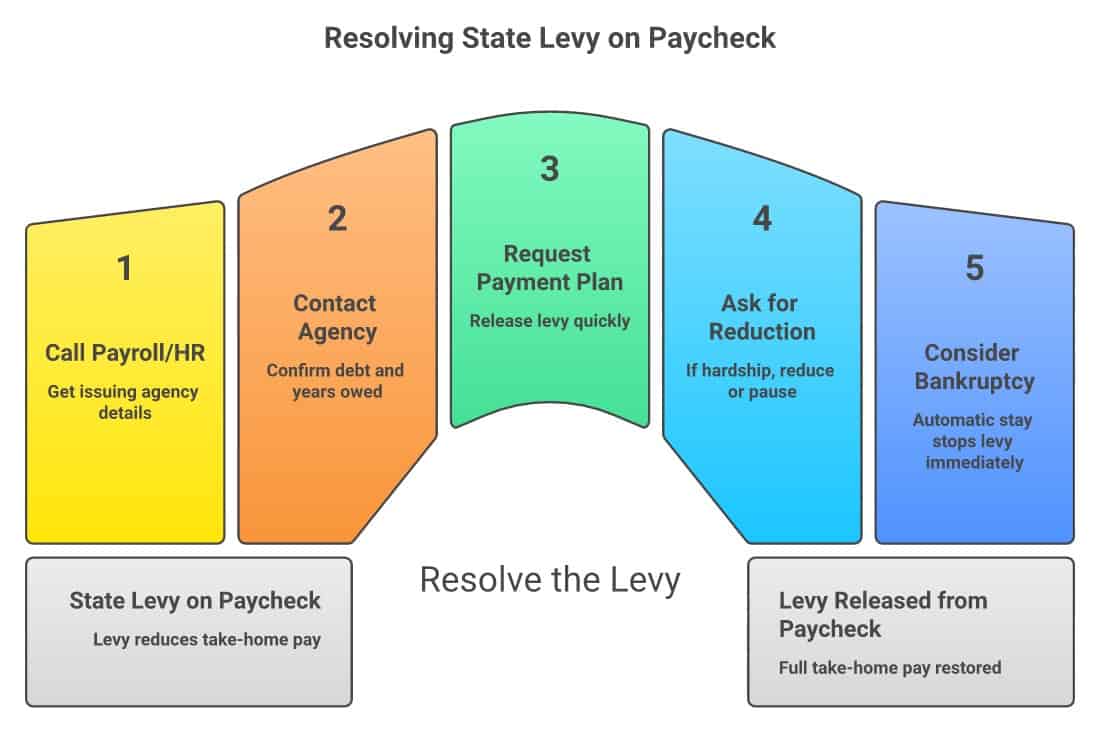
- Call your payroll or HR department first. They received the actual levy paperwork and are legally required to keep it. Ask for the name of the issuing agency and any case or reference number. That reference number is gold — it tells you exactly who to call next. This is the most important step, and it’s free.
- Contact the issuing agency directly — and verify it’s real. Once you know who it is — a state department of revenue/taxation, a county or city treasurer, or a court — look up that agency’s official phone number on its .gov website (not a number from any letter you received, which could be a scam) and call to confirm what you owe, for which years, and whether the balance is correct. Mistakes, outdated balances, and outright fraudulent levy notices all happen. Ask them to send copies of the prior notices too — a levy almost always means earlier warnings went to an old address.
- Ask about a payment plan to release the levy. For most state and local tax debts, setting up an installment agreement will get the levy lifted — often within days. Say plainly: “I want to set up a payment plan and have the wage levy released.” Many agencies do this routinely.
- If the levy is creating real hardship, ask for a hardship adjustment. Most tax agencies can reduce or pause a levy if it leaves you unable to cover basic living expenses. You usually have to ask — they don’t volunteer it.
- Check whether you still have an appeal window. If you recently received a “Final Notice of Intent to Levy,” you may have a narrow window to request a formal hearing that pauses the levy — for federal (IRS) levies it’s 30 days, requested with IRS Form 12153, and most states have an equivalent appeal. If you’re inside that window, act today — missing it removes your automatic right to stop the levy through appeal.
- If the debt is large or this is one of several, bankruptcy’s automatic stay (11 U.S.C. § 362) stops the levy immediately — the day you file, typically halting it by your next payroll cycle. Some older income-tax debt can even be discharged. A free consultation with a bankruptcy attorney tells you whether that fits: find one through NACBA. Talk to Damon Day for free first if you want help thinking it through.
How to Actually Stop It — Your Paths
- Set up a payment plan (the usual fix). For ordinary state and local tax levies, an installment agreement almost always releases the levy — though not always instantly. For IRS levies the release order typically reaches your employer within 1-2 weeks of an approved agreement; state agencies vary, and a few (South Carolina, for example) won’t offer a plan once a levy is in place and require payment in full. This is still the fastest, cheapest path for most people — especially when the balance is a few hundred or a few thousand dollars.
- Prove it’s wrong or already paid. If the balance is incorrect, the debt isn’t yours, or it was already satisfied, contact the agency with proof. Levies do get issued on stale or mistaken balances.
- Bankruptcy’s automatic stay (for large or multiple debts). Filing bankruptcy stops the levy the moment you file — not weeks later. Certain older income taxes can be discharged entirely if they meet the timing rules. Federal Reserve research shows people who file recover financially faster than those who keep struggling. This is the right tool when the debt is big — not for a small vehicle-tax bill.
- What WON’T work: Ignoring it (it keeps coming every paycheck), or paying a “tax relief” company thousands to do what one phone call to the agency can do for free. Be very cautious of anyone who finds you first promising to “settle for pennies.”
What You Need to Know About the Limits on a State Levy
This is the part that surprises people. A regular creditor that sued you and won is generally limited to about 25% of your disposable earnings under federal law (15 U.S.C. § 1673) — a limit the U.S. Department of Labor enforces for ordinary garnishments — and some states protect more. But those creditor caps often don’t apply to tax authorities. Many state tax agencies request around 25% as a standard amount, yet legally can reach further, leaving only a small exempt portion based on your filing status and dependents. This isn’t a loophole — it’s written directly into federal law: 15 U.S.C. § 1673(b)(1)(C) explicitly exempts “any debt due for any State or Federal tax” from the standard garnishment caps that protect you from ordinary creditors. The exact rule then varies by state — South Carolina, for example, can take 25% of gross wages, while California’s general creditor-garnishment rules are more protective (it applies whichever limit is lower) — though even there, the state’s own tax collector operates under separate authority and can reach up to 25% of disposable income. So don’t assume a flat percentage protects you. That’s exactly why identifying the issuing agency matters so much.
| Source of the Levy | Did they need to sue you first? | How to stop it fastest |
|---|---|---|
| State income tax | No — administrative | Payment plan with the state revenue/tax department |
| Local / personal property tax (e.g. vehicle tax) | No — administrative | Payment plan with the county or city treasurer |
| Court judgment sent to the state | Yes — a creditor sued and won | Exemption claim or bankruptcy stay; 25% cap usually applies |
| Child support | Through a court/agency order | Contact the child support agency; different rules apply |
If you live in a state with strong wage protections (like Texas, Pennsylvania, North Carolina, or South Carolina, which sharply limit or bar most creditor wage garnishment) — note that those protections often still don’t stop a tax levy. Check your state’s specific rules with the issuing agency, and see the complete wage garnishment guide for state-by-state details.
If the agency is refusing a reasonable payment plan, the balance is wrong, or you’re being threatened improperly, you can file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov, or connect with a consumer attorney through NACA.
Steve’s Take
I filed bankruptcy in 1990, so I know the cold-stomach feeling of money disappearing that you were counting on. Here’s what 30 years has taught me about levies: the people who got hurt weren’t the ones who owed the money — they were the ones who hid from it or panicked and made it worse. A state levy feels like the government is coming for you. It isn’t. It’s a process, and the agency on the other end deals with payment plans all day long. This is math, not morality. Open the question of who issued it, make the calls, and you’ll almost always find the path is shorter than the fear.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Frequently Asked Questions
A state levy just hit my paycheck — how do I find out what it’s for?
Call your payroll or HR department first. They received the official levy order and are required to keep it on file. Ask for the name of the issuing agency and the case or reference number. That tells you exactly who to call next — usually a state tax/revenue department or a local county/city treasurer.
Can a state take money from my paycheck without suing me first?
Yes, if it’s a tax debt. State and local tax authorities can generally levy your wages administratively after sending notices — they don’t need a court judgment the way a regular creditor does. If the levy came from a court judgment instead, that means a creditor already sued you and won, possibly without your knowledge.
How much of my paycheck can a state levy take?
It depends on the source. A regular creditor with a court judgment is generally capped around 25% of disposable earnings under federal law, and some states protect more. But tax authorities often aren’t bound by that cap and can take more, leaving only a small exempt amount. The exact rule varies by state, so confirm with the issuing agency.
Can I stop a state levy on my wages?
Usually yes. For most state and local tax levies, setting up a payment plan with the agency gets the levy released, often within days. If the balance is wrong, you can dispute it. If the debt is large or you have multiple debts, filing bankruptcy stops the levy immediately through the automatic stay.
I filed bankruptcy — how fast does it stop a state levy?
Immediately. The automatic stay takes effect the moment you file — not weeks later. It halts the wage levy right away. Some older state income tax debt can even be discharged in bankruptcy if it meets the timing rules, which a bankruptcy attorney can confirm in a free consultation.
Could the levy be for unpaid vehicle or property tax?
Yes. In some states, local personal property tax — including the annual tax on cars and trucks — can result in a wage levy. These are handled by your county or city treasurer, not the state, and the balances are usually small. A payment plan with the local treasurer’s office typically releases the levy quickly. If your unpaid property taxes went further and the county actually sold a lien or deed on your home, that is a different clock — see what to do when a property tax lien is sold.
Should I hire a tax relief company to handle the levy?
Be very cautious — especially if a company contacted you first. For most levies, one free phone call to the agency to set up a payment plan does what a relief company would charge you thousands for. The agencies deal with payment arrangements every day. Run any company through the Scam-O-Meter before paying anyone.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A state levy is serious but rarely permanent. Find out who issued it (call payroll today), confirm what you owe, and ask for a payment plan to release it. For large debts, bankruptcy’s automatic stay stops it immediately. The longer you wait, the more paychecks it eats — but the fix is usually one phone call away.
If a state levy isn’t the only thing hitting your paycheck — say a court judgment garnishment is already running too — see my guide on multiple wage garnishments at the same time for how the caps combine.
The Bottom Line
If money vanished from your paycheck today and you don’t even know why, take a breath — you are not in trouble the way it feels, and you are not powerless. A state levy is a process, not a punishment, and the agency behind it sets up payment plans all day long. The people who come through this fastest are the ones who make the calls instead of hiding from the mail. You didn’t fail — a balance went unpaid and the system did what it does, and now you get to fix it. If someone you know just found a levy on their check and is panicking, send them this page — knowing the first step is sometimes the whole battle. Start with the Find Your Path quiz if you’re not sure how big this really is.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



