

In a different financial emergency? This guide is part of our Crisis Guides: Emergency Financial Triage hub — step-by-step help for the moments when something has just gone wrong with your money.
Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 4, 2026
Quick Answer: If you missed the deadline to respond to a debt collection lawsuit, the creditor can ask the court for a default judgment — a win by forfeit that lets them try to garnish wages or levy your bank account. But this is often not the end. You may be able to file a motion to vacate (set aside) the judgment, especially if you were never properly served, have a real defense, or missed the deadline for an unavoidable reason. Deadlines to do this are short and vary by state, so act today. And even if the judgment stands, federal law protects Social Security, SSI, VA benefits, and a large share of your wages. (CFPB)
What Just Happened With Your Case
When you’re sued over a debt, you usually have a set window — often 20 to 30 days, depending on your state and court — to file a written response called an “Answer.” If that window passes with no response, the person suing you can ask the court for a default judgment. That means you lose automatically, not because the debt was proven, but because nobody showed up to contest it.
A default judgment is a real court order. Once a creditor has one, they can return to court for tools to collect it — a wage garnishment, a bank account levy, or a lien on property. A lot of people end up here without ever feeling like they had a fair shot: they were served at an old address, the papers got buried in a stressful month, or they froze up and hoped it would disappear. If that’s you, you are not alone, and you are not out of options.
The Mistake You’re About to Make: Assuming it’s over and ignoring it a second time. A default judgment is the moment many people give up — but giving up is exactly what turns a fixable problem into a paycheck-shrinking one. The other common mistake is the opposite: panicking and emptying a retirement account or taking a high-interest loan to pay it off fast. Don’t do either. Read your options first. Some judgments can be undone, and even the ones that can’t have legal limits on what they can take.
Your Options Right Now
What to Do in the Next 48 Hours
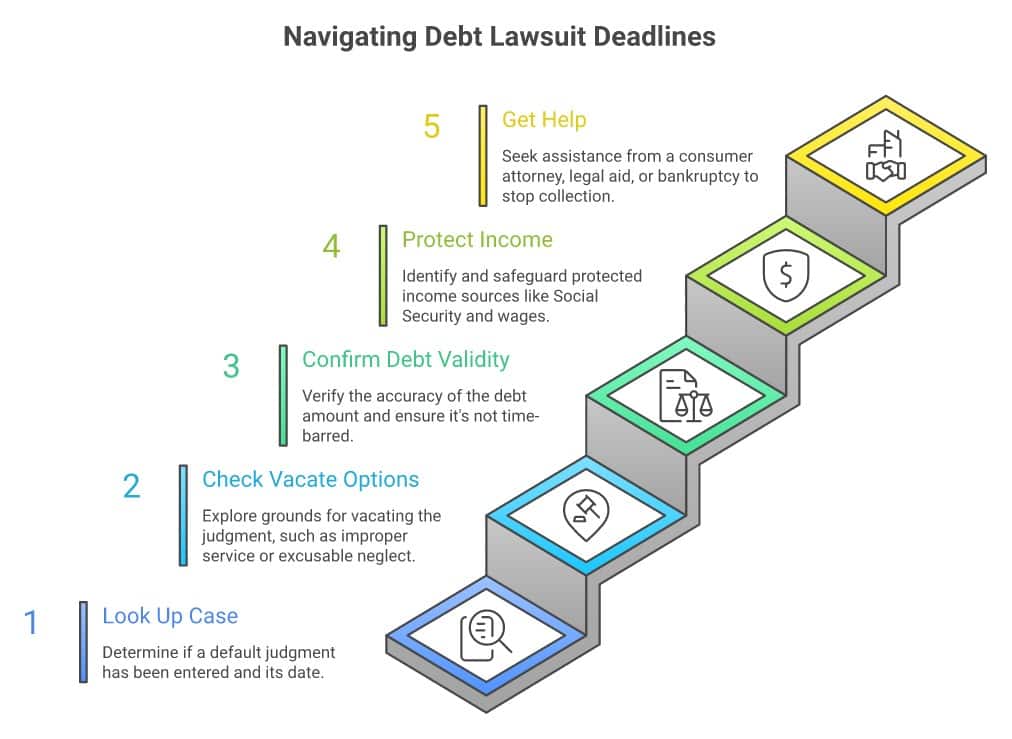
- Find out exactly where your case stands. Look up your case on your court’s online docket or call the clerk. You need to know whether a default judgment has actually been entered yet, and on what date. The date starts your clock for everything below.
- Check whether you can file a motion to vacate the judgment. Courts can set aside a default judgment for reasons like improper service (you were never properly served), excusable neglect (an unavoidable reason you missed the deadline, like a medical emergency), a valid defense to the debt, or fraud. For excusable neglect, deadlines are tight — typically 30 days to one year, and they vary by state. If you were never properly served, you may have stronger grounds, because a court without proper service may have had no authority over you. But don’t assume that gives you unlimited time: in January 2026 the U.S. Supreme Court ruled (in Coney Island Auto Parts v. Burton) that even a motion to vacate a “void” judgment must be filed within a “reasonable time” — so once you know about the judgment, the clock is running. (Improperly serving someone and getting a quiet default — sometimes called “sewer service” — is a documented problem in debt collection, so don’t assume a judgment is valid just because it exists. But the moment you learn of it, treat it as urgent.) Talk to an attorney right away. (Federal Rule 60, the model most states follow)
- Confirm whether the debt was even valid. Was it past your state’s statute of limitations (time-barred)? Is it actually your debt, in the right amount? Did the collector have the right to sue? Any of these can be a defense — and an expired statute of limitations is itself a meritorious defense, which matters because debt buyers frequently sue on time-barred “zombie” debt. If your debt was past the deadline to sue, that can be your strongest grounds to undo the judgment.
- Protect your income immediately. Social Security, SSI, VA benefits, and other federal benefits are protected from private creditors even after a judgment, and your bank must automatically shield two months’ worth of directly-deposited benefits before freezing anything. (That automatic protection applies to electronic direct deposits — if you still receive benefits by paper check, you may have to go to court to protect those funds.) A large share of wages is protected too. If exempt money gets frozen, you can file a claim of exemption with the court to get it released. (CFPB)
- Get help — much of it is free or low-cost. A consumer attorney can often spot a defense or service problem you’d miss, and many take these cases for little upfront because the law can shift fees to the other side. NACA lists consumer attorneys; LSC.gov connects you to free legal aid if you can’t afford one. Or talk to Damon Day for free.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
How to Actually Stop It — Your Paths Forward
- Bankruptcy — the fastest, most complete stop. The moment you file, an automatic stay takes effect immediately — it legally halts wage garnishments, bank levies, and most collection on the judgment, that same day, not weeks later. For most people, bankruptcy can wipe out the judgment debt entirely, and it protects your retirement savings, which you should never drain to pay a judgment. Federal Reserve research shows filers recover faster than those who don’t file. Find an attorney through NACBA or take the 2-minute bankruptcy quiz.
- Motion to vacate the judgment. If you have grounds (improper service, excusable neglect, a real defense), getting the judgment set aside puts you back to square one — able to actually defend the case. This has a deadline measured in days to months, so it’s the one to investigate first.
- Negotiate a settlement on the judgment. Sometimes a creditor will accept a lump sum or payment plan to release the judgment. If you go this route, get every term in writing before you pay a dollar, including that they’ll mark the judgment satisfied.
- What usually won’t fix this: a debt consolidation loan or a debt settlement company. Neither erases a judgment, and a settlement company can leave you exposed to further legal action while fees pile up. A judgment is a legal problem; it needs a legal answer.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What You Need to Know About the Legal Limits on a Judgment
Under federal law (15 U.S.C. § 1673), a creditor generally can’t garnish more than the lesser of 25% of your disposable earnings or the amount by which your weekly pay exceeds 30 times the federal minimum wage — and the U.S. Department of Labor enforces those limits. Many states protect more of your wages than federal law does. Social Security, SSI, and VA benefits are protected from private creditors entirely (42 U.S.C. § 407). One important distinction: regular Social Security and SSDI can have up to 15% taken by federal agencies (like the IRS or Department of Education) for certain government debts — but SSI cannot be touched even for government debts, making it among the most protected income there is. (CFPB)
Also worth knowing: a judgment does not garnish anything by itself. Before a paycheck is touched, the creditor usually has to go back to court for a separate writ of garnishment and serve it on your employer — which means you often have more time to act than the judgment alone suggests. And if a default judgment was entered because you were never properly served, it may be a “void judgment” you can challenge — but, since the Supreme Court’s 2026 Coney Island ruling, you must still act within a “reasonable time” once you learn of it, so move quickly.
| Income or asset | Protection from a private judgment | Notes |
|---|---|---|
| Social Security / SSDI | Fully protected from private creditors | Federal agencies can take up to 15% for some government debts |
| SSI benefits | Fully protected — even from government debts | The strongest protection; cannot be taken even for taxes or student loans |
| VA benefits | Generally fully protected | Keep them in a separate account if possible |
| Wages | At least 75% protected under federal law | Many states protect more; a few protect nearly all |
| Directly-deposited benefits in a bank | Two months auto-protected | Bank must shield before freezing |
If you live in a state with strong debtor protections, what a creditor can actually collect may be far less than the judgment suggests. Four states — Texas, Pennsylvania, North Carolina, and South Carolina — prohibit wage garnishment for ordinary consumer debts entirely. Two important caveats: this doesn’t cover taxes, child support, or federal student loans, and the ban is on garnishing your paycheck — a creditor in these states can still try to levy your bank account after the wages land there, so don’t assume money sitting in checking is safe. Florida offers a strong “head of family” exemption: if you provide more than half the support for a dependent and your disposable earnings are $750 a week or less, they’re fully protected — but you generally must respond to the garnishment notice to claim it, so don’t ignore the paperwork. Check your own state’s rules, because they can change the whole picture. (CBS News)
If a collector is breaking the rules — trying to seize exempt benefits, garnishing more than the law allows, or collecting on a judgment that was never properly obtained — file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, so I know the particular dread of a legal document with your name on it and a number you can’t pay. Here’s what thirty years has taught me: a default judgment feels like a verdict on you as a person, and it isn’t. It’s a procedural event, and procedural events can often be undone or contained. The people I’ve watched come through this best are not the ones who had the most money — they’re the ones who opened the envelope, found out exactly where they stood, and moved within the deadline instead of freezing. You can be one of those people. Today, not someday.
Heard that you “never have to pay a debt collector”? That viral advice is half-true in a dangerous way — the rights are real, but ignoring a lawsuit is exactly how a default judgment happens.
Frequently Asked Questions
I missed the deadline to respond to my debt lawsuit — is it too late to do anything?
Often, no. If a default judgment hasn’t been entered yet, you may still be able to file a late response. If it has been entered, you may be able to file a motion to vacate (set aside) the judgment — especially if you were never properly served, have a valid defense, or missed the deadline for an unavoidable reason. These motions have tight, state-specific deadlines, so act immediately.
A default judgment was entered against me — can I still get it removed?
Possibly. Courts can set aside a default judgment for improper service, excusable neglect, a meritorious defense, or fraud. If you were never properly served, the time limit to challenge it is sometimes much longer than usual. Look up your judgment date and check your state’s rules right away, because most other grounds must be raised within a short window.
What can a debt collector actually do to me with a default judgment?
With a judgment, a creditor can go back to court to garnish wages, levy a bank account, or place a lien on property — but there are legal limits. Federal law caps wage garnishment, protects Social Security, SSI, and VA benefits from private creditors, and requires banks to shield two months of directly-deposited federal benefits before freezing an account.
Can they take my Social Security or disability if I have a judgment?
Not for ordinary consumer debts. Social Security, SSDI, SSI, and VA benefits are protected from private creditors even after a judgment. If those funds are mistakenly frozen, you can file a claim of exemption with the court to get them released. Keeping benefits in a separate account makes them easier to protect.
I filed bankruptcy — how fast does it stop a garnishment from a judgment?
Immediately. The moment you file bankruptcy, an automatic stay takes legal effect and halts wage garnishments, bank levies, and most collection on the judgment — that same day, not weeks later. For many people, bankruptcy can also discharge the underlying judgment debt entirely.
Should I just pay the judgment to make it go away?
Not before you understand it. First confirm the judgment is valid and check whether you can vacate it. If you do choose to pay or settle, get every term in writing — including that the creditor will mark the judgment satisfied — before paying a dollar. Never drain retirement savings to pay a judgment; that money is generally protected and you’ll need it later.
Will a default judgment ruin my credit forever?
A judgment is serious, but not permanent. Its credit impact fades over time, and resolving it — by vacating, settling, or discharging it in bankruptcy — starts the recovery. Credit scores often rise after bankruptcy precisely because the underlying debt is gone. The worst thing for your credit and your peace of mind is to do nothing.
Can a debt settlement company fix a judgment for me?
No. A judgment is a legal matter that a settlement company cannot undo, and enrolling can leave you exposed to continued collection while fees accumulate. A judgment needs a legal answer — a motion to vacate, a negotiated release in writing, or bankruptcy. Talk to a consumer attorney through NACA or a bankruptcy attorney through NACBA instead.
If I get the default judgment vacated, am I done?
Not quite — vacating the judgment reopens the lawsuit, it doesn’t end it. You’re back to where you would have been if you’d responded on time: you now have to file an Answer and actually defend the case. That’s a good position to be in, because you can raise defenses like an expired statute of limitations or the wrong amount — but don’t mistake a vacated judgment for a dismissed case.
Can I just wait out a default judgment until it expires?
Usually not. Most states let creditors renew a judgment before it expires — often every 10 years — so waiting rarely makes it disappear and interest can keep accruing the whole time. Meanwhile the creditor can garnish or levy. It’s almost always better to address the judgment than to hope it lapses.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
If a default judgment was already entered: Missing the lawsuit deadline is one thing — but if the default judgment itself has now been formally entered, that opens a different set of options. See my guide: A Default Judgment Was Entered Against Me. Here’s What to Do Right Now.
Important: This guide is for informational purposes only and is not legal advice. Laws and deadlines vary significantly by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A default judgment is serious but often not final. Find out your judgment date, check immediately whether you can vacate it, and protect your exempt income. The longer you wait, the harder it is to undo — so move within the deadline, this week. Start with the Find Your Path quiz to see your options.
The Bottom Line
Missing a court deadline doesn’t make you irresponsible — it makes you human, usually a human who was scared or overwhelmed by a process built to be confusing. The law has more off-ramps than the collector’s letter wants you to know about: judgments can be vacated, exempt income can’t be touched, and bankruptcy can stop the whole thing the day you file. The people who come through this best are simply the ones who opened the envelope and acted before the clock ran out. If someone you know is hiding from a debt lawsuit or a judgment they think is hopeless, send them this page — knowing they still have moves can be the difference between freezing and fighting back. See all your options here.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Related: If you never knew you were sued, it may have started with a process server you avoided — or one who never really served you. A Process Server Is Trying to Find Me. Here’s What to Do Right Now.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



