

Quick Answer: A “nonprofit” credit counseling agency is not held to the same legal duty your doctor or a registered financial adviser owes you. There is no federal fiduciary standard requiring a credit counseling agency to put your interests first. The creditor kickback that built this industry — “fair share” — has shrunk over the years, but the structural reason agencies push you toward a Debt Management Plan never went away. The funding changed clothes. The conflict did not.
Expert Context: I founded and ran a credit counseling organization for over a decade before I ever wrote a word about debt. I sat in the rooms where the funding model was discussed. So when I tell you the word “nonprofit” doesn’t mean what you think it means in this industry, I’m not theorizing — I watched it work from the inside.
Here’s a question almost nobody asks: if a nonprofit hospital’s doctor gives you negligent advice, that’s malpractice — because a doctor owes you a legal duty of care. So why, when a “nonprofit” credit counseling agency steers you into the wrong plan, is there no equivalent accountability at all?
That question sits at the heart of something I’ve wanted to explain plainly for a long time. We trust the word “nonprofit.” It sounds like “charity,” like “on your side,” like “no angle.” But in the debt world, nonprofit status is a tax classification — not a promise about whose interests come first. And the gap between what people assume and what the law actually requires is enormous.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 11): You drive to the dealership to pick up the car. There is no car. There was never a car.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
I’ve already written about how credit counseling agencies actually make money and whether credit counseling is worth it after running one myself. This post is about something narrower and, I think, more important: the accountability gap, and why the reforms you were told fixed this industry left the engine running.
The double standard nobody talks about
Think about who you turn to when your money is on fire. Maybe a financial adviser. And here’s something most people don’t know: a Registered Investment Adviser is legally required — by statute, under the Investment Advisers Act of 1940 — to act as your fiduciary. That means putting your interests ahead of their own, disclosing every conflict of interest, and giving advice that is in your best interest. The Securities and Exchange Commission, in its 2019 interpretation of that standard, said the duty is “imposed by operation of law” and cannot be negotiated away.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
No equivalent federal fiduciary standard applies to credit counseling agencies. They must meet organizational integrity requirements under the Bankruptcy Code (11 U.S.C. § 111) and the tax-exempt rules in IRC Section 501(q) — but neither law imposes a legal duty to act in your best interest. (State laws vary, and a few states may impose higher standards, but there is no uniform federal best-interest requirement.)
So sit with the comparison. A doctor at a nonprofit hospital owes you a duty of care, and breaching it is malpractice. A financial adviser owes you a fiduciary duty. A “nonprofit” credit counseling agency — handling one of the most consequential financial decisions of your life — owes you neither. Same comforting “nonprofit” label. Wildly different accountability.
Key Terms Defined
Fiduciary duty: A legal obligation to act in another person’s best interest, putting their interests ahead of your own and disclosing all conflicts. Registered Investment Advisers have it. Credit counseling agencies are not held to it.
Fair share: The payment a creditor returns to a credit counseling agency — historically a percentage of the payments you make through a Debt Management Plan. The original funding engine of the industry.
Debt Management Plan (DMP): A repayment program run by a credit counseling agency where you make one monthly payment to the agency, which distributes it to your creditors, often at reduced interest. It is the product the agency earns money on.
Who created credit counseling — and why that matters
Credit counseling didn’t grow out of a consumer movement. The agencies were largely created by creditor banks and credit card companies in the late 1950s and 1960s to reduce their own default losses. The funding mechanism was “fair share” — when you made payments through a Debt Management Plan, the creditor sent a percentage back to the agency.
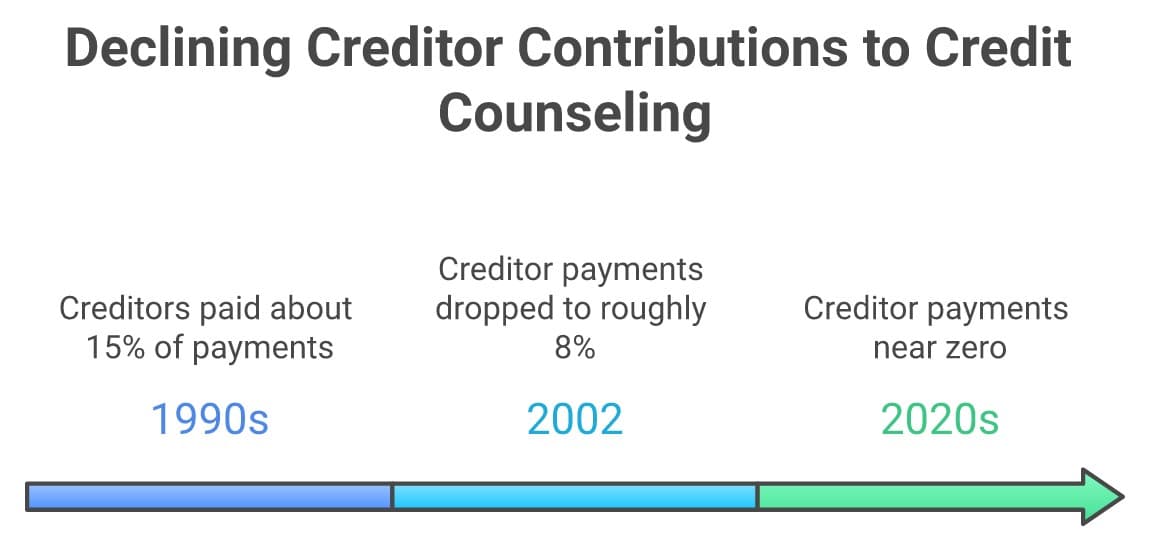
At its peak, that fair share return ran roughly 12 to 15 percent of the payments collected, according to the U.S. Senate’s 2005 Permanent Subcommittee on Investigations report. In one year, member agencies of the largest network received as much as $360 million in fair share payments.
“In the late 1950s, credit card issuers played a key role in developing what we refer to today as the credit counseling industry.”
— U.S. Senate Permanent Subcommittee on Investigations, Profiteering in a Non-Profit Industry (2005)
Consumer advocates noticed the obvious problem early. As the Uniform Law Commission documented in 2005, some came to perceive these agencies as “debt collectors for the credit-card industry” — and a later wave of them “uncritically enrolled all their customers in DMPs.” When the people whose job is to advise you are paid by the people you owe, that’s not a conspiracy theory. It’s just how the money flows.
That investigation, by the way, was scathing. It found agencies enrolling people in Debt Management Plans with little or no actual counseling — because the DMP, not the counseling, was the revenue. The IRS came down hard afterward: it examined the 63 largest credit counseling organizations and revoked, proposed revoking, or terminated the tax-exempt status of organizations representing 41 percent of the industry’s revenue. The IRS Commissioner at the time said these agencies had “poisoned an entire sector of the charitable community.”
The reform that capped the label, not the incentive
Congress responded in the Pension Protection Act of 2006, which added IRC Section 501(q). It tightened governance rules and capped creditor-sourced DMP payments at no more than 50 percent of an agency’s total revenues. That was a real constraint on the most extreme cases — an agency can no longer be almost entirely creditor-funded and keep its tax exemption.
But here’s what 501(q) did not do, and this is the part that matters:
- It did not prohibit fair share payments. Creditors can still pay agencies a cut of what you pay through a DMP.
- It did not cap the rate creditors pay. It capped the share of total revenue — not the percentage.
- It did not require agencies to counsel you toward the best option for you, including bankruptcy. No fiduciary duty was added.
- It did not eliminate the structural incentive to enroll you in a DMP.
Now follow the money, because this is the crux. Up to 50 percent of an agency’s revenue can still legally come from creditors through DMP-related payments. And the fees you pay — the setup fee, the monthly service fee — are not counted against that 50 percent cap at all. So an agency could draw 49 percent of its revenue from creditor fair share and another 49 percent from the monthly fees its DMP clients pay, and be 98 percent dependent on DMP enrollment — while remaining fully compliant with the law that supposedly fixed this.
The Claim: The 2006 reforms cleaned up credit counseling, so a “nonprofit” agency today is independent and free of creditor influence.
The Reality: The reforms capped how concentrated creditor funding can be — but left the financial architecture intact. The agency still earns more when you enroll in a Debt Management Plan, whether that money comes from the creditor or from your own monthly fees. The kickback shrank. The reason to steer you toward a DMP did not.
Fair share fell. The grip didn’t.
It’s true that fair share has been sliding for years. What began around 15 percent fell to an average of about 8 percent by 2002, according to the largest network’s own trade data as reported in a landmark 2003 study by the Consumer Federation of America and the National Consumer Law Center. The network itself later described the drop as “precipitous” in filings with the Consumer Financial Protection Bureau. By the early 2020s, some creditors had stopped paying fair share entirely.
You might think that solves the problem on its own. It doesn’t — because as fair share fell, the consumer-paid fees rose to replace it. Both revenue streams point the same direction: the agency does better when you sign up for a DMP. Whether the check comes from the bank or from your checking account, enrollment is still where the money is.
I can’t tell you that every agency today acts on that incentive the way the worst actors did twenty years ago — no public study measures current steering, and I won’t claim one does. But the incentive was never removed from the law. And the CFPB still lists DMP-first pressure as a red flag — telling you a Debt Management Plan is your only option before they’ve spent real time on your finances. Regulators don’t keep warning about a danger they believe is retired.
And here’s why this isn’t ancient history. Right now, as I write this, credit card delinquencies have hit a 15-year high — 13.1% of balances are seriously past due. The NFCC’s own Bruce McClary describes what’s happening to ordinary families as “survival debt”: people charging groceries and medicine just to get by. Counseling demand is surging. So the people most likely to walk into a credit counseling office today are the most desperate and the least able to absorb a wrong recommendation — which is exactly the moment that whose-interest-comes-first stops being academic.
The silences that tell you the most
When I’m trying to understand an industry, I pay as much attention to what isn’t said as to what is. Here are four silences worth noticing.
They don’t tell you how often bankruptcy would serve you better. No public study quantifies how often credit counseling agencies recommend bankruptcy first instead of a DMP. What is documented is the incentive: an agency earns fair share and fees from a DMP, and earns nothing — zero — from telling you to file bankruptcy. The Senate found that some agencies even operated under contractual minimum enrollment quotas.
They don’t publish their success rates. Credit counseling agencies do not, as a standard practice, disclose what percentage of people actually finish a Debt Management Plan. The American Bankruptcy Institute has flatly noted that “the credit counseling industry does not publicly report their success rate.” Independent and industry-insider estimates put completion in the range of 20 to 35 percent; industry-affiliated figures run higher, 55 to 70 percent. No government-verified, independently audited number exists — and the wide gap itself is a product of the missing disclosure.
They aren’t bound to act in your best interest. We covered this — no fiduciary duty. It bears repeating because it’s the whole game.
They don’t criticize the creditors who fund them. An organization funded in part by creditors has an obvious structural reason not to bite the hand. In researching this, I found no public statement by a major credit counseling agency calling out a specific bank or credit card company by name for an interest-rate, fee, or lending practice that harms the very consumers they counsel. I can’t prove that no such statement exists anywhere. So don’t take my word for it — go look. Search the websites of the big agencies and the national network for a single instance of them naming a creditor’s harmful practice. Notice what you find, and what you don’t.
Key Takeaways
- “Nonprofit” is a tax status, not a promise that an agency puts your interests first.
- Credit counseling agencies are not held to a fiduciary duty — unlike registered financial advisers.
- The 2006 reforms capped how concentrated creditor funding can be, but didn’t end the incentive to enroll you in a Debt Management Plan.
- As creditor “fair share” payments shrank, consumer-paid fees rose to replace them — both reward DMP enrollment.
- Agencies don’t publicly publish DMP completion rates, and they earn nothing when bankruptcy is the better answer for you.
Want a recommendation based on your actual numbers — not someone’s revenue model? Take the free Find Your Path quiz. It walks through your real situation and points to the option that fits you, including the ones nobody earns a commission on. If you want to talk it through with a human who sells nothing, Damon Day will take your call for free. And if you think bankruptcy might be on the table, the National Association of Consumer Bankruptcy Attorneys and the National Association of Consumer Advocates can help you find a real attorney.
The Bottom Line
If you’ve been carrying this quietly — embarrassed, scared, sure that signing up with a “nonprofit” was the safe and responsible thing to do — please hear me: you did nothing wrong by trusting the label. The system is built so the label does the persuading. But you deserve advice from someone who earns exactly the same whether you say yes or no, because that’s the only advice you can be sure is about you. Debt is math, not morality, and the math has more than one answer — including some, like bankruptcy, that no one profits from recommending. You are not your debt, and you are allowed to ask the hard question out loud: whose interest is this advice really serving? Once you start asking that, you’re already on your way out.
Frequently Asked Questions
Is nonprofit credit counseling independent?
Not in the way most people assume. “Nonprofit” is a tax classification, not a guarantee of impartiality. The agencies were largely created by creditors to reduce defaults, and they earn money — through creditor “fair share” payments and through your own monthly fees — when you enroll in a Debt Management Plan. There is no federal law requiring them to act in your best interest.
Do credit counseling agencies have a fiduciary duty to me?
No federal fiduciary standard applies to them. A Registered Investment Adviser is legally required under the Investment Advisers Act of 1940 to act in your best interest. Credit counseling agencies operate under organizational and tax-exempt rules (11 U.S.C. § 111 and IRC 501(q)) that impose no equivalent best-interest duty. State laws vary.
Didn’t the 2006 reforms fix the conflict of interest?
They reduced the most extreme version of it. IRC Section 501(q) capped creditor-sourced DMP payments at 50 percent of an agency’s total revenue and added governance rules. But it did not ban fair share payments, did not cap the rate creditors pay, and crucially did not count the fees you pay against that cap. An agency can remain heavily dependent on DMP enrollment for its revenue and still be fully compliant.
Why doesn’t credit counseling recommend bankruptcy more often?
No public study measures how often they do or don’t. What’s documented is the incentive: an agency earns fair share and monthly fees from a Debt Management Plan and earns nothing from a bankruptcy referral. That doesn’t mean any given agency is steering you wrong — but it’s a reason to get a second opinion from someone with no stake in the outcome.
What should I do instead?
Get your options from a source that doesn’t profit from your choice. Compare all of them — including bankruptcy — using a tool built on your numbers, not a sales funnel. Take the free Find Your Path quiz, talk to a no-cost independent voice like Damon Day, and if bankruptcy may fit, consult a consumer bankruptcy attorney. The goal isn’t to pick the option someone else earns money on — it’s to pick the one that’s right for you.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



