

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 8, 2026
Quick Answer: When you signed a personal guarantee, you became personally liable for the business debt — your LLC or corporation does not protect you, because the guarantee is a separate contract between you and the lender. The lender can sue you, win a judgment, and then garnish wages or levy your bank account. But you have real protection: filing personal bankruptcy can discharge a personal guarantee on most business debt, and the automatic stay (11 U.S.C. § 362) stops collection the moment you file. Don’t sign anything new and don’t drain your retirement before you read your options. This gets worse if you ignore it — not better.
What Just Happened to Your Personal Liability
You started a business the right way — you formed an LLC or corporation so that if things went bad, the business’s debts would stay with the business and not follow you home. That part was smart, and it’s still true for most of what the business owed.
But somewhere along the way, a lender asked you to sign a personal guarantee. Banks ask for them on almost every small business loan. SBA loans require them. Equipment leases, commercial leases, business credit cards, lines of credit, and merchant cash advances almost always include one. The moment you signed it, you made a second, separate promise — this one directly from you, the human being, to the lender.
That’s the trap people don’t see coming: the corporate shield protects you from the business’s liability, but a personal guarantee is a separate contract between you and the lender. So when the business defaults, the lender doesn’t sue your dead company — it sues you. And if more than one person signed, or you signed “jointly and severally,” the lender can come after any one guarantor for the entire balance, not just a share.
The Mistake You’re About to Make: When the lender calls, panicked guarantors do one of three things that make it worse — they sign a new repayment agreement or a confession of judgment without legal advice (giving away defenses they didn’t know they had), they ignore the lawsuit and let a default judgment sail through, or they cash out a 401(k) to pay it down. That last one is the cruelest: most retirement money is protected from creditors under 11 U.S.C. § 522 (401(k)s and pensions have unlimited protection; IRAs are protected up to about $1.7 million), so draining it converts protected money into the lender’s money — and adds a tax bill on top. Read your options before you sign or spend anything.
Your Options Right Now
What to Do in the Next 48 Hours
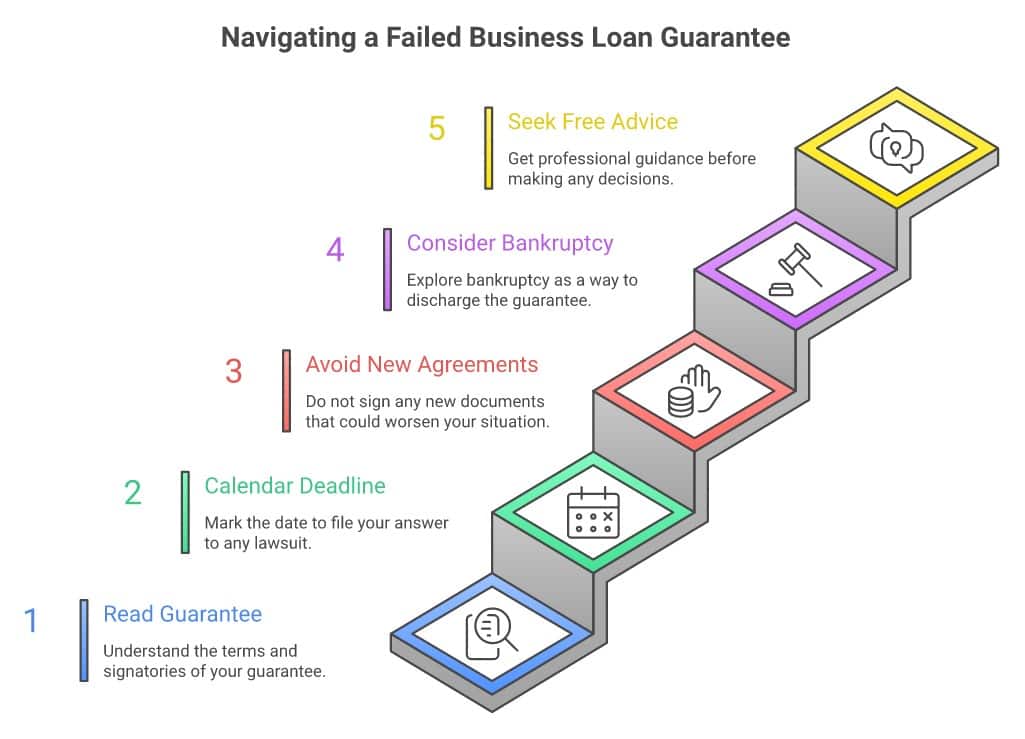
- Find your guarantee and read it. Was it limited (a dollar cap) or unlimited? Did anyone else sign? Is there a confession-of-judgment clause? You can’t make a good decision until you know exactly what you signed.
- If you’ve been served with a lawsuit, calendar the deadline TODAY. In most state courts you have roughly 20 to 30 days to file a written answer (the federal benchmark is 21 days under FRCP 12(a)) — check your summons for the exact date. Miss it and the lender wins automatically by default.
- Do not sign anything new without legal advice. No new repayment agreement, no confession of judgment, no “just sign here and we’ll work with you.” Once you sign away a defense, it’s gone.
- Understand the bankruptcy option — it discharges the guarantee. Personal Chapter 7 or 13 can wipe out your personal liability on the guarantee, and the automatic stay stops every lawsuit, garnishment, and levy the instant you file — not weeks later. Find a bankruptcy attorney through NACBA, and take the 2-minute bankruptcy quiz to see if the math favors a fresh start.
- Talk it through with someone who has no product to sell you. Talk to Damon Day for free before you hand money or a signature to anyone.
How to Actually Stop It — Your Paths
- Personal bankruptcy (the fastest stop). A Chapter 7 discharge eliminates your personal liability on a guaranteed business debt under 11 U.S.C. § 727, and SBA and bank business debt is generally dischargeable like any other contract debt. The automatic stay halts collection the moment you file. Federal Reserve research shows people who file recover faster than those who don’t.
- Negotiate a settlement — but get it in writing. Lenders often accept a lump sum for less than the full balance once the business is closed and there’s nothing left to collect. For SBA loans this is a formal Offer in Compromise (see below). For private debt, never pay a dime until you have a signed agreement that the payment fully releases your guarantee.
- Defend the lawsuit if you have grounds. Was the guarantee properly signed? Has the statute of limitations run? Did the lender fail to mitigate? An attorney can spot defenses you can’t. NACA can connect you with a consumer attorney.
- What WON’T work: A debt consolidation loan (you can’t borrow your way out, and a closed business has no income to qualify), a debt settlement company (they have no special power over a sophisticated commercial lender), or simply hoping it goes away. Ignoring it produces a default judgment, which is the worst outcome.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
What You Need to Know About SBA and Federal Loans
If your guarantee is on an SBA loan — a 7(a) loan or a COVID EIDL over $200,000 — the rules are different and more dangerous, because the federal government can collect without ever taking you to court.
Here’s the part most people never hear: a private lender usually has to sue you and win before it can garnish anything. Federal debt skips the courtroom. Once an SBA loan goes into default and gets referred to the U.S. Treasury, the government can use Administrative Wage Garnishment to take up to 15% of your disposable pay with no judge involved (31 U.S.C. § 3720D), and the Treasury Offset Program can seize your federal tax refund and benefits (31 U.S.C. § 3716).
The good news: SBA debt is still dischargeable in personal bankruptcy, and before bankruptcy you can apply for an SBA Offer in Compromise — a formal request to settle for less than the full balance (legal authority: 31 U.S.C. § 3711). It uses SBA Form 1150 (the offer) and SBA Form 770 (your financial statement), and it’s generally available after the business has closed and any collateral has been sold. See our deeper guides: what happens when you can’t repay an SBA EIDL loan and how to find an attorney to help with your SBA loan.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Beware the Confession of Judgment (Especially With Merchant Cash Advances)
If your business took a merchant cash advance, your guarantee may include a confession of judgment — a clause where you pre-signed away your right to be sued and to defend yourself. The lender just files your signed affidavit with a court clerk and gets an instant judgment, no lawsuit required.
New York closed its most abused loophole effective August 30, 2019: under N.Y. CPLR § 3218, a confession of judgment can now only be filed where the debtor lived — which stopped MCA lenders from filing in New York against out-of-state business owners nationwide. But the protection only helps out-of-state borrowers; New York businesses are still exposed. Learn how this clause works in our full explainer on confessions of judgment and how business debt collection differs from consumer debt.
Where You Live Changes What They Can Take
| Protection | Rule | Notes |
|---|---|---|
| Federal wage garnishment (private lender) | Lesser of 25% of disposable pay or amount over 30× federal minimum wage | 15 U.S.C. § 1673 — requires a judgment first |
| Federal SBA debt (Treasury) | Up to 15% of disposable pay | No judgment needed — 31 U.S.C. § 3720D |
| Florida homestead | Unlimited home equity protected | FL Const. Art. X, § 4 |
| Texas homestead | Unlimited home equity protected | TX Const. Art. XVI, § 50 (acreage limits apply) |
If you live in Florida or Texas, your home equity is generally protected from a business-debt judgment with no dollar cap. One important caution: if you file bankruptcy, federal law (11 U.S.C. § 522(p)) caps the homestead exemption at about $214,000 (for cases filed through March 2028) if you bought the home within roughly 3.3 years (1,215 days) before filing — even in Florida or Texas. Long-time homeowners keep the unlimited state protection. Texas, Pennsylvania, North Carolina, and South Carolina generally don’t allow wage garnishment for ordinary private debts — but that protection ends once wages hit your bank account (where they can be levied) and it does not stop federal SBA garnishment. Exemptions vary widely by state, so confirm your own state’s rules with an attorney.
If a lender or collector is violating the law — threatening you over a debt that isn’t yours, or collecting after a bankruptcy discharge — file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, so I know exactly what it feels like to have your name — not your company’s, your name — on a debt you can’t pay. The shame is the heaviest part, and it’s also the most useless. You took a risk to build something. That makes you brave, not bad with money. The math is simple: a personal guarantee on a failed business is dischargeable debt, the law gives you an automatic stay the moment you file, and your retirement is protected if you don’t touch it. I’ve watched thousands of people in this exact spot. The ones who moved fast, didn’t sign anything in a panic, and got real advice came out the other side. The ones who froze and let a default judgment land did not. Act while you still have all your options.
Frequently Asked Questions
My business was an LLC — why am I personally liable for the loan?
Because you signed a personal guarantee, which is a separate contract between you and the lender. The LLC protects you from the business’s debts, but the guarantee is a direct promise from you as an individual. The lender enforces it against you personally, not against the closed company.
I personally guaranteed a business loan — can bankruptcy erase it?
Generally yes. A personal Chapter 7 or 13 bankruptcy can discharge your personal liability on a guaranteed business debt, including most SBA and bank loans, under 11 U.S.C. § 727. The exception is debt obtained by fraud — such as a materially false financial statement on the loan application (11 U.S.C. § 523).
I filed bankruptcy — how fast does it stop the lawsuit and garnishment?
Immediately. The automatic stay (11 U.S.C. § 362) takes effect the moment your petition is filed — not weeks later. It halts the lawsuit, any wage garnishment, bank levies, and lien enforcement against you.
Can the SBA garnish my wages without suing me?
Yes. Unlike a private lender, the federal government can use Administrative Wage Garnishment to take up to 15% of your disposable pay with no court judgment under 31 U.S.C. § 3720D, and the Treasury Offset Program can seize your tax refund. This is why SBA debt needs urgent attention.
Should I cash out my 401(k) to pay off the personal guarantee?
No. Most retirement accounts are protected from creditors under 11 U.S.C. § 522 — 401(k)s and pensions have unlimited protection, and IRAs are protected up to about $1.7 million. Cashing one out turns protected money into money the lender can take, and triggers income tax plus an early-withdrawal penalty. Talk to an attorney before touching retirement funds.
The lender wants me to sign a confession of judgment — should I?
Not without legal advice. A confession of judgment lets the lender get a judgment against you with no lawsuit and no chance to defend yourself. It’s common in merchant cash advance deals and it surrenders rights you may not know you have. Have an attorney review it first.
Can they take my house over a business debt?
It depends on your state. In Florida and Texas, home equity is generally protected from a judgment with no dollar cap (FL Const. Art. X, § 4; TX Const. Art. XVI, § 50). Other states have lower or no homestead caps. And if you file bankruptcy, a federal cap of about $214,000 (11 U.S.C. § 522(p)) can apply to a home you bought within about 3.3 years before filing, even in Florida or Texas. Confirm your state’s homestead exemption with an attorney before assuming your home is — or isn’t — at risk.
How long do I have to respond if I’m sued on the guarantee?
Usually 20 to 30 days from the date you’re served, depending on your state (the federal benchmark is 21 days under FRCP 12(a)). Check your summons for the exact deadline. Missing it lets the lender win by default — the worst outcome.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A personal guarantee on a failed business is serious but not permanent — it’s dischargeable debt. Don’t sign anything new, don’t drain your retirement, and don’t miss a lawsuit deadline. Take the bankruptcy quiz and talk to an attorney this week. The longer you wait, the more options you lose.
The Bottom Line
You are not a failure because a business didn’t make it — you’re one of the millions of people brave enough to try. The law built protections for exactly this moment: the automatic stay, the bankruptcy discharge, your protected retirement. The people who come through this best are the ones who act before a default judgment lands, not after. If someone you know is drowning under a personal guarantee from a business that closed, send them this page — it could be the difference between a fresh start and years of garnishment. Start with the Find Your Path quiz and the debt relief options page.
If your personal account has also been frozen because you signed a personal guarantee, see my crisis guide on what to do right now when an MCA company freezes your bank account.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



