

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 9, 2026
Quick Answer: Debt created by identity theft is not your debt — and federal law gives you real machinery to prove it. File a free identity theft report at IdentityTheft.gov, and under FCRA Section 605B the credit bureaus must block the fraudulent accounts from your report within 4 business days. Don’t pay a dollar of it to make the calls stop — paying can look like you’re accepting the debt as yours.
What Just Happened — and Why the Collectors Found You First
Someone used your name, Social Security number, or other personal information to open credit cards, loans, or accounts — and then didn’t pay them. The accounts went to collections, and the collectors traced the name on the account: yours. Often the first you hear of any of it is a collection call, a credit denial, or a stack of statements you never knew existed.
Here’s the hard part nobody warns you about: a large share of identity theft isn’t committed by strangers. It’s a spouse, an ex, a parent, an adult child — someone who had easy access to your Social Security number and mail. If that’s your situation, you’re dealing with betrayal and a legal mess at the same time, and the path through is different in ways this guide takes seriously.
The Mistake You’re About to Make: Paying the fraudulent debt — or even a “small settlement” of it — to make the calls stop. Paying a debt created in your name can be read as accepting responsibility for it, restarts collection clocks, and tells the collector the account is collectible. The second mistake is the quiet one: protecting the family member who did it by doing nothing. If you don’t dispute the accounts, the defaults, judgments, and ruined credit land on YOU — permanently and legally. You can act without pressing criminal charges, but you cannot safely do nothing.
Your Options Right Now
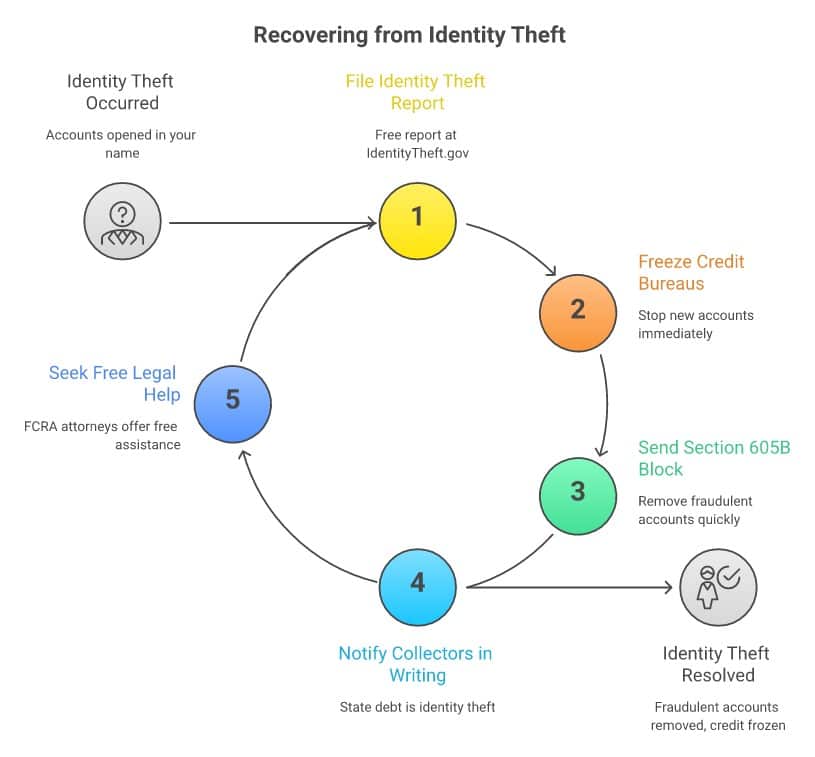
What to Do in the Next 48 Hours
- File your identity theft report at IdentityTheft.gov — it’s free and it’s the master key. The FTC’s report counts as an official identity theft report under federal law and generates a personal recovery plan plus pre-filled dispute letters. Most companies and all three credit bureaus accept it; you do not need a police report to get started. Your report is entered into Consumer Sentinel, a federal law-enforcement database — which is why it qualifies as a law-enforcement report under the FCRA.
- Freeze your credit at all three bureaus — today, before anything else gets opened. Freezes are free by federal law at Equifax, Experian, and TransUnion and stop new accounts cold. Then pull your full reports free at AnnualCreditReport.com and list every account you don’t recognize.
- Send the bureaus a block request under FCRA Section 605B. With your identity theft report, proof of identity, and a list of the fraudulent accounts, each bureau must block those accounts from your credit report within 4 business days — far stronger and faster than an ordinary dispute.
- Tell every collector, in writing: “This debt is the result of identity theft.” Under 15 U.S.C. § 1681m(g), a collector notified of identity theft must alert the creditor that the debt may be fraudulent. Separately, under 15 U.S.C. § 1681g(e), you can demand the account records — applications, signatures, transaction history — directly from the creditor or business that opened the account, and they must provide them within 30 days of your written request. Model language that works: “This account is the result of identity theft. Enclosed is my FTC Identity Theft Report. Cease collection of this debt and provide me the underlying account records under 15 U.S.C. § 1681g(e).”
- Get help that costs you nothing. FCRA violations pay your attorney’s fees — find a consumer attorney through NACA if bureaus or collectors don’t comply. Or talk to Damon Day for free about your whole picture.
How to Actually Clear It — Your 4 Paths
- The 605B block — your strongest tool. An ordinary credit dispute gives the bureau 30 days to “investigate” — and they often side with the creditor. A Section 605B block with an identity theft report flips the burden: the bureau must block the information within 4 business days, notify the furnisher, and the creditor is restricted from selling or re-aging the blocked debt. This is the difference between asking and requiring.
- The extended fraud alert — 7 years of verification. With your identity theft report, you can place an extended fraud alert: businesses must verify your identity before opening anything for 7 years, and you only have to contact one bureau — it must tell the other two.
- If they sue you anyway — respond, always. Collectors sometimes sue on fraudulent debt because most people don’t show up. Identity theft is a defense, but only if you raise it. My guides on being served with a debt lawsuit and what to do after a default judgment walk you through it.
- What WON’T work: paying it, ignoring it, or generic “not mine” disputes. Paying validates the debt. Ignoring it lets defaults and judgments pile onto your name. And a vague online dispute without the identity theft report invokes none of the special protections above — it’s the weakest move available dressed up as action.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
What You Need to Know About Your Federal Protections
For accounts opened entirely without your knowledge, you owe nothing — you never signed the contract, and the FCRA block removes the debt from your record. (For a card you actually hold that someone else used, liability is capped at $50 under the Truth in Lending Act — and card networks usually waive even that.) Each tool below does a different job; most people need the first three:
| Tool | What It Does | What You Need |
|---|---|---|
| Credit freeze | Stops NEW accounts from being opened; free; stays until you lift it | Nothing — set up online at each bureau in minutes |
| 605B block | Removes existing fraudulent accounts from your report within 4 business days | Identity theft report + proof of identity + list of fraudulent accounts |
| Extended fraud alert | 7 years of mandatory identity verification before credit is issued; one bureau notifies the other two | Identity theft report |
| Initial fraud alert | 1 year of verification; renewable | Nothing — just ask one bureau |
| Ordinary dispute | 30-day investigation the bureau controls — the weak option for identity theft | Nothing, and it shows |
If the person who did this is family — a spouse, an ex, a parent, an adult child — you have more room than you think. The FTC identity theft report does not require you to name the person or press charges, and it is enough for the credit bureaus. Be aware that some individual creditors may ask for a police report before they’ll clear an account, and a police report strengthens everything — but filing one is a choice you can make deliberately, not a toll you must pay at the door. What you cannot do is absorb the debt to keep the peace: the defaults stay on YOUR record for seven years, and if a creditor sues and wins, the judgment is against YOU.
If a bureau or collector ignores your identity theft report, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov — and remember that FCRA cases often cost you nothing because the law makes the violator pay your attorney’s fees through NACA-member attorneys.
Steve’s Take
I filed bankruptcy in 1990, so I know what it feels like when your finances collapse — but at least mine was my own doing. In 30 years I’ve sat with a lot of people who discovered the boxes of statements, the cards they never applied for, the signature that wasn’t theirs — and the thief was someone they loved. The shame runs in every direction and none of it belongs to you. Here’s the math that matters: the law is overwhelmingly on your side, the tools are free, and every month you wait adds defaults to your name that take real work to unwind. Protect your record first. Decide about the relationship second.
Frequently Asked Questions
Someone opened accounts in my name — am I responsible for that debt?
No. Debt created through identity theft is not legally yours — for accounts opened without your knowledge you owe nothing, because you never entered the contract. (If someone used a card you actually hold, liability is capped at $50 under 15 U.S.C. § 1643, and in practice it’s usually $0.) But you must act: file the identity theft report and dispute the accounts, or the defaults will sit on your credit as if the debt were yours.
Collectors are calling about accounts I never opened — what do I tell them?
Tell them in writing that the debt is the result of identity theft and include a copy of your FTC identity theft report. Under 15 U.S.C. § 1681m(g) they must notify the creditor the debt may be fraudulent. Then demand the underlying account records from the creditor itself under 15 U.S.C. § 1681g(e) — it must provide them within 30 days of your written request.
Do I have to file a police report?
Usually not to get started. The free FTC report at IdentityTheft.gov counts as an identity theft report for credit bureau blocks and extended fraud alerts. Some individual creditors ask for a police report before clearing an account, and having one strengthens your case — but the bureaus cannot reject a valid 605B request just because you don’t have one.
The person who did this is my spouse or family member — do I have to turn them in?
No. The FTC report doesn’t require you to press charges, and it’s enough for the credit bureaus. But you can’t simply absorb the debt to protect them — the ruined credit and any judgments land on you. File the report, dispute the accounts, and decide separately — ideally with a lawyer’s advice — how to handle the personal side.
How do I get the fraudulent accounts off my credit report?
Use a block request under FCRA Section 605B, not an ordinary dispute. Send each bureau your identity theft report, proof of identity, and the list of fraudulent accounts — they must block them within 4 business days.
Should I freeze my credit even after the damage is done?
Yes — immediately. Whoever opened these accounts has your information and can open more. A freeze is free at all three bureaus and stops new accounts while you clean up the existing ones. You can lift it temporarily anytime you apply for credit yourself.
Can a collector sue me over a debt someone else created in my name?
They can file suit — and some do, betting you won’t respond. Identity theft is a strong defense, but only if you show up and raise it. Never ignore a summons: an unanswered lawsuit becomes a default judgment against you even on a fraudulent debt. See my guide on what to do when you’re served.
Should I file bankruptcy to get rid of identity theft debt?
Almost never — bankruptcy is for debt you actually owe. Fraudulent accounts should be removed through the FCRA tools above at no cost to you. If you also carry real debt you can’t manage, that’s a separate conversation worth having with a NACBA bankruptcy attorney — but don’t file over debt that was never yours.
One more thing — everything here comes from 30 years of helping people through moments exactly like this one. But my advice is input for your decision, not the decision itself. Only you know your full situation — especially when family is involved. Talk to an attorney, look at your options, and make the choices that protect your future.
If legitimate collectors are also calling you about debts you actually owe, my guide to debt collectors calling explains your rights to demand validation, limit the number of calls, and stop contact entirely under the FDCPA.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACA can connect you with a consumer attorney experienced in FCRA and identity theft cases, NACBA can help you find a bankruptcy attorney if you also have debt of your own, or talk to Damon Day for free about your situation.
Key Takeaway: Identity theft debt is not your debt — but it becomes your problem if you don’t act. File the free report at IdentityTheft.gov, freeze your credit, and use the 605B block to force the fraudulent accounts off your report in 4 business days. The tools are free, the law is on your side, and paying even a dollar to “make it stop” is the one move that can hurt you.
The Bottom Line
You didn’t do anything wrong — someone did something wrong TO you, and if it was someone you trusted, that wound is real and it isn’t your shame to carry. Congress built specific, fast, free machinery for exactly this moment because it happens to millions of people a year. The ones who come through fastest aren’t the ones who agonize — they’re the ones who file the report, send the block letters, and let the law do the heavy lifting. If you know someone untangling accounts they never opened, send them this page — the difference between a 605B block and an ordinary dispute alone can save them months. For the longer story of money betrayal inside relationships, see my piece on financial infidelity and sexually transmitted debt.
If your data was exposed in a breach like the Flagstar Bank’s $31.5 Million Data Breach Settlement.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



