

Quick Answer: California consumers can report deceptive debt settlement, debt relief, or credit repair practices directly to the California Department of Financial Protection and Innovation (DFPI) at dfpi.ca.gov/submit-a-complaint. The DFPI now requires every debt settlement company serving Californians to register with the state, and its Enforcement Division actively investigates deceptive marketing — including bait-and-switch mailers, social media ads, and telemarketing pitches aimed at veterans and seniors. Your complaint is often the evidence that starts an investigation.
Part of the Debt Scam Alert Hub: This post is one piece of my complete Debt Relief Scams guide — the red flags to know, how to research any company, and what the FTC and CFPB data show about the most common fraud patterns.
Expert Context: I ran a credit counseling organization and watched debt settlement marketing corrupt good intentions from inside the industry. I’ve also spent decades collecting and dissecting deceptive debt relief mailers — my longtime I Buy Junk Mail series exists because the envelopes people throw away are often the best evidence of who is targeting them. So when a state regulator says “send us what you’re seeing,” I know exactly how valuable that ask is.
A senior attorney in the DFPI’s Enforcement Division recently reached out to me, and the message deserves a much bigger audience than my inbox: California is actively hunting deceptive debt settlement and credit repair operations, and the fastest way to put a bad actor on the state’s radar is for you to tell them what happened to you.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 15): A number you don’t look at is not an asset
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Here’s the problem the DFPI is up against, and it’s one I’ve seen play out for thirty years. Regulators can only act on what they know. If a company is blanketing California with fake “loan approval” mailers and nobody reports it, that company operates in the dark — collecting fees, stringing people along, and moving on to the next mailing list. The attorney I heard from put it simply: if the state doesn’t know which companies are harming consumers, or how they’re doing it, it can’t take action. The public is the early-warning system.
Key Terms Defined
DFPI: The California Department of Financial Protection and Innovation — the state regulator for financial products and services. It was given expanded authority under the California Consumer Financial Protection Law (CCFPL), passed in 2020. Think of it as California’s own consumer financial watchdog.
Bait-and-switch mailer: An official-looking letter that dangles a low-interest consolidation loan or pre-approved offer to get you on the phone — where you’re told you don’t qualify for the loan, but you do “qualify” for a debt settlement program. The loan was never real. The settlement enrollment was the goal all along.
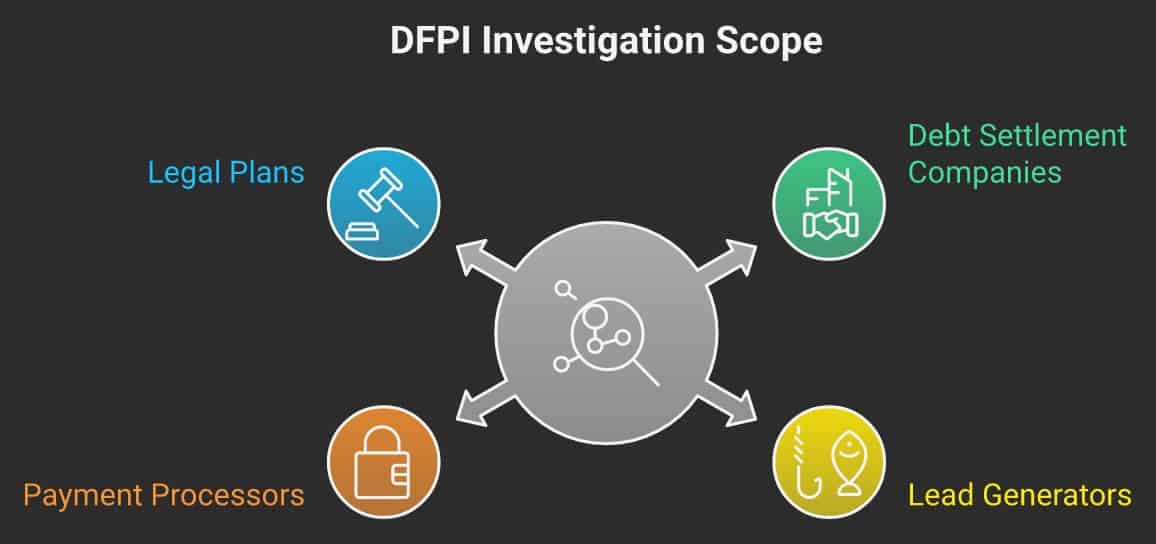
Debt settlement ecosystem: The full chain behind a settlement pitch — the marketing companies and lead generators who find you, the settlement company that enrolls you, the payment processor holding your money, and the “legal plans” sometimes bolted on. The DFPI is interested in all of it, not just the company whose name is on your contract.
The California Regulator Most Consumers Have Never Heard Of
Most people in debt trouble know about the CFPB, the FTC, or their state attorney general. Almost nobody knows California has its own dedicated financial-products regulator. That’s not an accident of your memory — the DFPI in its current form is young. The CCFPL took effect in 2021 and gave the state authority over corners of the financial marketplace that were previously unregulated in California — including debt settlement and debt relief services.
And here’s the part that genuinely changed the game: as of February 15, 2025, debt settlement companies serving California residents must register with the DFPI. Registration means the state knows who these companies are, can examine them, and can pull the registration of an operator that crosses the line. For an industry that spent decades operating with almost no state-level oversight in California, that is a fundamental shift.
In my experience, this matters more than any single enforcement action. A federal complaint to the CFPB goes into a national pile. A complaint to the DFPI about a company that is registered with the DFPI lands on the desk of the regulator holding that company’s permission slip to operate.
What California Wants to Hear About
Based on my conversation with the DFPI’s Enforcement Division, the state’s interest is broad. They are looking at potentially unlawful, unfair, deceptive, or abusive practices by any company in the debt settlement ecosystem — and they specifically want to hear from consumers who have encountered:
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
- Bait-and-switch mailers — fake loan offers that turn into debt settlement pitches on the phone. I’ve documented this tactic for years, including a confession from a former bait-and-switch debt relief salesperson who explained exactly how the script works.
- Deceptive social media ads — “government program” claims, fake deadlines, miracle debt erasure promises.
- Telemarketing calls — especially ones that misrepresent who is calling or what is being offered.
- Marketing aimed at veterans and seniors — the DFPI flagged this twice. If a pitch targeted you because of your age or military service, the state especially wants to know.
- Problems anywhere in the chain — lead generators, payment processors, and legal plans attached to settlement programs, not just the settlement company itself.
One detail worth underlining, because it’s the part most people don’t realize matters: the DFPI wants to identify both the company that sent the mailer and the debt settlement company that ultimately receives the lead. Those are usually two different companies, and connecting them is exactly what helps the state open an investigation. The envelope you almost threw away is evidence.
How to File a DFPI Complaint (and What to Include)
The complaint portal is at dfpi.ca.gov/submit-a-complaint. The online form takes about five minutes. You don’t need a lawyer, you don’t need to have lost money, and filing costs nothing. To make your complaint as useful as possible, include:
- The name of every company involved — the one on the mailer, the one you spoke to on the phone, and the one on any contract or bank draft
- Photos or scans of mailers, including the envelope and any return address or processing center listed
- Screenshots of social media ads or text messages
- Dates of calls and the phone numbers that called you
- What you were promised versus what was actually offered or delivered
Send it to me too. If you’ve received a suspicious debt relief mailer — from anywhere, not just California — I want to see it. My Debt Relief Scam Reporter page explains how to spot the tricks and share what you’ve received. I’ve been collecting this junk mail for years, and I pass patterns along to the people who can act on them. And before you sign anything a debt relief company puts in front of you, run it through my free Contract Decoder — it reads the fine print so you don’t get surprised by it later.
The Claim: “Filing a complaint is a waste of time. Nothing ever happens.”
The Reality: The DFPI has already used its authority to issue desist and refrain orders against debt relief operators — including an order against Elite Credit Group, Inc. that demanded rescission of its debt relief agreements with California residents. Complaints are how regulators find these companies in the first place. One complaint may not topple a company, but it adds to a pattern — and patterns are what trigger investigations.
Free Tool — Scam-O-Meter: Considering a debt relief company? Run your situation through the free Scam-O-Meter — it checks for official FTC, FBI, CFPB, and SEC warning signs before you hand over any money. Check for Red Flags →
If You Run a Debt Relief Company, Consider This Your Notice
I know plenty of people in the debt relief industry read this site, so let me speak to you directly for a moment, because frankly this is good news for the companies trying to do it right.
California is not casually monitoring this space — it is actively soliciting consumer evidence, and its interest runs through the entire ecosystem: the settlement companies, the lead generators feeding them, the payment processors holding client funds, and the legal plans wrapped around enrollments. If your growth strategy depends on mailers that promise loans you never intend to make, the state is specifically asking consumers to send those mailers in — envelope, return address, and all — so it can connect the marketer to the company buying the leads.
And the registration requirement changed the stakes. An unregistered operator isn’t just risking a fine — the DFPI has shown it will order operators to unwind their California agreements entirely. If you’re running a clean operation: register, audit your lead sources, and ask hard questions about what your marketing affiliates are mailing under names you’ve never approved. Every bottom-feeder the DFPI removes makes the honest companies’ phones easier to answer. The companies that should be nervous right now know exactly who they are.
What If You’re Not in California?
The DFPI’s jurisdiction covers California consumers. If you’re elsewhere, your complaint still matters — it just goes to different desks: the CFPB, the FTC, and your own state attorney general. And many deceptive operations market nationally, so a California complaint about a company’s mailer often helps consumers in all fifty states. If you’re not sure where you stand with your debt overall, my free Find Your Path quiz will help you sort out which options actually fit your situation — including the ones no salesperson earns a commission recommending.
Key Takeaways
- The DFPI is California’s financial-products regulator, and most consumers have never heard of it — file complaints at dfpi.ca.gov/submit-a-complaint.
- Debt settlement companies serving Californians have been required to register with the DFPI since February 15, 2025 — giving the state real oversight power.
- The state wants evidence of deceptive marketing across the whole ecosystem: mailers, social ads, telemarketing, lead generators, payment processors, and legal plans.
- Deceptive marketing aimed at veterans and seniors is a specific enforcement priority.
- Keep the envelope — identifying who sent a mailer and which settlement company received the lead is exactly what helps the state open an investigation.
The Bottom Line
If you got burned by a debt settlement pitch — or even just got a suspicious mailer — it’s easy to feel like you were the only one fooled, and that telling anyone would be pointless or embarrassing. You weren’t, and it isn’t. These companies run the same script on thousands of people at a time, and the only reason the script keeps working is that almost nobody reports it. California has built a regulator with real teeth and is openly asking for your help pointing it at the right targets. Five minutes at dfpi.ca.gov/submit-a-complaint turns your bad experience into someone else’s protection. The mailer they sent to trick you might be the exact piece of evidence that stops them.
If someone you know in California has been wrestling with a debt settlement company — or keeps getting those too-good-to-be-true loan offers in the mail — send them this post. This is one of those rare times a regulator is genuinely asking for the public’s help, and the more people who know the DFPI exists, the fewer people the bad actors can hide from. As always, my advice is input, not instruction — you know your situation best, and only you decide what’s right for it.
Frequently Asked Questions
What is the California DFPI?
The Department of Financial Protection and Innovation is California’s state regulator for financial products and services. It oversees debt collectors, debt settlement companies, student loan servicers, payday lenders, and more under the California Consumer Financial Protection Law passed in 2020. It investigates complaints and can issue enforcement orders, including ordering companies to stop operating and unwind their agreements with California residents.
How do I report a debt settlement company in California?
File a complaint online at dfpi.ca.gov/submit-a-complaint — it takes about five minutes and costs nothing. Include every company name involved, copies or photos of any mailers including the envelope, screenshots of ads or texts, dates of calls, and what you were promised versus what actually happened.
Can I file a DFPI complaint if I don’t live in California?
The DFPI focuses on California consumers, so if you live elsewhere, file with the CFPB, the FTC, and your own state attorney general instead. Many deceptive debt relief operations market nationally, so complaints filed in any state help build the pattern regulators need to act.
How can I check if a debt settlement company is registered in California?
Debt settlement providers serving California residents must register with the DFPI through the Nationwide Multistate Licensing System. You can verify a company through NMLS Consumer Access at nmlsconsumeraccess.org or through the DFPI’s search tools. A company pitching debt settlement to Californians without registration is a serious red flag worth reporting on its own.
Does filing a DFPI complaint cost anything or create risk for me?
No. Filing is free, you don’t need a lawyer, and you don’t need to have lost money — a deceptive mailer or ad alone is worth reporting. The DFPI reviews complaints to determine whether enforcement action is warranted; it is not a court and filing does not obligate you to anything.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



