

Quick Answer: On July 1, 2026 — three weeks from now — the biggest restructuring of federal student loan repayment in a generation takes effect. If you’re one of the 7.5 million borrowers still sitting on the now-vacated SAVE plan, doing nothing means getting auto-enrolled into a plan that could cost you hundreds more per month — and if you work in public service, it quietly stops your loan forgiveness clock entirely. Log into studentaid.gov this week, not after the deadline.
Related: Federal judges just struck down the new pslf employer restriction — here is what it means for public service borrowers.
I’ve watched every major student loan overhaul since the 1990s, and the same thing happens every single time: the people who act early get the best deal, and the people who wait get whatever’s left over. This one is no different — except the stakes are higher, because one of the default outcomes this time silently kills Public Service Loan Forgiveness credit.
Here’s what you need to know, why it matters, and exactly what to do in the next three weeks.
What You Need to Know
The changes coming July 1 flow from the budget law signed last July and a federal court ruling this March that struck down the SAVE plan for good. NPR broke down the details this week, and the bottom line is this:
- If you’re on SAVE: Starting July 1, your servicer will send you a notice giving you 90 days to pick a new plan. Most SAVE borrowers will see payments resume by September or October. If you do nothing, you get auto-enrolled into a standard repayment plan — which for many people who had $0 SAVE payments means going from nothing to several hundred dollars a month overnight.
- Two new plans launch July 1: The Repayment Assistance Plan (RAP) charges 1–10% of your total adjusted gross income depending on your bracket, waives unpaid interest monthly, and forgives the balance after 30 years. The new Tiered Standard Plan sets fixed payments over 10–25 years based on how much you owe.
- Two old plans close: PAYE and ICR stop accepting new enrollees July 1, 2026, and shut down completely in July 2028. If you’re on one now, you can stay for two more years — but you can’t get back in if you leave.
- IBR survives. Income-Based Repayment remains permanently available for loans taken out before July 1, 2026 — and the old income-eligibility restriction is gone, so anyone with qualifying loans can enroll regardless of income.
- Grad PLUS loans end for new borrowers July 1, with new annual and lifetime borrowing caps for graduate and professional students.
Why You Need to Know It
Here’s the part the headlines aren’t telling you, and it’s the part I’d be shouting from the rooftop if I worked at the Department of Education: the auto-enrollment default is a forgiveness trap for public service workers.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
If you work for a government agency, a school, a hospital system, or a nonprofit, and you’re counting on Public Service Loan Forgiveness, listen carefully. The Tiered Standard Plan — one of the plans you can get auto-enrolled into if you let the 90-day window expire — does not qualify for PSLF. Every month you sit in that plan is a month that doesn’t count toward your 120 qualifying payments. You wouldn’t just face a higher payment. You’d be paying more and earning zero forgiveness credit, and nobody would send you a warning letter about it.
I’ve seen this movie before. When loan programs restructure, the fine print always lands hardest on the people too busy living their lives to read it — nurses, teachers, social workers. The exact people PSLF was built for.
One more thing the headlines bury: if you’re a Parent PLUS borrower, the door to income-driven repayment closes on June 30 — twenty days from now. To keep IDR access, your Parent PLUS loans must be consolidated into a Direct Consolidation Loan with the consolidation disbursed by June 30. The Department recommended applying back in April because processing takes weeks. If you haven’t applied, do it today — literally today — and understand it may already be too tight. After June 30, unconsolidated Parent PLUS loans lose income-driven repayment access permanently.
Things to Consider
RAP or IBR? For most existing borrowers, run the numbers on both. RAP forgives after 30 years; IBR forgives after 20 years (25 if your loans predate mid-2014). That decade matters enormously. RAP’s payments are based on your total income with no deduction for basic living expenses, while IBR protects a chunk of your income first — so lower earners often pay less on IBR too. RAP’s advantages: unpaid interest is waived monthly so your balance never balloons, and there’s a $50/month minimum principal credit. The Loan Simulator at studentaid.gov can compare plans, though it didn’t yet include RAP estimates as I write this.
If you’re on PAYE or ICR, you have breathing room — but use it. Nothing forces you out until July 2028. But mark it on your calendar now, because when those plans sunset, you’ll be transitioned automatically, and automatic transitions are exactly how people end up in plans they didn’t choose.
Think hard before consolidating anything after July 1. Loans consolidated after that date lose access to IBR entirely — you’d be locked into RAP or standard repayment only. Consolidation also generally resets your IDR forgiveness clock to zero. There are situations where consolidation makes sense, but after July 1 it becomes a one-way door. Don’t walk through it casually.
And if your loans are already in default — you’re not alone; 2.6 million borrowers are there with you — start with my guide on what to do when your student loans are in default. Getting out of default comes first; plan selection comes second.
What to Think About Doing
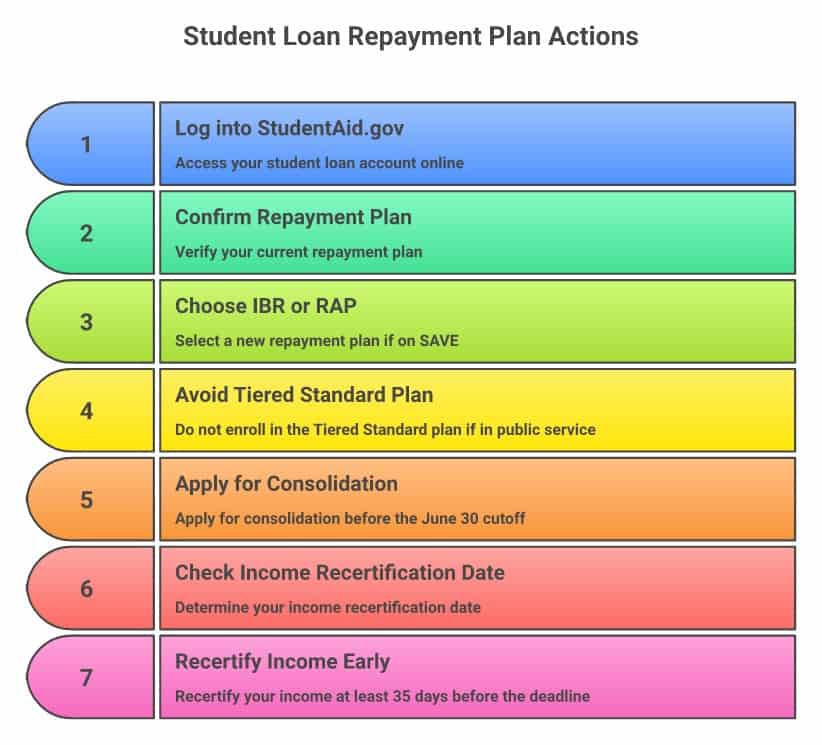
- Log into studentaid.gov this week. Confirm which repayment plan you’re actually on (many people guess wrong), verify your servicer’s contact info, and download your payment history while you’re there. Five minutes of looking beats three months of assuming.
- On SAVE? Don’t wait for the notice. You can contact your servicer right now and switch to IBR or RAP ahead of the rush. Seven and a half million people are about to flood the same phone lines within the same 90-day stretch. Early movers get processed; late movers get hold music.
- In public service? Protect your PSLF clock. Enroll in RAP or IBR — never let yourself land in the Tiered Standard Plan by default. While you’re at it, submit a PSLF employment certification form now so your qualifying payment count is documented before the transition.
- Check your income recertification date in the Loan Breakdown section of your studentaid.gov account, and recertify at least 35 days before the deadline. Missing recertification under the new rules can mean payment recalculation at the worst possible moment.
- Parent PLUS borrower who hasn’t consolidated? Apply today. The June 30 disbursement cutoff is real and processing takes weeks. It may already be too late — but applying today costs you nothing, and missing the window costs you income-driven repayment forever.
If your situation is genuinely tangled — mixed federal and private loans, a forgiveness count in dispute, default plus a Parent PLUS problem — don’t white-knuckle it alone. Talk to Damon Day for a free, no-sales-pitch consultation. And keep your scam radar on: every deadline like this brings out the “student loan relief” companies charging hundreds of dollars for paperwork you can do free at studentaid.gov. The FTC shut down an $8.8 million operation doing exactly that.
If someone you care about has student loans — your kid, your coworker, the nurse in your family — send them this post today. Three weeks is enough time to act, but only if they know the clock is running.
This is what I’m seeing after 30 years of helping people navigate debt, and it’s what I’d tell my own family at the kitchen table. But your situation is yours, and only you can weigh it. Take my advice as input, not instruction — nobody gets to tell you what to do with your money. Not me, not anyone.
Update: The autopay interest rate discount has increased from 0.25% to 1% as of July 1, 2026 — one more reason to get your servicer account set up this week before the deadline.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
While you’re sorting out the July 1 changes, don’t miss the truth about what happened to your SAVE balance during the “pause” — interest didn’t stop the way most people think.
Related: One of the July 1 changes is a brand-new repayment plan — and its lower monthly payment can quietly cost you more over 30 years. Here’s what to check before you switch to the new Repayment Assistance Plan.
Update — the deadline is now live: New York’s attorney general has issued a formal warning and servicer notices are going out. If you’re on SAVE, see why you have 90 days to choose a new plan before you’re auto-enrolled in a costlier one.



