

Quick Answer: Yes — a creditor or debt buyer can sue you even while you’re enrolled in a debt settlement program, and it happens more than most people enrolling ever realize. Signing up for debt settlement does not create any legal shield, your settlement company will not defend you in court, and if you ignore the lawsuit you can get a default judgment that leads to wage garnishment or a frozen bank account. If you’ve been served, the single most important thing is to file a written answer with the court before the deadline — usually 20 to 30 days — no matter what your settlement company tells you.
Expert Context: I ran a credit counseling organization and have watched the debt settlement industry from the inside for thirty years. This particular trap is one I’ve seen close on good people over and over: they enroll believing they’ve bought protection and breathing room, stop paying their creditors on the company’s advice, and then a lawsuit lands — and the company that took their monthly payments is nowhere to be found in the courtroom. Nobody warned them this could happen. So I’m warning you.
Where this topic came from: A recent conversation in my free Ask Steve chat raised exactly this kind of situation. I’m not sharing any personal details here — I never do — but when a real question shows me a gap worth covering, I write the answer for everyone. If you’re dealing with something like this yourself, ask me about it in the chat. It’s free, it’s private, and I’m not selling anything.
Here’s the hard truth the debt settlement sales pitch leaves out: enrolling in a program does nothing to stop a creditor from taking you to court — and your creditors know it.
Why a creditor can sue you mid-program
Debt settlement is a voluntary arrangement between you and a company you hired. Your creditors never agreed to it. They aren’t part of it. Nothing about your enrollment legally binds them to wait, pause collection, or hold off on a lawsuit. Until a specific debt is actually settled and that settlement is signed, a creditor is free to do whatever the law allows to collect — including suing you.
And there’s a reason lawsuits often land while you’re in a program. Most debt settlement companies tell you to stop paying your creditors and instead funnel money into a dedicated savings account they control, so a lump sum builds up to negotiate with. From the creditor’s side, you’ve gone from “slow payer” to “stopped paying entirely.” That’s frequently the trigger. The longer the account sits unpaid, the closer it gets to charge-off and sale to a debt buyer — and debt buyers sue aggressively to lock in their right to collect before the statute of limitations runs out.
The part that catches people off guard: the company won’t defend you
This is where I see the deepest sense of betrayal. People assume that because they’re paying a debt settlement company every month, that company is handling things — including a lawsuit. It almost never is.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
The Claim: “Once you enroll, we handle your creditors and you don’t have to worry about them anymore.”
The Reality: A debt settlement company is not a law firm and does not represent you in court. It does not monitor court filings, it will not file an answer for you, and it generally takes no action when you’re sued. If a lawsuit arrives, defending it is on you — and the clock is already running.
If a creditor or debt buyer sues you and you do nothing, they win automatically. It’s called a default judgment, and once a creditor has one, they can pursue wage garnishment, a bank levy, or a lien — depending on your state. The worst outcome here isn’t the lawsuit itself. It’s ignoring it.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What to do if you’ve been served while in a program
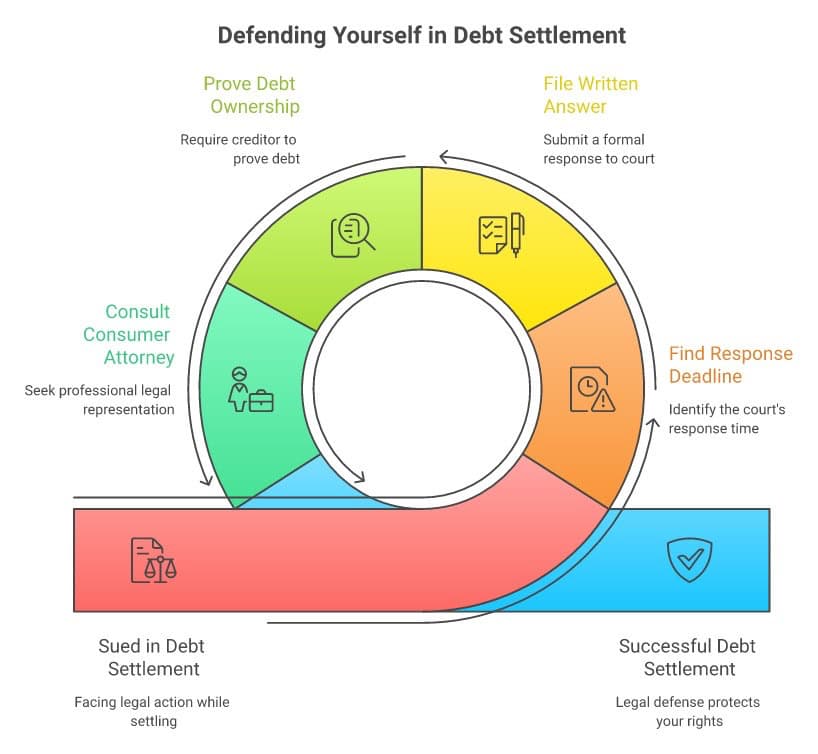
If a process server hands you papers — or you find out a case has been filed against you — here is the order I’d want my own family to follow:
- Find the deadline to respond. The summons states how many days you have to file an answer with the court, usually 20 to 30. This deadline is the most important date in the whole situation. Mark it.
- File a written answer before that deadline. Even a simple answer that denies the claims and asks the creditor to prove the debt stops a default judgment and forces the case to proceed properly. Filing an answer is the single act that protects you.
- Make the creditor prove they own the debt. Debt buyers often can’t produce the original signed agreement or a complete chain of ownership. Demanding proof can weaken or end a case — but only if you’ve answered.
- Don’t rely on the settlement company to handle it. Call them, by all means, but assume the court response is yours to make.
- Talk to a consumer attorney. Many offer free consultations, and some take cases for little or nothing because the law may make the creditor pay fees if they violated your rights.
Already behind and feeling trapped by the program itself? Run your real numbers through my free Find Your Path quiz to compare debt settlement against every other option, and check any company’s complaint history with the Scam-O-Meter. If you want a human to talk it through with, find a consumer attorney through the National Association of Consumer Advocates (NACA), or a bankruptcy attorney through NACBA if the math has gotten that far.
The bigger question this raises
Getting sued while in a settlement program isn’t just a legal emergency — it’s a signal worth listening to. If creditors are suing you, the program may not be working the way you were promised. Debt settlement resolves a far smaller share of enrolled debt than the marketing implies, and the fees, the credit damage, and the lawsuit exposure are real costs the brochure glosses over.
I’m not telling you to quit your program today. I’m telling you to use this moment to look honestly at whether it’s actually moving you forward — and to know that other paths exist, including ones that come with an automatic legal shield that settlement never offered you. The automatic stay in bankruptcy, for instance, legally stops lawsuits and garnishments the moment you file. That’s not a pitch — it’s just one of the options the people selling settlement have no reason to mention.
Key Takeaways
- Enrolling in debt settlement does NOT stop a creditor from suing you — it’s voluntary and your creditors never agreed to it.
- Settlement companies are not law firms and will not defend you in court.
- If you’re served, file a written answer before the deadline (usually 20–30 days) to avoid a default judgment.
- A default judgment can lead to wage garnishment, a bank levy, or a lien.
- Being sued mid-program is a signal to honestly re-evaluate whether settlement is working for you.
The Bottom Line
If you opened a lawsuit while you were paying a company to make your debt go away, I understand the gut-punch — you did the responsible thing and it still wasn’t enough, and now you feel alone in it. You’re not. This happens to thousands of people who were never told it could, and it doesn’t mean you failed. It means you were sold protection that didn’t exist. The good news is that the one move that matters most is completely within your reach: answer the lawsuit before the deadline. Do that, and you’ve turned an automatic loss into a real fight — and given yourself room to step back and choose a path that actually has your back.
Frequently Asked Questions
Can I be sued while enrolled in a debt settlement program?
Yes. Debt settlement is voluntary and your creditors are not bound by it. They can sue you at any point until a specific debt is settled in writing — and stopping payments, which most programs advise, often triggers the lawsuit.
Will my debt settlement company defend me if I’m sued?
Generally no. Debt settlement companies are not law firms, do not represent you in court, do not monitor court filings, and typically take no action if you’re sued. Responding to the lawsuit is your responsibility.
What happens if I ignore a lawsuit while in debt settlement?
If you don’t respond, the creditor wins automatically through a default judgment. That can lead to wage garnishment, a frozen bank account, or a lien, depending on your state. Always file an answer before the deadline.
How long do I have to respond to a debt lawsuit?
It varies by state, but typically 20 to 30 days from when you were served. The exact deadline is on your summons. Filing a written answer before that date is the most important step you can take.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
Should I quit debt settlement if I get sued?
Not necessarily on the spot, but a lawsuit is a strong signal to honestly re-evaluate. Compare your real numbers against every option — including ones like bankruptcy that legally stop lawsuits the moment you file. A free tool like the Find Your Path quiz can help you weigh the choices.
This is what I’d tell my own family after thirty years of watching this trap close on good people. Take it as one informed perspective, not a directive — only you know your full situation. Use it as input for your decision. Nobody gets to tell you what to do with your money. Not me, not anyone.
If your debt settlement company hasn’t resolved the debt, you’re now facing a real lawsuit instead of just a threat. See what to do when A Debt Collector Is Threatening to Sue Me.
If the settlement program itself fell apart and you’re trying to recover, here’s how to stop the bleeding and get your money back.
Facing a Similar Situation? You’re not alone — and you have more options than you think. Start with all your debt relief options to see what’s realistic, or take the 2-minute bankruptcy quiz if the debt feels unmanageable. Federal Reserve research shows filers recover faster than those who don’t file. If a company is involved, run them through the Scam-O-Meter first.



