

Quick Answer: If you’re already enrolled in a debt settlement program and wondering whether to abandon it and file bankruptcy instead, the honest answer is: it depends on the math, but for a lot of people the answer is yes — and the longer a program drags on without settling much, the stronger the case for switching. You can leave a debt settlement program at any time; it’s voluntary, not a contract that traps you. The hard part is the money you’ve already paid in fees, which you generally won’t get back. But that’s a sunk cost — it shouldn’t decide your future. What should decide it is which path actually gets you free.
Expert Context: I ran a credit counseling organization, I’ve watched the debt settlement industry sell its promises for thirty years, and I filed bankruptcy myself in 1990 after my real estate business collapsed. So I’m not comparing these options from a brochure — I’ve sat with people partway through a settlement program who were paying every month and getting nowhere, terrified that quitting meant they’d “wasted” all that money. I’ve also lived the thing the settlement industry never wants you to consider, and come out the other side with my life rebuilt.
Where this topic came from: A recent conversation in my free Ask Steve chat raised exactly this kind of decision. I’m not sharing any personal details here — I never do — but when a real question reveals a gap worth covering, I write the answer for everyone. If you’re weighing this for yourself, ask me about it in the chat. It’s free, it’s private, and I’m not selling you anything.
You are allowed to change your mind. Enrolling in a debt settlement program was a decision, not a life sentence — and if it isn’t working, staying in out of guilt over the money you’ve already spent is the one mistake that makes everything worse.
First, the question underneath the question
When someone asks me whether they should quit settlement for bankruptcy, what they’re usually really asking is: “Have I already thrown away too much to walk away?” The fees were steep, the monthly payments were real, and abandoning the program feels like admitting a loss.
Here’s the reframe I want you to hear. The money you’ve already paid into a settlement program is gone whether you stay or leave. Economists call it a sunk cost, and the entire trap of a sunk cost is that it tricks you into pouring more good money after bad just to justify what you already spent. The only question that matters now is: which path, starting today, gets you to a clean slate fastest and safest? Not which path makes the past hurt less.
What bankruptcy gives you that settlement structurally cannot
This is the part the settlement industry will never put in its sales pitch, because it’s the part that makes settlement look bad by comparison.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
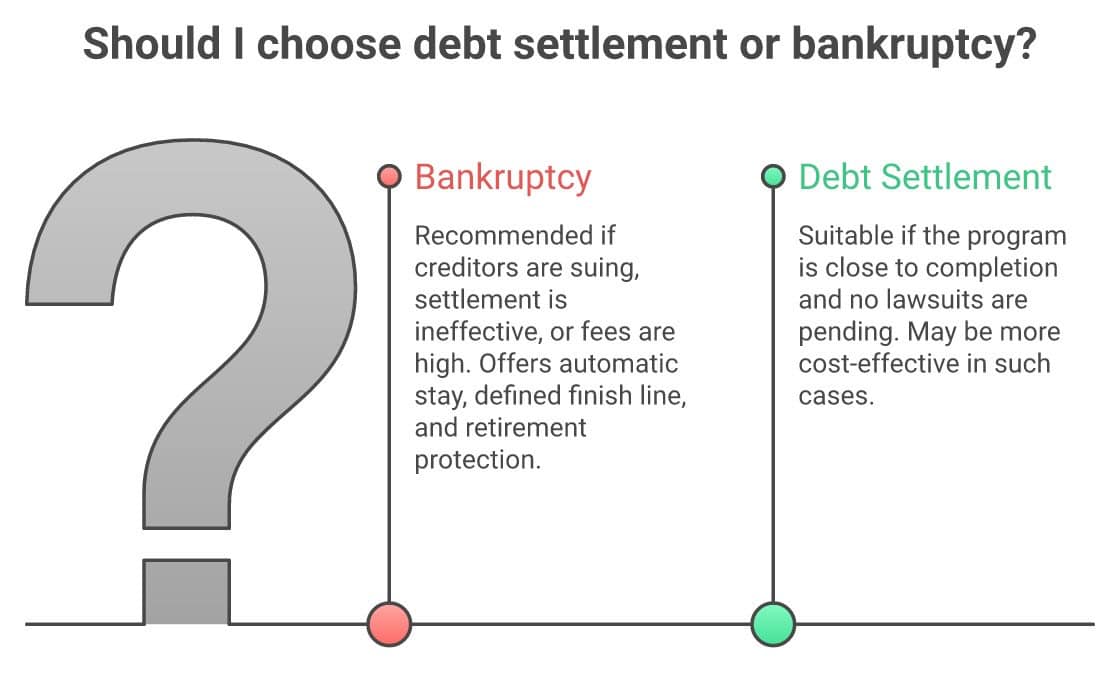
- The automatic stay. The moment you file bankruptcy, federal law instantly stops lawsuits, wage garnishments, bank levies, and collection calls. Settlement offers zero legal protection — creditors can sue you the entire time you’re enrolled.
- A defined finish line. A Chapter 7 case typically wraps up in a few months with eligible debts discharged. Settlement can grind on for years with no guarantee any given debt ever settles.
- A high success rate. Bankruptcy discharges eligible debt as a matter of law. Settlement resolves a much smaller share of enrolled debt than the marketing implies — and you pay fees whether it works or not.
- It protects your retirement. Your 401(k) and IRA are generally protected in bankruptcy. The hidden cost of dragging through years of settlement (or its cousin, a long credit-counseling plan) is the retirement savings you don’t make while every spare dollar goes to the program.
The Claim: “Bankruptcy is the worst thing you can do to your credit — settlement is the responsible choice.”
The Reality: Both damage your credit. But settlement damages it the whole long time you’re not paying creditors, with lawsuits and charge-offs piling on — and there’s research showing credit scores often rise in the period after a bankruptcy discharge, because the debt that was dragging the score down is finally gone. Federal Reserve research shows bankruptcy filers recover faster than people who keep struggling without filing.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
When staying in settlement might actually make sense
I give people all their options and let them decide — so let me be fair to settlement. Staying the course can make sense if you’re genuinely close to settling your remaining accounts, your creditors aren’t suing you, your debt is modest enough that the program is realistically finishing soon, or you have a specific reason bankruptcy doesn’t fit your situation (certain assets, certain debts, or you simply don’t qualify). If the program is working and the end is in sight, finishing it can be the right call. The trouble is that for many people, the end is never actually in sight — and that’s the signal to stop.
A few related situations I’ve written about that often come up alongside this decision: what to do if you’re sued by a creditor while still enrolled in a settlement program, how bankruptcy can erase certain tax debt, and why California is actively hunting deceptive debt settlement companies right now.
Free Tool — Scam-O-Meter: Considering a debt relief company? Run your situation through the free Scam-O-Meter — it checks for official FTC, FBI, CFPB, and SEC warning signs before you hand over any money. Check for Red Flags →
How to actually make the decision
Don’t decide this alone in your head at 2am. Do this instead:
- Pull your real numbers: total debt remaining, how much you’ve paid in fees so far, how many accounts have actually settled, and how many lawsuits or threats you’re facing.
- Run the comparison honestly with a tool built to weigh every option, not a sales funnel. My free Find Your Path quiz compares settlement, bankruptcy, and the rest based on your actual situation.
- Talk to a real bankruptcy attorney — most consumer bankruptcy attorneys offer a free consultation. Find one through NACBA. A 30-minute conversation will tell you more than weeks of worrying.
- If you decide to leave the program, stop your payments to the settlement company and redirect your energy to the new plan. You don’t owe them a long goodbye.
Worried the company you’re with isn’t even legitimate? Run it through my free Scam-O-Meter to see its complaint history, and if you were sold the program with promises that didn’t hold up, know that regulators like the FTC and state agencies are actively pursuing deceptive debt settlement operations.
Key Takeaways
- You can leave a debt settlement program anytime — it’s voluntary, not a binding sentence.
- Fees you’ve already paid are a sunk cost; they shouldn’t drive your decision.
- Bankruptcy offers legal protections settlement can’t: the automatic stay, a defined finish, and retirement protection.
- Staying in settlement makes sense only if it’s genuinely working and the end is in sight.
- Pull your real numbers and talk to a bankruptcy attorney before deciding — most consultations are free.
The Bottom Line
If you’re paying into a settlement program month after month and quietly wondering whether you’re just feeding a machine that isn’t getting you anywhere, trust that instinct enough to check. Leaving doesn’t mean you failed — it means you’re willing to stop honoring a sunk cost and start choosing what actually frees you. I filed bankruptcy in 1990 when I was sure my life was over, and it turned out to be the beginning of getting everything back. The debt is not your identity, the money you’ve already spent is not a reason to keep suffering, and there is a finish line — closer than the people who sold you the program ever wanted you to know.
Frequently Asked Questions
Can I quit a debt settlement program once I’ve enrolled?
Yes. Debt settlement is voluntary — you can stop at any time. You generally won’t recover the fees you’ve already paid, but you are not legally locked into continuing.
Will I lose the money I already paid if I leave debt settlement for bankruptcy?
You typically won’t get back the fees already paid to the settlement company. But that money is a sunk cost — it’s gone whether you stay or leave, so it shouldn’t determine your decision. Focus on which path gets you debt-free fastest from today forward.
Is bankruptcy better than debt settlement?
For many people with significant unsecured debt, yes. Bankruptcy provides the automatic stay (which stops lawsuits and garnishments instantly), a defined timeline, a high discharge rate, and retirement protection — none of which settlement guarantees. The right answer depends on your specific numbers.
Does switching from settlement to bankruptcy hurt my credit more?
Both damage credit. Settlement damages it throughout the long period you’re not paying creditors. Research shows credit scores often rise after a bankruptcy discharge because the debt dragging the score down is finally cleared.
How do I decide between continuing settlement and filing bankruptcy?
Pull your real numbers — debt remaining, fees paid, accounts actually settled, lawsuits faced. Compare your options with a neutral tool like the Find Your Path quiz, and get a free consultation with a bankruptcy attorney through NACBA before deciding.
This is what I’d tell my own family, having lived it myself. Take it as one informed perspective, not a directive — only you know your full situation. Use it as input for your decision. Nobody gets to tell you what to do with your money. Not me, not anyone.
If your program already failed and you’re weighing what comes next — especially with retirement close — see how to recover from a failed debt settlement program.
Facing a Similar Situation? You’re not alone — and you have more options than you think. Start with all your debt relief options to see what’s realistic, or take the 2-minute bankruptcy quiz if the debt feels unmanageable. Federal Reserve research shows filers recover faster than those who don’t file. If a company is involved, run them through the Scam-O-Meter first.



