

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 15, 2026
Quick Answer: Usually, no — not all of it. Throwing your entire emergency fund at debt feels like progress, but it trades a problem you can survive (debt) for one that can sink you (no cash when the car breaks or the hours get cut). The honest answer depends on your situation: how stable your income is, what the debt is costing you, and whether that debt is even worth paying in full. Keep a real cushion — I tell people to hold three months of expenses or more before paying extra toward debt. Use only the surplus above that. And before you empty the account, make sure you’re not paying down debt a fresh start could erase.
What This Decision Really Is
On paper, it looks simple. You’ve got money sitting in savings earning almost nothing, and debt costing you a fortune in interest. Move the money, kill the interest, win. If a calculator were the whole story, you’d have done it already.
But this isn’t a math problem — it’s a risk problem. Your emergency fund isn’t really “extra money.” It’s the thing standing between a bad week and a financial disaster. The day you drain it is the day a flat tire, a sick kid, or a cut shift goes straight onto a credit card — the same card you just paid off, now charging you interest again. People don’t fall apart because they had debt. They fall apart because they had debt and no cushion when life happened.
The Mistake You’re About to Make: Emptying your last few thousand dollars to pay down unsecured debt — credit cards, medical bills, personal loans — that a bankruptcy could legally erase. I’ve watched people scrape their savings to zero to pay collectors, then file bankruptcy six months later anyway and wipe out the rest. They could have kept that money. In some cases a last-minute payment to one creditor can even be reversed by the bankruptcy trustee — another reason to get advice before spending a dollar on debt you may not need to pay. Before you spend your safety net on debt, find out whether that debt is even worth paying in full.
How to Actually Decide — The Questions That Change the Answer
Work Through These Before You Move a Dollar
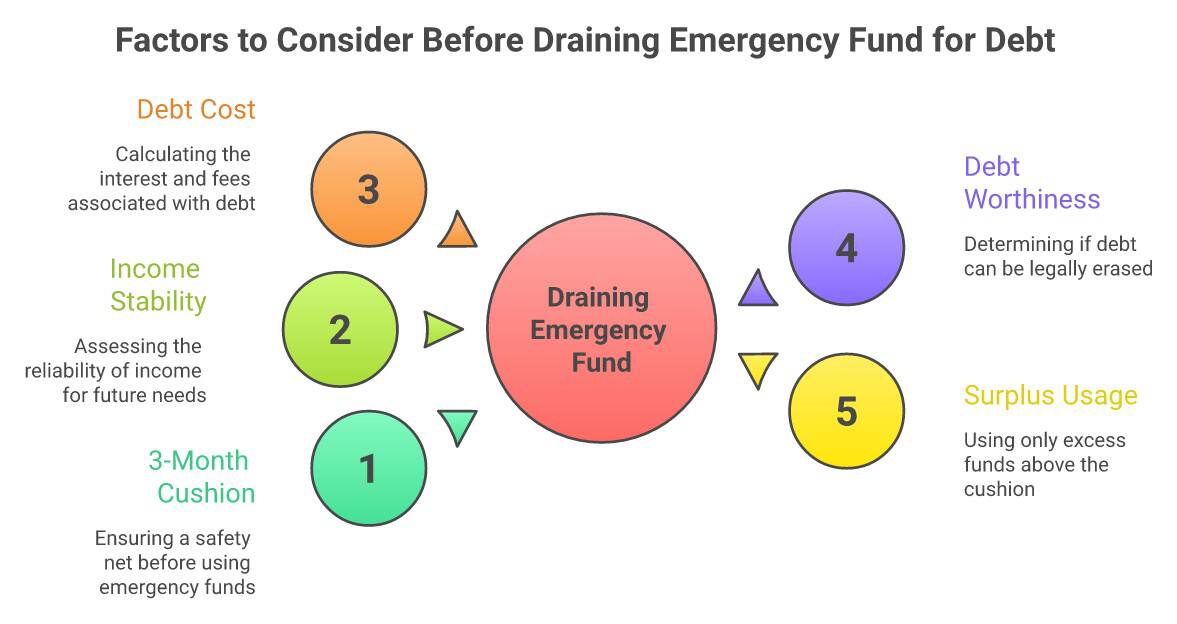
- Do you have a real cushion first? I tell people to hold three months of expenses or more before paying anything extra toward debt. If you’re not there yet, build the cushion first, even while making minimum payments — you cannot borrow your way out of a crisis if you’ve already maxed the cards you’d need. (Still deciding whether to build savings or pay debt down in the first place? That’s a different question — start here instead. This guide is for when you already have savings and are deciding whether to spend them.)
- How stable is your income? Steady paycheck, secure job, two earners in the house — you can afford to use more. Commission, gig work, seasonal hours, one income, or a shaky employer — keep more in reserve. The less predictable your money, the bigger your cushion needs to be.
- What is the debt actually costing you? The average credit card now charges about 21% APR — and 21.5% on balances that carry month to month (Federal Reserve, 2026). A 22% card is an emergency of its own; a 0% promo balance or a low-rate federal student loan is not. High-rate, high-balance debt is where spare cash does the most good.
- Is this debt even collectible — or worth paying in full? If you’re being sued, judgment-proof, or already thinking about bankruptcy, draining savings to pay these creditors can be money thrown away. Check whether you’re judgment proof first — it means creditors can’t currently collect from you, though that status can change if your income or assets do.
- Use a slice, not the whole thing. If you decide to pay, keep your three-month cushion intact and put only the surplus above it toward the highest-rate debt. A smaller balance with a full safety net beats a zero balance with zero dollars left.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
When It Makes Sense — and When It Doesn’t
- It can make sense when: your income is steady, you’d still keep a real buffer afterward, and the debt is high-rate (think 20%+) and one you intend to keep paying. Killing a 22% balance is a guaranteed return no investment matches.
- It usually doesn’t when: the fund is all you have, your income is unpredictable, or the debt is low-rate. Earning 21% by not paying interest means nothing if you have to re-borrow at 24% the next time the furnace dies.
- Stop and rethink entirely when: you’re considering draining savings to pay debt that bankruptcy could discharge, or to keep a debt settlement program alive. That’s spending your safety net to delay a fresh start — the worst of both. Bankruptcy protects your retirement accounts and gives you the clean slate that scraped-together payments never will.
- What won’t work: emptying the account to “feel caught up.” The relief lasts until the next surprise bill, and then you’re back in debt without the cushion. Feelings are not a financial plan.
The Numbers That Matter
The math people quote — “you’re earning 21% by paying off a 21% card” — is true only if you never have to re-borrow. The moment you put an emergency on a card because the cash is gone, you’ve erased the gain and added stress.
Your savings account isn’t losing to your credit card — it’s insuring you against it.
Where should this money live? Not your checking account, and not locked in a CD you can’t touch. Keep it in a high-yield savings account — the good ones pay around 4% right now, several times the national average — so your safety net earns something while it waits, and you can reach it in a day or two when you need it.
| Your Situation | What Usually Makes Sense | Why |
|---|---|---|
| No real cushion yet | Build three months first; pay minimums | A cushion prevents the next crisis from becoming new debt |
| Steady income + 3-month cushion + high-rate debt | Use the surplus above your cushion | Guaranteed return; you stay protected |
| Unstable or single income | Keep more in reserve | You’re more likely to need the cash than to regret the interest |
| Being sued / judgment-proof / weighing bankruptcy | Keep your cash; get advice first | You may be paying debt a fresh start could erase |
If a debt relief company is pressuring you to drain savings or borrow to pay them, that’s a red flag — run their name through the Scam-O-Meter and file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, so I know exactly how it feels to want that debt gone — to throw everything at it just to stop the weight of it. But in 30 years of helping people, I’ve watched far more get hurt by having no cash than by carrying a balance a little longer. Your emergency fund is the reason a hard month stays a hard month instead of becoming the month it all fell apart. Pay down debt with what you can truly spare — never with the last dollar standing between you and the next surprise.
This one comes down to YOUR situation. Your job security, what the debt is actually costing you, and whether it’s even worth paying in full all change the answer — and no calculator can weigh those together. That’s exactly the kind of question I built the free Ask Steve chat for — tell me what’s actually going on and I’ll give you my honest read. It’s free and anonymous, and I sell nothing. Everyone else in debt wants to sell you a solution; I just want you to make the right call for you.
Frequently Asked Questions
Should I use my emergency fund to pay off credit card debt?
Only the part you can spare while keeping a real cushion. With the average card near 21% APR, paying down high-rate debt is a strong move — but not if it leaves you with nothing for the next emergency, because you’ll just re-borrow at an even higher rate. I tell people to keep three months of expenses or more and use only the surplus.
How much of my savings is safe to put toward debt?
Keep your cushion first — I tell people to hold three months of expenses or more. Anything above that cushion is fair game for your highest-rate debt. The less stable your income, the bigger the cushion should be, not smaller.
I have $5,000 saved and $5,000 in credit card debt — should I just pay it off?
Probably not all at once. Paying it to zero also takes your safety net to zero, and the first surprise bill puts you right back on the card — now with debt and no cushion. Keep three months of expenses, put the surplus toward the highest-rate balance, and rebuild as you go.
Is it better to keep an emergency fund or be debt-free?
For most people, keep the fund. Being “debt-free” with no cash is fragile — one bad week undoes it. A cushion plus shrinking debt is more stable than zero debt and zero dollars. The exception is small, low balances you can clear while still keeping a buffer.
Should I drain my savings to pay debt if I’m thinking about bankruptcy?
No — stop and get advice first. If you may file, paying unsecured creditors with your savings can be money you’ll never get back, since bankruptcy could discharge that debt anyway. Bankruptcy also protects your retirement accounts. See whether you’re judgment proof and read about the research on how bankruptcy filers recover before spending a dollar.
What if I can’t make my minimum payments at all anymore?
Then the question isn’t your emergency fund — it’s getting real help. Draining savings to make one more month of minimums on debt you can’t sustain just delays the reckoning and leaves you with nothing. Read what to do when you can’t make minimum payments, and look at all your options before you spend your last cushion.
If I do use some of my emergency fund, how do I rebuild it?
Start the same month you make the payment. If paying off a card frees up a $200 minimum, redirect that $200 straight into savings every month until you’re back to your cushion — treat it like a bill you still owe, except now you’re paying yourself. Most people rebuild a three-month fund within a year or two when they send freed-up payments back to savings instead of absorbing them into spending.
What about the “save $1,000 first, then attack debt” advice I’ve heard?
That starter-fund idea has real merit as a first step — it gets people who have nothing saved off zero, and that matters. My disagreement is with stopping there. In 2026, $1,000 covers one bad day: a single car repair or an ER visit and you’re right back on the cards. I’d rather you build toward three months of expenses, even if it takes longer. The debt costs you interest; running out of cash costs you everything.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Look at your numbers, think about your job and your risks, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal or financial advice. Your situation may have details that change what makes sense for you. For advice specific to your case, consult a qualified professional. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: Don’t trade a problem you can survive for one that can sink you. Keep a buffer, pay debt with what you can truly spare, and never empty your last cushion for debt a fresh start could erase. Not sure where your situation lands? Find Your Path in two minutes.
The Bottom Line
You’re not bad with money for having debt and savings at the same time — you’re being careful, and that instinct to protect your cushion is right. The smart move is rarely all-or-nothing. Keep your safety net, attack the high-rate debt with what you can spare, and get a clear-eyed read on whether some of that debt is even worth paying in full. If someone you know is about to empty their savings to pay off debt, send them this page — it might be the buffer that saves them. Then see how all your debt relief options compare and Find Your Path.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 10): Your phone company is supposed to know who’s handing it those scam calls. Some of them don’t bother.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



