

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed June 17, 2026 • Every claim below links to a primary source.
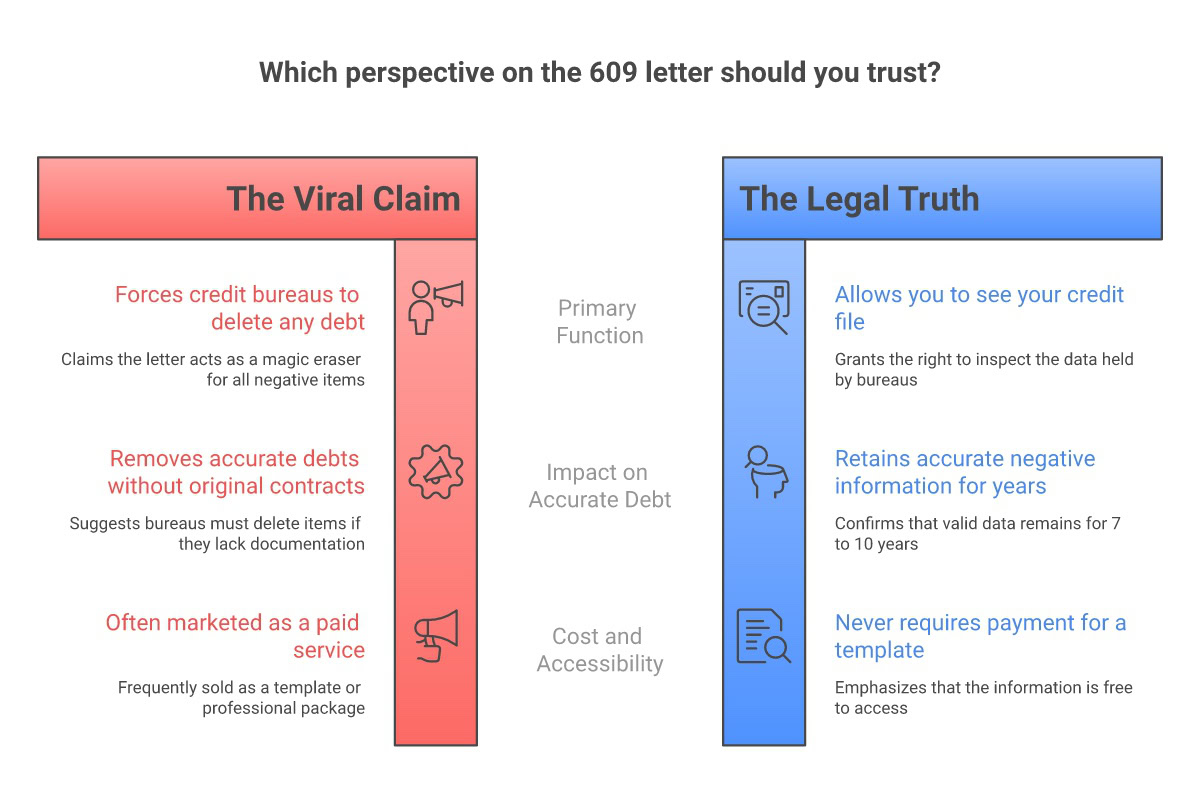
The verdict: Myth. A “609 letter” cannot erase an accurate debt. Section 609 of the Fair Credit Reporting Act is a disclosure right — it lets you ask a credit bureau what’s in your file. It does not force anyone to delete information that is accurate. The law itself says so: a credit bureau “is not required to remove accurate derogatory information” (15 U.S.C. § 1681g(c)(2)(E)). The paid “609 letter template” you keep seeing advertised does nothing the law makes you pay for.
I have to tell you about this one. A “credit repair hack” has been blowing up across TikTok and YouTube, and the promise being passed around goes something like this:
“Send a 609 letter and the credit bureaus are legally required to delete the debt — even accurate negative items — if they can’t produce your original signed contract.” — the viral “609 loophole” claim circulating on TikTok
People are paying real money for “609 letter templates” built on that promise. I couldn’t let it sit, because the law doesn’t say any of that — and the folks who can least afford to waste money are the ones being sold the dream. Let me walk you through what’s actually going on.
Well, Actually…
Here’s the part the videos leave out: Section 609 is real, but it isn’t a delete button. It’s a disclosure rule. When you read the actual statute, 15 U.S.C. § 1681g, all it does is give you the right to ask a credit bureau to “clearly and accurately disclose” what’s in your file and where the information came from. That’s it. There is no language anywhere in § 609 requiring a bureau to delete anything, and no “produce the original signed contract or remove it” rule. That part got bolted onto the myth over time — most likely borrowed from a different law. The Fair Debt Collection Practices Act does let you demand that a debt collector verify a debt it’s collecting from you. That’s a real right — but it applies to collectors contacting you, not to the credit bureaus reporting your file, and even then it doesn’t erase a debt that’s genuinely yours.
And the law goes one step further — it actually says the opposite of the viral claim. Right inside the same section, the FCRA states a credit bureau “is not required to remove accurate derogatory information from the file of a consumer” — unless that information is outdated or can’t be verified, which is exactly why a legitimate dispute of a genuine error can still work. Accurate, current debt stays. The federal regulator agrees: the CFPB says plainly, “You generally cannot have negative information removed from your credit report if it is accurate.” Accurate negative marks come off on their own timetable — most after seven years, bankruptcy after ten — not because you mailed a letter.
So why does anyone ever say it “worked”? Because a disclosure request under § 609 can occasionally surface a genuine error — an account that isn’t really yours, a wrong balance, a duplicate. Those you can dispute and get fixed for free — but that’s a separate process under a different part of the law, FCRA § 611. Either way, that’s correcting a mistake, not erasing a real debt. The trick the sellers pull is taking that narrow, legitimate use and dressing it up as “delete anything you want.”
A 609 letter legally forces the bureaus to delete any debt — even accurate ones — unless they produce your original signed contract.
Section 609 is a right to see your file, not to delete it. The FCRA explicitly says a bureau is “not required to remove accurate derogatory information,” and there is no “original contract” deletion rule anywhere in the law. Accurate negative items legally remain for about seven years (bankruptcy, ten). A paid “609 template” cannot change that — and you never have to pay for one.
Why You Were Told This
Someone is making money from this claim. There’s a whole cottage industry selling “609 letter templates” for anywhere from a few dollars to a few hundred — for a document you can write yourself in ten minutes, or skip entirely. The FTC puts it bluntly: “Anything a credit repair company can do legally, you are able to do yourself at little or no cost.” And the FTC has warned for decades about paying upfront for credit-repair promises — under the federal Credit Repair Organizations Act, a business that qualifies as a credit repair organization can’t legally charge you before the promised service is fully performed. Anyone selling you a template and promising it will erase real debt is banking on a result the law says no one can deliver.
The myth survives because it has a kernel of truth wrapped around a lie. Section 609 exists. Disclosure requests are real. So when someone confidently cites a real statute number, it sounds like inside knowledge. It isn’t. It’s a real law with a made-up superpower bolted on.
What to Actually Do
- Pull your real report for free first. Get all three reports at AnnualCreditReport.com — the only federally authorized free source, now available weekly. Read them line by line.
- Dispute genuine errors — for free, the right way. If something is wrong (not yours, wrong amount, already paid), file a dispute under FCRA § 611. Use the CFPB’s free sample dispute letters. The bureau must investigate, usually within 30 days. Disputing mistakes is free.
- Don’t pay anyone to “delete” accurate debt. No one can legally do it, no matter what the ad promises. If a company asks for an upfront fee or for your Social Security number and credit-bureau login credentials, that’s your signal to walk — and you can run them through the free Scam-O-Meter first.
- If the debt is real and you can’t pay it, deal with the debt — not the report. A clean report doesn’t erase what you owe. Look at your actual options; if the math is broken, the Find Your Path quiz gives you a real read.
Steve’s Take
I’ve watched “secret credit loopholes” come and go for more than thirty years, and they all share one thing: someone is selling the secret. The 609 letter is just the newest costume on a very old scam — the promise that a magic document makes real debt disappear. It doesn’t. What actually rebuilds your credit is unglamorous and free: fix the genuine errors, then show, month after month, that you pay what you owe. I filed bankruptcy in 1990 and rebuilt from zero. Nobody sold me a template to do it. Save your money for the debt itself.
Frequently Asked Questions
What is a 609 letter?
A 609 letter is a written request you send a credit bureau asking it to disclose what’s in your credit file and where the information came from, based on your rights under Section 609 of the Fair Credit Reporting Act (15 U.S.C. § 1681g). It’s a request to see your file — not a formal dispute, and not a tool that deletes accurate information.
Will a 609 letter remove a debt that’s actually mine?
No. Section 609 is a disclosure right, not a deletion tool. The FCRA says a bureau “is not required to remove accurate derogatory information.” If the debt is genuinely yours and reported correctly, a 609 letter won’t make it vanish.
Is the 609 letter a scam?
Section 609 itself is a real, legitimate part of the law. The scam is the overstated promise — that it forces deletion of accurate debts — and especially anyone charging you upfront for a template to do it. The right tool is real; the marketing around it usually isn’t.
Do the bureaus have to delete an item if they can’t produce my original contract?
No. There is no such rule anywhere in Section 609. That “no contract, no debt” idea is invented. Bureaus must investigate items you dispute as inaccurate — that’s a separate process (FCRA § 611) — but accurate items stay.
How long does accurate negative information actually stay on my report?
According to the FTC, “most negative information will stay on your report for seven years, and bankruptcy information will stay on for 10 years.” It falls off on that schedule on its own — no letter required.
Should I pay for a 609 letter template?
No. The FTC says anything a credit repair company can do legally, you can do yourself “for little or no cost.” If you want to dispute a real error, the CFPB’s sample dispute letters are free.
So what DOES fix my credit?
Two things: correcting genuine errors through a free dispute, and time spent paying your obligations as agreed. There’s no shortcut document. If the underlying debt is the real problem, fixing the report doesn’t fix the debt — look at your actual options instead.
One more thing — everything here is based on more than thirty years of helping people through exactly this, but my advice is input for your decision, not the decision itself. Only you know your full situation. Read your own reports, and make the call that serves your future.
The bottom line: A 609 letter lets you see your credit file — it does not force anyone to erase a real debt, and you should never pay for a template that claims otherwise. If someone you know is about to buy a “609 secret,” send them this first.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
If you’ve seen similar credit-repair myths on social media, read about why the “credit sweep” trick is a federal crime — an even more dangerous scam than the 609 letter.
Another debt-collection myth worth knowing: just because a collector has your name and a dollar amount doesn’t mean the debt is real. Here’s how to make them prove it. And before you call any number you found by searching a collector’s name, read who actually answers when you call a collector you Googled.



