

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 18, 2026
Quick Answer: Someone is trying to hand you legal papers — most often a debt collection lawsuit. A process server has zero power to arrest you, enter your home, or make you open the door. But here is the part that surprises people: hiding does not make the lawsuit disappear. When personal service fails, courts let plaintiffs serve you by leaving papers with an adult at your home — and in many states, by taping them to your door and mailing a copy, or even publishing notice in a legal newspaper you’ll never read — and then win by default while you’re still hiding. The smart move is the opposite of your instinct: accept the papers, find out who’s suing you, and answer in time. Don’t ignore this — it gets worse, not better.
What Just Happened
A process server is a civilian whose job is to legally deliver court papers to you. If one is asking your neighbors about you, leaving a card on your door, or calling your relatives, it means a lawsuit — most likely from a debt collector or debt buyer — has already been filed, and they need to formally hand you the summons and complaint. This step is called service of process, and the law requires it before a court can rule against you.
Here’s why it matters: the U.S. Supreme Court held in Mullane v. Central Hanover Bank & Trust that you’re entitled to notice “reasonably calculated” to tell you about the case. But the test is whether the method was reasonable — not whether you personally opened the envelope. That distinction is everything, and it’s the trap most people walk into. “Reasonable” does have limits, though: if the plaintiff knew your real address and published notice anyway, or left papers at a home you moved out of years ago, that service may be invalid — but you can only challenge it if you show up to do so.
The Mistake You’re About to Make: Dodging the process server because you think “if they can’t serve me, they can’t sue me.” That is false, and it’s the single most damaging move you can make. When personal service fails, courts allow substituted service — leaving the papers with a competent adult at your home, and in many states (such as New York) taping them to your door and mailing a copy (“nail and mail”). If you truly can’t be found, a court can authorize service by publication in a legal newspaper you’ll never see — but only after the plaintiff shows the court they made diligent efforts to locate you. Either way, you’re legally served, you don’t show up, and the collector wins a default judgment. You find out months later when your paycheck is garnished. Hiding doesn’t cancel the lawsuit — it just removes you from the room where you could have fought it.
Your Options Right Now
What to Do in the Next 48 Hours
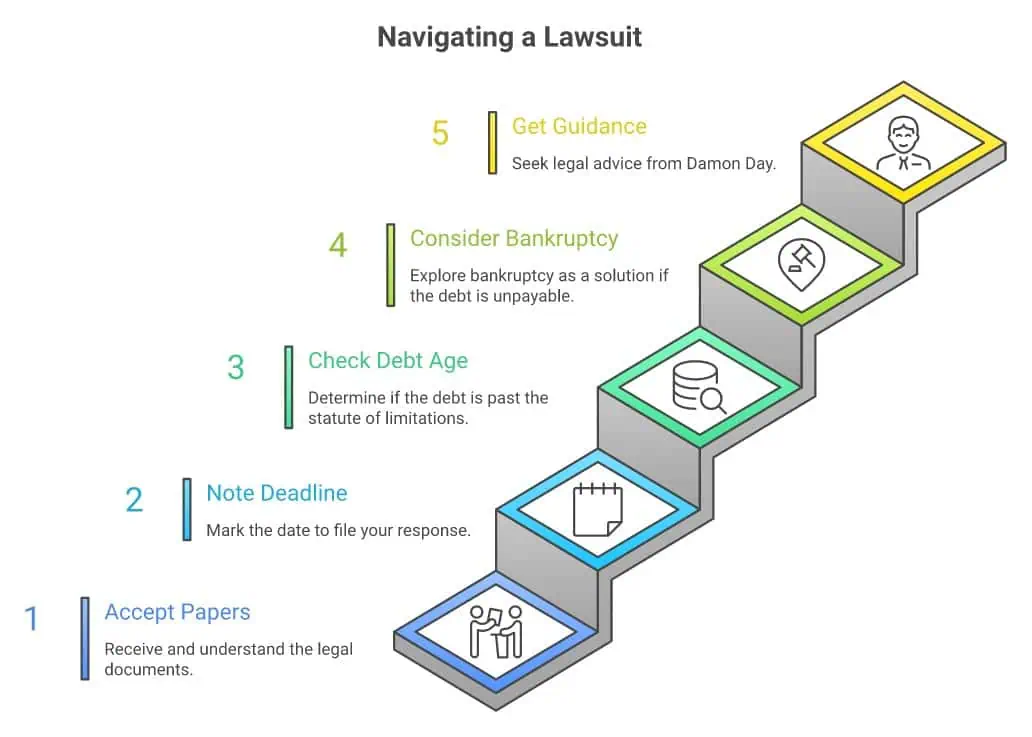
- Accept the papers — don’t run. The papers tell you exactly who is suing you, for how much, and which court. You cannot defend yourself against a lawsuit you refuse to read. Accepting service does not admit you owe anything; it just starts the clock you control.
- Read the summons — it states your exact deadline. The papers themselves tell you how long you have to file a written Answer, and that number controls. It’s typically 20 to 30 days depending on your state and how you were served (21 days in federal court under FRCP 12(a); California 30 days; Florida 20; New York is 20 days if handed to you in person but 30 if served any other way). Don’t guess from a general rule — use the date on your papers. Miss it and the plaintiff gets a default judgment without you.
- Check whether the debt is too old to sue on. If the statute of limitations has passed, the suit may be improper — but only if you show up and raise it. The CFPB is blunt: a court can still rule against you if you don’t appear and assert the expired statute of limitations as a defense. Use the Find Your Path quiz to think through your situation.
- If you can’t afford the debt at all, weigh bankruptcy. Filing bankruptcy triggers the automatic stay under 11 U.S.C. § 362, which instantly stops the lawsuit from moving forward — the creditor can’t continue the case, can’t get a judgment, and can’t start new collection. A free consult with a NACBA bankruptcy attorney tells you fast whether it fits. See if it’s right for you with the Brain on Debt quiz.
- Get free, honest guidance before you decide anything. Talk to Damon Day for free — he sells nothing and will give you a straight read on whether to fight, settle, or file.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
How to Actually Handle It — Your Real Paths
- Show up and answer (almost always the right first move). Filing an Answer by the deadline keeps your defenses alive: wrong amount, wrong person, debt already paid, expired statute of limitations, or the plaintiff can’t prove it owns the debt. This last one matters most against a debt buyer — they often can’t produce the original contract and a clean chain of ownership for your account. Don’t count on it as a magic bullet, but the only way to make them prove it is to answer and demand the documents.
- File bankruptcy if the debt is unpayable. The automatic stay stops the lawsuit cold the moment you file — no hearing needed. If a creditor knowingly keeps pursuing you after they’ve been notified of your filing, that willful violation can make them owe you damages under § 362(k).
- Negotiate — but get every term in writing first. A settlement before judgment is possible, but never pay or promise anything on a phone call. If it isn’t in writing, it doesn’t exist.
- What WON’T work: Hiding from the server, ignoring the summons, or hoping it goes away. Debt settlement companies and consolidation loans don’t stop a lawsuit that’s already filed — only a timely Answer, a settlement, or bankruptcy does.
What You Need to Know About Your Rights
A process server is a civilian, not law enforcement. They cannot arrest you, force you to open your door, enter your home, or threaten you. A debt lawsuit is 100% civil — you cannot be jailed for owing a debt; debtors’ prisons ended in the 1800s. The one remote arrest risk comes far down the road and only through a long chain: a judgment is entered, the creditor then separately serves you with an order to appear at a debtor’s examination, and you ignore that court order. Only then can a judge issue a “body attachment” for contempt — and that’s for defying the court, not for the debt itself. You end it by appearing and complying. No one is coming to arrest you for an unpaid bill.
When the collector calls your relatives, neighbors, or employer trying to locate you, they’re bound by 15 U.S.C. § 1692b (which covers most consumer debts): they may contact a third party once to confirm your location, must identify themselves by name, but may not reveal that you owe a debt, may not state they’re a debt collector, and may not contact that person repeatedly. If they told your sister or your boss you owe money, that’s a violation.
| Situation | What the law allows | What it means for you |
|---|---|---|
| You won’t open the door | Substituted service — papers left with an adult at home (FRCP 4(e); CA CCP § 415.20; NY CPLR 308) | You’re still legally served |
| You can’t be located at all | Service by publication in a legal newspaper, with court approval | A default judgment can follow without you ever seeing it |
| You were never actually served (sewer service) | Motion to vacate the default judgment | You must act the moment you learn of it — see the 2026 ruling below |
| Debt is past the statute of limitations | Affirmative defense you raise in your Answer (CFPB) | Only protects you if you show up and assert it |
If you find a judgment you were never told about: “Sewer service” — a process server falsely swearing they served you — is a documented abuse. In Sykes v. Mel S. Harris, a debt-buying operation obtained more than 120,000 default judgments with fake service affidavits; the case settled for $60 million and vacated roughly 195,000 judgments. If your wages were suddenly garnished over a lawsuit you never knew about, you may be able to vacate the judgment — but the Supreme Court’s January 2026 decision in Coney Island Auto Parts v. Burton requires you to file within a “reasonable time” that starts the moment you learn of the judgment. What counts as “reasonable” depends on your facts — which is exactly why you should call a lawyer the same day you find out rather than guess at it. Don’t wait.
If a collector revealed your debt to others, lied, or you suspect false service, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov. For a consumer attorney, NACA can connect you with one.
Steve’s Take
I filed bankruptcy in 1990, so I know what it feels like to want to make a problem vanish by not looking at it. But in 30 years of helping people, I’ve watched the same heartbreak over and over: someone dodges the server, feels relief for a few weeks, then gets a garnishment notice for a judgment they never had a chance to fight. The shame keeps people hiding, and the hiding is exactly what the collector is counting on. You are not a bad person for being in debt. The system actually gives you protections — an Answer deadline, defenses, the automatic stay — but every one of them requires you to show up. The people who answered the door and answered the lawsuit did dramatically better than the ones who ran.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
Frequently Asked Questions
A process server is looking for me — can I just avoid being served?
You can dodge for a while, but it won’t stop the lawsuit. When personal service fails, courts allow substituted service (papers left with an adult at your home under FRCP 4(e) and state rules like CA CCP § 415.20) or even service by publication. Once that happens you’re legally served whether you saw the papers or not — and a default judgment can follow.
Do I have to personally take the papers from the process server?
No, and that’s the misconception that hurts people most. In most states, leaving the papers with a competent adult who lives at your home counts as valid service, and in many states taping them to your door and mailing a copy does too. Refusing to take them by hand changes nothing.
Can a process server arrest me or come into my house?
No. A process server is a civilian with no law enforcement authority. They cannot arrest you, enter your home, or force you to open the door. You cannot be jailed for owing a debt — that’s civil, not criminal.
What happens if I don’t respond after I’m served?
The plaintiff asks the court for a default judgment, which they almost always get. From there they can pursue wage garnishment, bank levies, and property liens. Filing a written Answer by your deadline (usually 20–30 days) is what keeps your defenses alive.
The debt is really old — can they still get a judgment?
Yes, if you don’t show up. The statute of limitations is an affirmative defense you must raise in your Answer. The CFPB explains that a court can still rule against you on time-barred debt if you fail to appear and assert it. Suing on expired debt may itself violate the FDCPA — but that won’t save you from a default judgment if you stay home.
The collector has been calling my family and my boss — is that legal?
Only narrowly. Under 15 U.S.C. § 1692b, a collector may contact a third party once to confirm where you are and must identify themselves by name, but may not reveal that you owe a debt, may not state they’re a debt collector, and may not contact that person repeatedly. If they told anyone about your debt, that’s a violation you can report to the CFPB.
I filed bankruptcy — how fast does it stop the lawsuit?
Immediately. The automatic stay under 11 U.S.C. § 362 takes effect the moment you file, with no hearing required. It stops the lawsuit from moving forward — the creditor can’t continue the case, get a judgment, or start new collection actions. A creditor who knowingly keeps pursuing you after being notified of your filing can owe you damages under § 362(k) for that willful violation.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A process server can’t arrest you or force the door — but hiding doesn’t stop the lawsuit. Substituted service and publication exist precisely to serve people who dodge. Accept the papers, note your Answer deadline, and use the debt relief options calculator to plan your move. The longer you wait, the closer you get to a default judgment you never fought.
The Bottom Line
You’re not bad with money — you’re scared, and your instinct is to disappear. But the law built real protections into this process: a deadline you control, defenses you can raise, and the automatic stay if you need it. Every one of them requires you to stop running and step into the room. The people who answered the door and answered the lawsuit consistently did better than the ones who hid. If someone you know is ducking a process server, send them this page — it could be the difference between fighting the lawsuit and losing it without ever showing up. Start with the Find Your Path quiz to see your options.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 10): Your phone company is supposed to know who’s handing it those scam calls. Some of them don’t bother.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



