

Quick Answer: If a debt collector is calling about a store card — any store card — start a written log right now. Date, time, what they said, any threats. The Fair Debt Collection Practices Act (FDCPA) gives you enforceable rights, but those rights are only worth something if you have documentation. A June 2026 class action lawsuit filed in federal court alleges Synchrony Bank — the company that backs a vast number of retail store cards — continued calling a consumer over 100 times after she revoked consent and retained legal counsel. Her paperwork is what makes a case. Yours should too.
Part of the FDCPA Rights Hub: This post is one piece of my complete Debt Collectors and Your FDCPA Rights: The Complete Guide — what collectors can and cannot do, how to stop calls, demand validation, fight back in court, and sue collectors who cross the line.
Expert Context: I’ve studied debt collection tactics since the 1990s — including as someone who was on the receiving end after my own 1990 bankruptcy. I also ran a nonprofit credit counseling organization where I saw, up close, how store-card collections escalate and how quickly a consumer’s legal rights evaporate when there’s no paper trail. The people who fight back successfully are almost always the ones who wrote things down.
Here’s the thing most people don’t know about store cards: one bank is probably behind most of the ones in your wallet. Synchrony Bank — the largest issuer of retail store credit cards in the United States, with over 80 million customer accounts — provides the financing behind an enormous roster of branded retail cards. When a store-card debt goes to collections, the collector is often working on behalf of Synchrony, not the retailer whose name is on the card. That changes things, because Synchrony’s collectors are subject to federal law, and a federal court in California is now being asked to weigh whether those limits were honored.
Key Terms Defined
FDCPA (Fair Debt Collection Practices Act): Federal law (15 U.S.C. §1692) that governs what third-party debt collectors can and cannot do. Bans harassment, false statements, and contact after you’ve told them in writing to stop.
TCPA (Telephone Consumer Protection Act): Federal law (47 U.S.C. §227) that restricts robocalls and autodialed calls to your cell phone without your consent.
RFDCPA (Rosenthal Fair Debt Collection Practices Act): California’s state-level version of the FDCPA, which applies to original creditors (not just third-party collectors) collecting their own debts.
Revocation of Consent: When you formally tell a creditor or collector — in writing — to stop contacting you by phone. Under the TCPA, continuing to call after revocation is a federal violation.
What You Need to Know
On June 17, 2026, Top Class Actions reported that a class action lawsuit has been filed against Synchrony Bank in the U.S. District Court for the Southern District of California (Case No. 3:26-cv-03349-AJB-BJW). The plaintiff, Iman Habel, alleges that she fell into financial hardship in November 2025 on a PayPal credit account — issued by Synchrony — and that after she retained legal counsel and sent a cease-and-desist letter revoking consent for prerecorded calls in January 2026, Synchrony representatives allegedly continued calling her cellphone with prerecorded voice messages more than 100 times.
The lawsuit alleges violations of California’s RFDCPA and the federal TCPA. The plaintiff is seeking to represent a nationwide class of consumers who received prerecorded calls from Synchrony Bank after they had revoked consent. To be clear: these are allegations in a filed lawsuit. No court has ruled on whether Synchrony violated any law. The case is in early stages. I’m not calling Synchrony a law-breaker — a court will decide that. What I’m saying is that the conduct alleged is a textbook example of what the FDCPA and TCPA are designed to prevent, and it’s a good prompt for every store-card holder to understand their rights.
Which cards are Synchrony-backed? The Synchrony-issued retail card lineup is large — Upgraded Points lists over 140 Synchrony store cards including Amazon Store Card, Sam’s Club, PayPal Credit, JCPenney, Lowe’s, Belk, CareCredit, Guitar Center, TJX (Marshalls/TJ Maxx/HomeGoods), and more. Verify whether your specific card is Synchrony-issued by checking your statement or calling the number on the back of the card. The issuing bank is disclosed on every statement.
Free Tool — Debt Collector Rights Lookup: Being contacted by a debt collector? The free Debt Collector Rights Lookup shows your state-specific protections — statute of limitations, garnishment limits, and what collectors are legally prohibited from doing. Look Up Your Rights →
Why You Need to Know It
I’ve been helping people navigate debt since 1994. In all those years, the single biggest predictor of whether someone successfully enforces their FDCPA rights isn’t their knowledge of the law — it’s whether they can prove what happened. Without dates, times, and details of what a collector said, you have no case. With them, you may have a federal claim worth $1,000 per violation in statutory damages, plus actual damages and attorney fees.
Here’s the insider view that most debt advice misses: store-card collections can be aggressive precisely because store cards are often marketed to people with thin credit histories or financial stress. The cards are easy to get. When borrowers fall behind, the collections can escalate quickly. I’ve watched this pattern play out repeatedly — a consumer is struggling, they miss payments, and then calls start. The consumer doesn’t know their rights. They don’t document. They either pay under pressure or default silently. Neither is the right outcome when the collector may have crossed legal lines.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
There’s also something important about the “one bank behind many cards” reality. A lot of people think they’re dealing with the store where they shop. They’re not. They’re dealing with a financial institution operating under federal banking and consumer protection law. That institution knows the FDCPA. Whether it follows it is a different question — one that courts increasingly have to answer.
“Conservative estimates suggest that 70% to 90% of debt collection lawsuits brought against unrepresented defendants result in default judgments.” — Neil L. Sobol, Protecting Consumers from Zombie-Debt Collectors (2014)
Things to Consider
Let me walk you through what a collector can and cannot do under federal law — because most people getting these calls don’t know where the line is:
The Myth: “A debt collector can call me as many times as they want, whenever they want.”
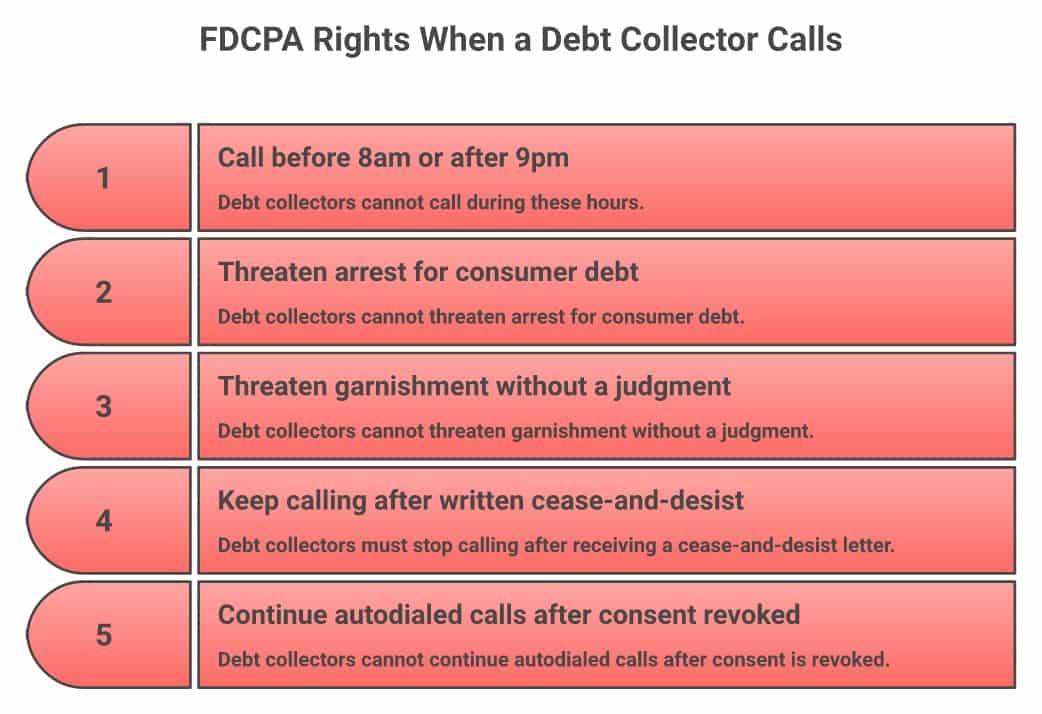
The Reality: False. Under 15 U.S.C. §1692d, calling repeatedly or continuously with intent to annoy, abuse, or harass is an FDCPA violation. Calling before 8 a.m. or after 9 p.m. (your local time) is also prohibited. Calling your workplace if they know your employer prohibits such calls is prohibited. The CFPB’s Regulation F also limits collectors to seven calls within seven days regarding a specific debt.
The Myth: “If they say they’ll have me arrested, they can.”
The Reality: A false threat of arrest for a consumer debt is an FDCPA violation under 15 U.S.C. §1692e. Collectors cannot threaten legal action they don’t intend to take, cannot claim to be law enforcement, and cannot threaten criminal consequences for civil debt. If a collector says “you’ll be arrested” for not paying a credit card, write it down — that’s a $1,000 federal claim right there.
The Myth: “They said they can garnish my wages — so I’d better pay now.”
The Reality: A debt collector cannot garnish your wages without first suing you in court, winning a judgment, and then obtaining a garnishment order. Threatening garnishment without a judgment is false and deceptive under §1692e. Social Security benefits, disability benefits, and veterans’ benefits have additional protections and are generally exempt from garnishment. Don’t be scared into paying by an illegal threat.
Things You Might Want to Think About Doing
Here’s the practical checklist. Start right now, before anything else.
Step 1: Start Your Call Log — Every Single Call
Create a dedicated document — paper or digital, whatever you’ll actually maintain. For every collector contact, record:
- Date and time of the call
- The phone number they called from (save it)
- The name they gave (collectors are required to disclose this under §1692d(6))
- The company they claimed to represent
- Exactly what they said — especially any threats, claims about legal action, or statements about what you owe
- Whether they left a voicemail (save it — don’t delete it)
- Whether they used a recorded or artificial voice
This log is your evidence. If a collector violates the FDCPA, each individual violation is a separate claim worth up to $1,000 in statutory damages. A collector who calls 100 times after you revoke consent isn’t just annoying — they’re potentially writing checks.
Step 2: Revoke Consent in Writing
If you’ve been getting prerecorded or autodialed calls to your cell phone, you can revoke consent for those calls under the TCPA. Do it in writing, and do it via certified mail with return receipt. Keep a copy. Note the date it was mailed. Note when the delivery receipt comes back.
Under the FDCPA, you can also send a cease-and-desist letter demanding they stop contacting you entirely. Note: that doesn’t make the debt go away, and it can prompt them to sue. But it does stop the calls — legally. Use my Debt Validation Letter Generator to start this process properly.
Step 3: Never Agree to Payment Terms Under Phone Pressure
Here’s something I’ve seen trip people up over and over: a collector calls, uses pressure tactics, and the person being called makes a verbal commitment to pay, sometimes agreeing to a payment plan, sometimes giving a bank account number. Don’t do it. Not on the phone. Not under pressure.
- Never give a bank account number over the phone to a debt collector
- Never agree to a new payment plan verbally — get everything in writing first
- Never restart a payment on a debt that may be past the statute of limitations (it can restart the clock)
- Never confirm that you owe the debt without first requesting debt validation
They have lawyers. You deserve to take a breath, read anything before signing it, and if necessary, talk to someone who can advise you. That’s not avoidance — that’s prudent.
Step 4: Request Debt Validation
Under 15 U.S.C. §1692g, within 30 days of first contact, you have the right to request written validation of the debt. Send this in writing, certified mail. They must stop collection activity until they verify the debt. This is especially important for store cards that may have been sold or transferred — you want to confirm who actually owns the debt and whether the balance they claim is accurate.
Step 5: Know Where to Go If They Cross the Line
If you believe a collector has violated the FDCPA, you have three options:
- File a CFPB complaint: Go to consumerfinance.gov/complaint/ — the CFPB tracks these and the complaint itself can generate a response
- Find a consumer attorney: FDCPA cases can be filed in federal court, and many consumer attorneys take FDCPA cases on contingency (no upfront cost to you). Find one through NACA (National Association of Consumer Advocates)
- Talk to someone first: If the debt itself is the bigger problem and you’re not sure what to do, Damon Day offers a free phone consultation and can help you see the full picture before you make any decisions
What If the Underlying Debt Is Unmanageable?
I want to say this plainly, because I get so many questions that start with collector pressure and end up revealing that the debt itself is the real problem: if you’re getting collector calls because you’re genuinely unable to pay, that’s a different conversation than “how do I stop illegal calls.”
Stopping the calls is one problem. The debt is another. And if the debt is large enough that a collector is this persistent, you need to think through your full situation — not just the calls. Take the all-options calculator or the 2-minute bankruptcy quiz. There’s a reason Federal Reserve research shows bankruptcy filers recover faster than those who don’t file — bankruptcy triggers an automatic stay that stops all collection immediately, including the calls. Sometimes the cleanest answer to “make the calls stop” is “eliminate the debt.”
If you’re on fixed income, Social Security, disability, or veterans’ benefits, you likely have even more protection than you think. I cover that specific situation here.
Key Takeaways
- A federal class action filed June 2026 alleges Synchrony Bank made 100+ autodialed calls after a consumer revoked consent — this is the kind of conduct the FDCPA and TCPA are designed to prevent
- Synchrony backs over 140 retail store cards — the company behind your store card may be the same bank named in this case
- Your paper trail is your power: log every call — date, time, caller name, what was said
- Key FDCPA prohibitions: threats of arrest, threatening garnishment without a judgment, calling before 8 a.m. or after 9 p.m., calling after you’ve sent a cease-and-desist letter
- Don’t agree to anything under phone pressure — get it in writing first
- CFPB complaint + NACA attorney referral + FDCPA statutory damages ($1,000/violation) are your tools if lines are crossed
The Bottom Line
If you’re getting these calls at 7 in the morning or at dinner, feeling that knot in your stomach every time your phone rings — I know that feeling. It’s not just annoying, it’s designed to wear you down. But the law is on your side in ways most people don’t realize until it’s too late to use it. Debt is math wrapped in emotion, and right now the emotion they’re banking on is your fear. Write down the calls. Request validation. Send a cease-and-desist. If they keep going anyway, that’s not just harassment — it’s potentially a federal claim with real dollars attached. You don’t have to take it lying down, and you don’t have to figure this out alone. Start the log today.
Frequently Asked Questions
What should I write down when a debt collector calls about a store card?
Record the date and time of every call, the phone number, the name the collector gave, the company they claim to represent, and exactly what they said — especially any threats about legal action, arrest, garnishment, or claims about the amount you owe. Save voicemails. This documentation is your evidence if you need to file an FDCPA complaint or pursue damages in federal court.
Can a debt collector keep calling after I tell them to stop?
No. Under the FDCPA (15 U.S.C. §1692c), if you send a written cease-and-desist letter, they must stop contacting you — they can only notify you of specific actions like filing a lawsuit. If the calls are prerecorded or autodialed to your cell phone, you can also revoke consent under the TCPA. Do both in writing via certified mail with return receipt so you have proof of when they received it.
Is Synchrony Bank actually the company behind my store card?
Synchrony Bank is the largest retail card issuer in the United States, with over 140 branded store cards according to published lists. Cards backed by Synchrony include PayPal Credit, Sam’s Club, Amazon Store Card, JCPenney, Lowe’s, CareCredit, and many others. Check your statement or the number on the back of your card — the issuing bank must be disclosed. If it says Synchrony Bank, then Synchrony’s debt collection practices are directly relevant to your situation.
What FDCPA violations are worth reporting immediately?
Report these to the CFPB at consumerfinance.gov/complaint/ and consider consulting an FDCPA attorney: threats of arrest for a consumer debt; threats of wage garnishment before a court judgment; calls before 8 a.m. or after 9 p.m. your time; calling your workplace when they know it’s not allowed; claiming to be a law enforcement officer; making false statements about the amount you owe; and continuing to call after receipt of a cease-and-desist letter. Each violation is a separate claim worth up to $1,000 in statutory damages.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What if I can’t pay the store card debt at all?
Then the collector calls are a symptom, not the problem. If the underlying debt is unmanageable, stopping the calls only delays the larger question. Bankruptcy provides an automatic stay that stops all collection activity — including calls — immediately upon filing. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file. Take the 2-minute bankruptcy quiz to see if it’s the right option for your situation, or talk to Damon Day for a free consultation.
This post reflects my personal views and experience. It is not legal advice. Only an attorney familiar with your specific circumstances can give you legal advice. My job is to make sure you have all the information — what you do with it is your decision.
If this was useful, please send it to someone who is getting collector calls and doesn’t know their rights. Most people being called have no idea that the law protects them — and that the paperwork they’re not keeping is exactly what they’d need to fight back.
Know Your Rights: If a debt collector is contacting you, you have legal protections. See the complete list of FDCPA violations collectors commit most often. Use the free Debt Validation Letter Generator to demand proof of the debt, or check this collector’s complaint history with the Scam-O-Meter.
Dealing With Debt? Before you pay a collector, understand all your debt relief options — including ones the collector won’t tell you about. If the debt feels unmanageable, take the 2-minute bankruptcy quiz to see if the math favors a fresh start. Federal Reserve research shows filers recover faster than those who don’t file.



