

Quick Answer: The new 1% federal student loan autopay discount does not reach borrowers who are in default — you can’t enroll in autopay while your loans are in default, so you’re locked out of the savings until you fix the default first. The way back in is either loan rehabilitation (9 on-time, income-based payments over 10 months) or consolidation (faster, but with a real tradeoff after July 1, 2026). Both are free through your servicer, and once you’re out of default you can finally turn on autopay and claim the discount.
Expert Context: I’ve tracked federal student loan programs since I founded my first debt-help organization in 1994, and I’ve watched multiple administrations change the rules mid-stream. The pattern never changes: a new benefit gets announced, the headlines celebrate it, and the people who need help most — the ones already in default — quietly find out they’re not invited. That’s exactly what just happened here.
The U.S. Department of Education just expanded the autopay discount on federal student loans to a full percentage point — but if you’re one of the millions of borrowers in default, you can’t get it, and almost nobody is telling you why or what to do about it.
Here’s the part the celebratory headlines skipped: Fortune reported on June 20, 2026 that the bigger discount excludes the borrowers who are currently in default — a group Fortune put at nearly 9 million people. (The U.S. government’s own Federal Student Aid data counted more than 7.7 million in default as of December 2025, and the number has been climbing fast.) If that’s you, this post is the one written for your situation — not the one telling everyone to go sign up.
What you need to know
The Department of Education’s announcement stacks a new 0.75% reduction on top of the long-standing 0.25% autopay discount, for a combined 1 percentage point off your interest rate. (If you’re not in default, I covered how to grab it in this companion post.) Two things you need to keep straight about it:
- It’s temporary — the bigger discount runs from July 1, 2026 through June 30, 2028. After that, it reverts to the old 0.25% unless it’s extended.
- It applies to federal Direct Loans originated after July 1, 2012. Older loans, including many commercially held FFEL loans, aren’t covered.
And the catch that matters most for this post: you have to be enrolled in autopay to get it, and you cannot enroll in autopay while your loans are in default. That single rule is what shuts out everyone in default. The discount isn’t denied to you on purpose — it’s just out of reach until you’re no longer in default. So the real question isn’t “how do I get the discount?” It’s “how do I get out of default?”
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Why you need to know it
In my experience, default rarely travels alone. The Federal Reserve Bank of New York’s researchers found that about 3.6 million borrowers fell into default over just two quarters as collections resumed, and the typical defaulter isn’t who people picture. The New York Fed’s Liberty Street Economics analysis found the average defaulter is nearly 40 years old and was current on their loans before the pandemic — and that 56% of them are also behind on credit cards, 40% on auto loans, and 20% on a mortgage.
That last part is the reason I want you to act, and not out of panic. If you’re in default, the missing autopay discount is the small problem. The big problem is that default quietly poisons everything else — your credit, your ability to refinance a car, your shot at a mortgage. Fixing the default is what actually moves the needle. The 1% discount is just the small, satisfying bonus you collect at the end of doing the important thing.
Things to consider — the two ways out, and the trap inside one of them
There are two real paths out of federal student loan default. They are not the same, and in 2026 the difference between them got bigger.
Rehabilitation
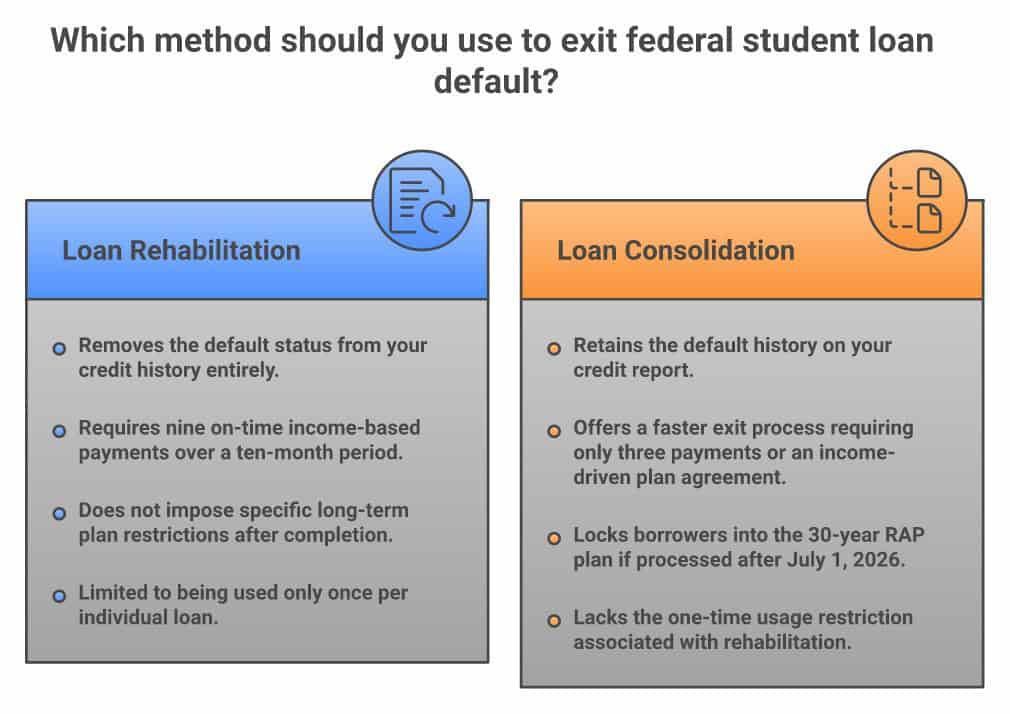
You make 9 voluntary, on-time, income-based payments over 10 consecutive months. Those payments can be as low as a few dollars a month because they’re based on your income. When you finish, the default record comes off your credit report — a meaningful credit benefit consolidation doesn’t give you. Under current law you can rehabilitate a loan only once (a second-rehab option exists in the law but doesn’t start until July 1, 2027).
Consolidation
You either make 3 consecutive on-time payments first, or agree to an income-driven repayment plan, and your defaulted loans roll into a new Direct Consolidation Loan. It’s faster than rehab — though it still takes weeks, not a day — and it’s the route to take if you need access to repayment options quickly. One thing to know: any collection costs already on your defaulted loan get rolled into the new balance.
The 2026 trap inside consolidation: If you consolidate on or after July 1, 2026, you’re treated as a new borrower — and the only income-driven plan you can enroll in is the new RAP plan, which forgives after 30 years. You lose access to IBR’s shorter 20- or 25-year forgiveness timeline. That doesn’t make consolidation wrong, but it means “faster” can cost you years on the back end. Rehabilitation generally preserves more of your options. Choose with that tradeoff in front of you, not behind you.
One more thing I won’t let you skip: getting out of default is free. You do it through your loan servicer or at studentaid.gov. If any company offers to “get you out of default” for an enrollment fee, a monthly subscription, or a “maintenance” charge, walk away. They’re selling you something the government does for nothing. I’ve watched the FTC shut these operations down for years, and there’s always another one waiting.
What to think about doing
- Call your servicer this week and say the two magic words: “loan rehabilitation.” Ask what your income-based rehab payment would be. If you don’t know who your servicer is, log in at studentaid.gov.
- Compare rehab vs. consolidation with the July 1 RAP tradeoff in mind. If your credit recovery matters and you can manage 9 small payments, rehab is usually the stronger long-term move. If you need speed and access more than the credit benefit, consolidation may fit — just go in knowing about RAP.
- Once you’re out of default, turn on autopay and claim the 1% discount before the September 30, 2026 enrollment window matters for the timing of the benefit.
- If your loans were stranded in the SAVE plan (which a federal court vacated in March 2026), you’ll need to pick a new plan by September 30, 2026 anyway — handle that at the same time.
For the full step-by-step on getting out of default, I wrote a dedicated guide: My Student Loans Are in Default — Here’s What to Do Right Now. And if the bigger picture is that your total debt has simply become unpayable — not just the student loans — that’s a different and honest conversation worth having with a bankruptcy attorney through NACBA, or a free, no-sales-pitch phone call with Damon Day.
Key Takeaways
- The new 1% autopay discount is temporary (July 2026–June 2028) and you must be enrolled in autopay — which you can’t do while in default.
- Get out of default first. The discount is the bonus, not the goal.
- Rehabilitation (9 income-based payments) removes the default from your credit report; consolidation is faster but, after July 1, 2026, locks you into the 30-year RAP forgiveness timeline.
- Exiting default is free — never pay a company for it.
The Bottom Line
If you saw the headline about the bigger student loan discount, tried to sign up, and hit a wall because you’re in default — you’re not being punished, and you’re not stuck. You’re one phone call away from a path back. Nearly 8 million people are standing exactly where you are, most of them people who were doing fine until life changed the math on them. Default is a status, not a verdict on who you are. Make the call this week, take the small payments one at a time, and in less than a year you can be out, rebuilding, and yes — finally collecting that discount. The hardest part is picking up the phone. Everything after that gets easier.
Frequently Asked Questions
Can I get the new 1% student loan autopay discount if my loans are in default?
No. You must be enrolled in autopay to receive the discount, and you cannot enroll in autopay while your federal loans are in default. You first have to get out of default through rehabilitation or consolidation, then enroll in autopay to claim the 1% reduction.
What is the fastest way to get out of student loan default?
Direct Consolidation is generally faster than rehabilitation — it can be done after 3 consecutive on-time payments or by agreeing to an income-driven repayment plan, and it processes in weeks. Rehabilitation takes about 10 months but removes the default from your credit report, which consolidation does not.
Does getting out of default cost money?
No. Both rehabilitation and consolidation are free through your loan servicer or at studentaid.gov. If a company charges an enrollment, subscription, or maintenance fee to “get you out of default,” it is selling you something the government provides at no cost — walk away.
What is the risk of consolidating my defaulted loans after July 1, 2026?
If you consolidate on or after July 1, 2026, you’re treated as a new borrower and the only income-driven plan available is the RAP plan, which forgives remaining balances after 30 years. You lose access to IBR’s shorter 20- or 25-year forgiveness timeline. Rehabilitation generally preserves more repayment options.
How many borrowers are in student loan default right now?
Estimates range from more than 7.7 million (Federal Student Aid data as of December 2025) to nearly 9 million (as reported by Fortune, which includes borrowers in late-stage delinquency). The number has risen sharply since collections resumed after the pandemic pause.
This is what I’m seeing after more than 30 years of helping people dig out of debt. Take it as one experienced perspective, not marching orders — you know your own situation better than anyone, and only you get to decide what’s right for it. Use this as input, weigh it, and then make your own call. Nobody gets to tell you what to do with your money. Not a servicer, not a salesperson, and not me.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



