

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 22, 2026
Quick Answer: If you’ve gotten a default notice or a sale date, your home is not gone yet — foreclosure is a process with deadlines, and you have rights at every step. Federal rules generally bar your servicer from starting foreclosure until you’re more than 120 days behind, and submitting a complete loss-mitigation application can pause a scheduled sale. The fastest emergency brake is bankruptcy’s automatic stay, which stops a sale the moment you file. Call a free HUD-approved housing counselor today. Don’t ignore the notices — the options shrink as the sale date gets closer.
What Just Happened With Your Mortgage
You fell behind on payments, and at some point your servicer sent a notice — a notice of default, an acceleration letter, or in some states a notice of sale. That notice is the legal starting gun for foreclosure, the process a lender uses to take and sell the home that secures your loan. Under federal mortgage servicing rules, your servicer generally can’t make that first official foreclosure filing until your loan is more than 120 days delinquent (12 CFR 1024.41(f)) — with limited exceptions, such as a due-on-sale clause violation or when the servicer is joining another lienholder’s foreclosure. If a reverse mortgage (HECM) is involved, the rules are different — see the crisis guide for surviving spouses and heirs facing HECM foreclosure.
If your home was lost to a property tax lien or tax deed sale instead of mortgage foreclosure, the rules and timeline are different — see the crisis guide on what to do if your property tax lien was sold.
How fast it moves from there depends on your state. Judicial-foreclosure states require the lender to go through court, which can take close to a year or more. Non-judicial states let the lender sell through a power-of-sale clause without a court case, sometimes in just a few months. Either way, the clock matters — and acting early is what keeps the most doors open.
The Mistake You’re About to Make: Out of shame or fear, a lot of people stop opening the mail, move out early, or hand money to the first company that promises to “save” the house for an upfront fee. All three make things worse. Abandoning the home can forfeit protections and even create liability; ignoring notices lets deadlines pass; and paying upfront is the calling card of a foreclosure-rescue scam. Read your options first — then act.
Your Options Right Now
What to Do in the Next 48 Hours
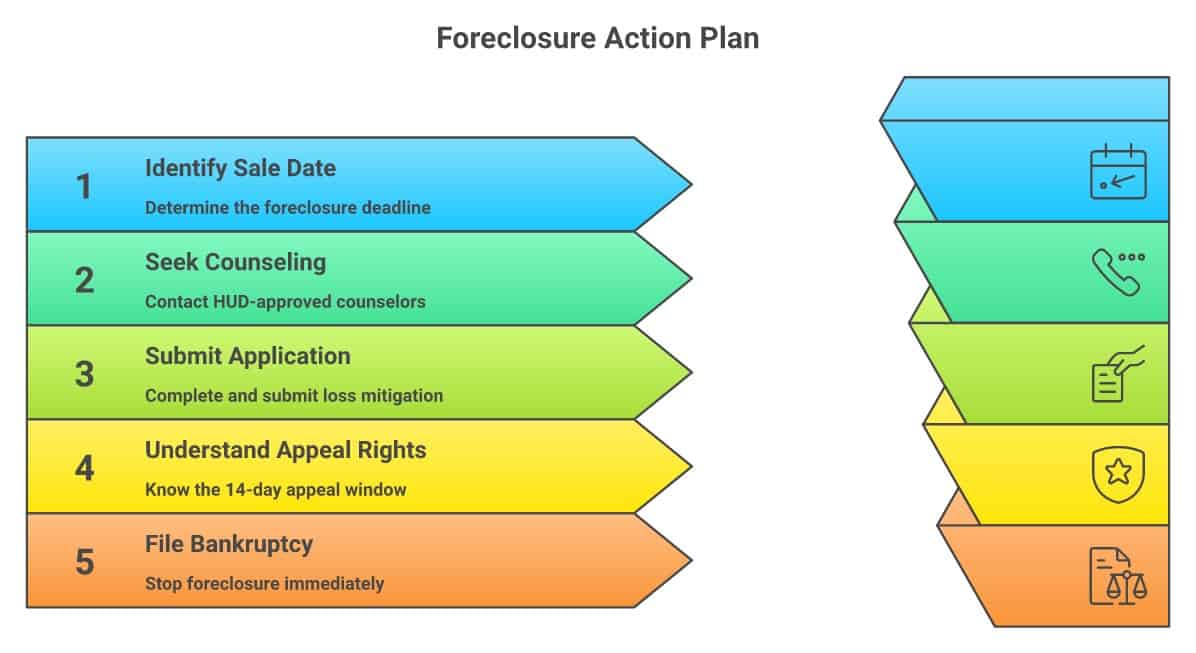
- Open every notice and find your dates. Look for a sale date, a response deadline, and your servicer’s loss-mitigation contact. Everything below runs on those dates.
- Call a free HUD-approved housing counselor. Dial 800-569-4287 or use hud.gov/findacounselor. Foreclosure counseling is always free, and a counselor can request options on your behalf.
- Submit a complete loss-mitigation application to your servicer in writing. If you submit a complete application more than 37 days before a scheduled sale, your servicer generally cannot move for a foreclosure judgment or hold the sale until it evaluates you (12 CFR 1024.41(g)). This is the “dual-tracking” protection.
- Know your appeal right. If the servicer denies you for a loan modification — and your complete application was submitted either before the servicer filed the first foreclosure notice OR more than 90 days before a scheduled sale — you can appeal within 14 days of the servicer’s written denial notice (12 CFR 1024.41(h)).
- If a sale is imminent, weigh bankruptcy. Filing triggers an automatic stay that stops the sale the moment you file — not days later (11 U.S.C. § 362). NACBA can connect you with a bankruptcy attorney, or talk to Damon Day for free first.
How to Actually Stop It — Your Real Paths
- Bankruptcy (the fastest emergency brake). A Chapter 13 case stops the foreclosure instantly through the automatic stay and lets you cure your past-due balance over a court-approved plan — at least three years for below-median-income filers, at least five years for above-median filers, with five years the maximum either way (11 U.S.C. § 1325(b)(4), § 1322(d)). One critical caveat: the instant stay only applies in full if this is your first bankruptcy in the past year. If you had one case dismissed in the last 12 months, the stay lasts only 30 days (11 U.S.C. § 362(c)(3)); with two or more dismissals in the past year, no stay takes effect at all unless a court orders it (§ 362(c)(4)). Tell your attorney immediately if you’ve filed before. Federal Reserve research shows filers recover faster than those who don’t.
- Reinstatement. Pay the past-due amount (missed payments plus fees) to bring the loan current before the deadline. This stops the foreclosure without changing your loan terms.
- Loan modification, forbearance, or repayment plan. Change the terms, pause payments, or spread the arrears out. This is what the loss-mitigation application above is asking for. If your loan is FHA-insured, VA-guaranteed, or USDA-backed, ask your servicer specifically about those programs — they have their own loss-mitigation options beyond Regulation X, including the new VA Partial Claim Program for veterans.
- Redemption. Pay the full loan balance to keep or recover the home. Important: many states have no post-sale redemption period at all, and where one exists it can be as short as a few months — do not assume you’ll have time to recover the home after the sale. Check your state’s law immediately.
- If you can’t keep the home, control the exit. A short sale (selling for less than you owe, with lender approval) or a deed in lieu of foreclosure (voluntarily signing the home back to the lender) is far less damaging to your credit than letting the foreclosure complete, and in many states can help you avoid a deficiency judgment. Your HUD counselor can help you weigh these.
- What usually WON’T save the house: a debt-settlement program (and if you’ve been paying into one with no results, you have legal rights including getting your money back), a new high-interest “rescue” loan, or any company demanding money upfront. Those address the wrong problem — or are a scam.
What You Need to Know About Your Rights
These federal loss-mitigation protections under Regulation X (12 CFR 1024.41) apply to most mortgage servicers — but some small servicers (generally those servicing 5,000 or fewer loans they own or originated) are exempt from much of it. Important nuance: even a small servicer still cannot start foreclosure until you’re more than 120 days delinquent. What they’re not required to give you is the full loss-mitigation evaluation, the 37-day dual-tracking protection, and the 14-day appeal right. If your loan is with a small community bank or credit union, ask which rules apply to you.
| Term | What it means | When it helps |
|---|---|---|
| Reinstatement | Pay the past-due arrears + fees to bring the loan current | You can catch up the missed amount before the deadline |
| Redemption | Pay the full balance to keep/recover the home | Limited — and many states allow none after the sale |
| Loan modification | Permanently change the loan terms | Your hardship is ongoing and you need a lower payment |
| Chapter 13 bankruptcy | Automatic stay stops the sale; cure arrears over 3–5 yrs | A sale is imminent or you need time to catch up |
If your servicer started foreclosure while your complete application was pending, denied you without explanation, or charged junk fees, file a complaint with the CFPB and your state attorney general. For faster, servicer-facing action, you can also submit a written Notice of Error under 12 CFR 1024.35 — the servicer must acknowledge it within 5 days and respond within 30–45 days. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov. And beware foreclosure-rescue scams: under the federal MARS Rule (Regulation O, 12 CFR Part 1015), no company may collect a fee until you have received and accepted a written offer of relief from your lender — signed and agreed to, not merely presented. Anyone asking for money upfront is breaking that rule.
One thing many homeowners miss: if your home sells at foreclosure for more than you owe, the surplus generally belongs to you — claim it promptly through the court or county. Scammers target people owed surplus funds, so verify anyone who contacts you offering to recover it.
Steve’s Take
I lost my own home after my business collapsed in 1990, so I know the specific terror of a sale date on a calendar. Here’s what I learned: the people who did best were the ones who opened the mail and made the calls early, while they still had every option. Foreclosure is not a character verdict — it’s a math problem with legal deadlines, and deadlines can be worked. I’ve watched thousands of people get to the other side of this. The ones who acted fast kept the most choices. The ones who froze lost them one by one. Don’t freeze.
If a hospitalization is what put you behind on the mortgage, see the complete guide to debts that piled up during a hospital stay for the full call order and deadlines.
Frequently Asked Questions
I’m facing foreclosure — can I really still stop it?
Yes, in most cases, especially if you act before the sale. Submitting a complete loss-mitigation application more than 37 days before a scheduled sale generally bars your servicer from selling until it evaluates you (12 CFR 1024.41(g)), reinstatement lets you catch up the past-due amount, and filing bankruptcy stops a sale immediately. The earlier you move, the more of these options remain open.
I have a sale date next week — how fast does bankruptcy stop it?
Immediately. The automatic stay under 11 U.S.C. § 362 takes effect the moment your case is filed and halts a foreclosure sale — even one scheduled for that same day. A Chapter 13 case then lets you cure the missed payments over a 3-to-5-year plan. (If you’ve filed bankruptcy before within the past year, the stay may be limited or absent — tell your attorney.)
What’s the difference between reinstatement and redemption?
Reinstatement means paying only the past-due amount — missed payments plus fees — to bring the loan current before a deadline. Redemption means paying the entire loan balance to keep or recover the home. Redemption is far more expensive, and many states provide no right to redeem after the sale at all, so never assume you’ll have time once the home is sold.
A company says it can save my house for an upfront fee — is that legit?
No. Under the federal MARS Rule (Regulation O, 12 CFR Part 1015), it is illegal for a mortgage-relief company to collect any fee until you have received and accepted a written offer of relief from your lender — signed and agreed to, not merely presented. Legitimate help — a HUD-approved housing counselor — is free. Anyone demanding money upfront is a red flag.
Do these federal protections apply to every mortgage?
They apply to most, but not all. The loss-mitigation timing rules under Regulation X exempt small servicers — generally those servicing 5,000 or fewer loans they own or originated. If your loan is with a small bank or credit union, ask whether the 120-day rule and dual-tracking protections apply, and lean on a HUD counselor for help.
Should I just move out to avoid the embarrassment?
No. You generally have the legal right to stay in the home until the foreclosure process is complete. Vacating early can also let the servicer treat the home as “abandoned” under federal servicing rules (12 CFR 1024.41(f)), which can strip away certain procedural protections — and leaving does not stop a deficiency judgment. Stay put, keep the home maintained, and work your options from inside it.
What happens to my credit if the foreclosure goes through?
A completed foreclosure stays on your credit report for seven years under the Fair Credit Reporting Act (15 U.S.C. § 1681c), but its weight fades over time. A short sale or deed in lieu is generally less damaging than a completed foreclosure. Many people’s scores begin recovering within two to three years, especially as new on-time payment history builds — and Federal Reserve research shows people who address the problem recover faster than those who delay.
One more thing — everything I share here is based on more than 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Foreclosure law varies significantly by state — especially timelines, judicial vs. non-judicial process, and redemption rights — and your situation may have details that change your options. For advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: Foreclosure is serious but not the end — it’s a process with deadlines you can work. Call a free HUD counselor this week, get a complete loss-mitigation application in, and know that bankruptcy can stop a sale instantly if you need it. For your state’s specific rules and the full set of options, see my complete guide: Facing Foreclosure? Your Options to Save Your Home or Walk Away. The longer you wait, the fewer options remain.
The Bottom Line
If there’s a foreclosure notice on your kitchen table right now, take a breath: a notice is the start of a process, not the end of your home. The law gives you real protections — a 120-day runway, the right to be evaluated for help, an appeal, and bankruptcy’s instant stop if you need it. I lost my home in 1990 and rebuilt everything, and I’ve watched thousands of people do the same. You are not your mortgage balance, and a hard season is not a life sentence. If someone you love is hiding foreclosure notices out of shame, send them this page — the call they’re afraid to make is the one that saves them the most. See the complete foreclosure guide or take the Find Your Path quiz to see your options.
If you’re on active duty, the SCRA gives you separate mortgage protections — including a 6% interest rate cap on a mortgage you had before you deployed — here’s how to invoke your Servicemembers Civil Relief Act rights.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 10): Your phone company is supposed to know who’s handing it those scam calls. Some of them don’t bother.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



