

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 23, 2026
Quick Answer: You just lost your income, and the bills haven’t stopped. Take a breath — you have more protection than you think. Unemployment benefits are protected from most private debt collectors in nearly every state. For the next month or two, pay for survival first — housing, utilities, food, transportation to job interviews — and let unsecured debts like credit cards wait. Call your creditors and ask for hardship programs before you miss a payment. Don’t drain your retirement or your emergency fund to keep a credit card current. Triage like your future depends on it, because it does.
If you also received a notice that you were overpaid unemployment benefits and the state wants the money back, that is a separate fight — and you have appeal rights there too.
What Just Happened to Your Income
Whether you were laid off, fired, or had your hours cut to nothing, the math just changed overnight. Your obligations — rent or mortgage, car payment, credit cards, utilities — were built around a paycheck that isn’t coming. The panic you’re feeling is your brain trying to solve all of it at once. You don’t have to. You have to solve the next 30 days first.
Here’s the part most people don’t realize in the first scary week: not all debts are equal, and not all of your money is up for grabs. The law protects certain income, and certain bills matter far more than others when cash is short. Knowing the difference is what keeps a temporary setback from becoming a permanent one.
The Mistake You’re About to Make: Reaching for your 401(k), your emergency fund, or a high-interest “tide-me-over” loan to keep your credit cards current. I’ve watched this destroy people. You’ll burn through protected retirement money — money creditors usually cannot touch — to pay an unsecured debt that could have waited. Then you’re still unemployed, your retirement is gone, and the credit card is right back where it was. Protect your cash and your retirement first. Read your options before you move a dollar.
Your Options Right Now
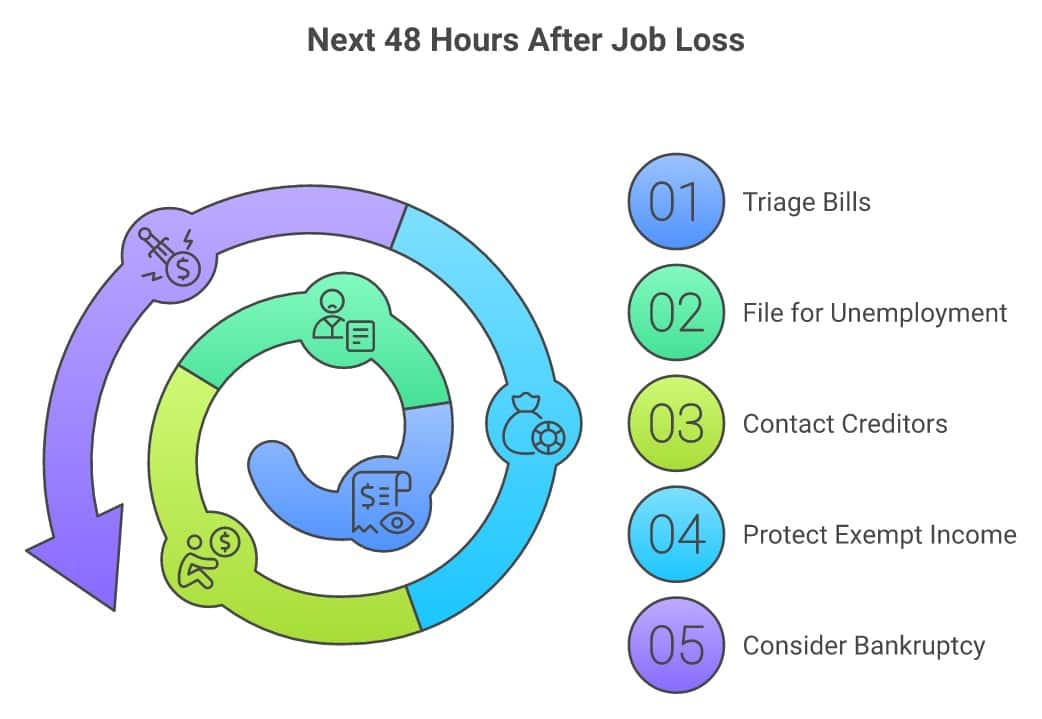
What to Do in the Next 48 Hours
- Triage your bills into “survival” and “everything else.” Survival = housing, utilities, food, and transportation to find work, plus any car you need to get to a job. Everything else (credit cards, medical bills, personal loans) goes to the bottom of the list — temporarily.
- File for unemployment benefits today if you haven’t. Don’t wait — benefits often start from the date you file, not the date you lost the job. And know this: in nearly every state, unemployment benefits are exempt from garnishment by ordinary creditors.
- Call your creditors and ask for hardship help before you miss a payment. Mortgage servicers, credit card issuers, and auto lenders all have hardship and forbearance programs. The word to use is “forbearance” or “hardship.” Asking before you default gives you far more leverage than asking after. Get any agreement in writing.
- Know your protected income. Unemployment benefits, Social Security, SSDI, SSI, and veterans’ benefits are generally protected from private creditors. The exceptions are government claims, not private ones: child support, federal taxes, your state unemployment office recovering an overpayment, and possibly defaulted federal student loans (check with an attorney). If an ordinary collector tells you they’ll take your unemployment check, that is usually not true — and may be illegal.
- If the debt is genuinely unpayable, look at bankruptcy early — not as a last resort. The moment you file, the automatic stay under 11 U.S.C. § 362 takes effect instantly — it stops most lawsuits, garnishments, and collection calls the same day, not weeks later. (One important exception: the stay does not stop child support or alimony collection — those continue regardless of a bankruptcy filing. And in practice, a garnishment already running may take a few days to actually halt while your attorney notifies the creditor and your employer.) Talk to a bankruptcy attorney through NACBA, take the 2-minute bankruptcy quiz, or talk to Damon Day for free before you make any move under panic.
How to Actually Stop the Bleeding — Your Paths Forward
- Pay for survival, defer the rest. Housing, utilities, food, and getting to job interviews come first. Missing a credit card payment hurts your credit score; missing rent or a car payment can cost you your home or your way to work. The order matters.
- Hardship and forbearance programs. Most lenders will pause or reduce payments for a hardship period — but you have to ask, and you have to get it in writing. A verbal “don’t worry about it” is worth nothing when the late notice arrives.
- Bankruptcy, if the hole is too deep. If your debt is genuinely beyond what you can repay even after you find work, Chapter 7 can wipe out unsecured debt, and the automatic stay stops collection instantly. Research from Federal Reserve economists shows people who file recover faster than those who keep struggling.
- What usually won’t work: A debt consolidation loan when you have no income (you won’t qualify, and if you do, you’ve just added a payment). A debt settlement program (it takes years and money you don’t have — and if you’re already enrolled and nothing has settled, you have rights including the right to get your money back). Cashing out your 401(k) (you lose protected money and trigger taxes and penalties — see why that’s almost always a mistake).
What You Need to Know About Your Protected Income
Unemployment, Social Security, SSDI, SSI, and VA benefits are protected from ordinary creditors in nearly every state.
Even for wages from a new job, the CCPA caps garnishment at 25% of disposable earnings — and protects 30× the federal minimum wage per week.
Child support, federal taxes, state benefit-overpayment recovery, and possibly defaulted federal student loans can reach income that private creditors cannot.
The federal Consumer Credit Protection Act (CCPA) limits how much of any future paycheck a creditor can garnish — generally no more than 25% of your disposable earnings, and it fully protects the equivalent of 30 times the federal minimum wage each week (see 15 U.S.C. § 1673). And right now, while you’re between jobs, your unemployment and other benefit income is protected even further.
One important caveat about Social Security and SSDI: they’re protected from private creditors, but the government can still reach them — the IRS can offset up to 15% for back taxes, and defaulted federal student loans can be collected through the Treasury Offset Program. SSI carries stronger protection and generally can’t be taken even for government debts. And these federal-benefit protections apply automatically only when the money arrives by direct deposit — if you get a paper check and deposit it yourself, you may have to assert the exemption manually.
| Income Type | Protected From Private Creditors? | Notes |
|---|---|---|
| Unemployment benefits | Yes, from private creditors (nearly all states) | Government exceptions: child support, federal taxes, state overpayment recovery, possibly defaulted federal student loans |
| Social Security / SSDI / SSI | Yes (federally protected) | Keep in a separate account so the protection is clear |
| Veterans’ benefits | Yes (federally protected) | Generally exempt from creditor garnishment |
| Wages from a new job | Partly | CCPA caps garnishment at 25%; protects 30× minimum wage/week |
If you live in a state with stronger protections — several states (like Texas, Pennsylvania, North Carolina, and South Carolina) prohibit or heavily restrict wage garnishment for most consumer debts entirely. Check your state’s rules, because your paycheck from your next job may be more protected than you think. One catch worth knowing: that protection applies at the employer level — once wages land in your bank account, a creditor who has won a judgment may still be able to levy the account. Don’t let large balances sit exposed.
If a debt collector is threatening to garnish your unemployment check, lying about your rights, or harassing you, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, so I know what it feels like to look at bills you can’t pay. Losing a job isn’t a character flaw — it’s something that happens to good, hard-working people, and the panic that comes with it makes everyone reach for the wrong lever. In 30 years I’ve watched too many people empty a retirement account to keep a credit card current, then end up filing bankruptcy anyway — just poorer. Protect your survival money and your retirement first. The credit card can wait. You can rebuild a credit score in a couple of years; you can’t easily rebuild a drained 401(k). Move calmly, protect what’s protected, and ask for help early.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Frequently Asked Questions
I just lost my job — which bills should I pay first?
Pay for survival first: housing, utilities, food, and transportation to job interviews, plus a car you need to get to work. Credit cards, medical bills, and personal loans go to the bottom of the list temporarily. Missing a credit card payment hurts your credit; missing rent or a car payment can cost you your home or your way to work.
Can a debt collector take my unemployment check?
Usually no. In nearly every state, unemployment benefits are exempt from garnishment by ordinary creditors. The exceptions are government claims: child support, federal taxes, your state unemployment office recovering an overpayment, and possibly defaulted federal student loans. If a private collector claims they’ll seize your unemployment, they’re usually wrong — and may be breaking the law.
Should I use my 401(k) or emergency fund to pay my credit cards?
Almost never. Retirement money is generally protected from creditors, and cashing it out triggers taxes and penalties. You’d be spending protected money to pay an unsecured debt that could have waited. Keep at least a three-month cushion. See why cashing out your 401(k) is almost always wrong.
Free Tool — Judgment Proof Checker: Think creditors can take everything? Many people in financial hardship are legally protected. The free Judgment Proof Checker shows whether collectors can actually collect anything from you in your state. Check My Status →
I filed bankruptcy — how fast does it stop collection?
Immediately, for most debts. The automatic stay under 11 U.S.C. § 362 takes effect the moment your petition is filed and stops most lawsuits, wage garnishments, and collection calls the same day. It does not stop child support or alimony collection, and a garnishment already in motion can take a few days to actually halt while your attorney notifies the creditor and employer.
Should I call my creditors before or after I miss a payment?
Before. Call as soon as you know you’ll have trouble paying, and ask for a hardship or forbearance program. Lenders have far more flexibility when you reach out proactively than after you’ve defaulted. Get any agreement in writing.
Will a debt consolidation loan help me while I’m unemployed?
Probably not. With no income, you likely won’t qualify — and if you do, you’ve just added a monthly payment you can’t make. Consolidation moves debt around; it doesn’t reduce it. Focus on protecting survival cash and talk to a bankruptcy attorney if the debt is truly unpayable.
Can losing my job lead to bankruptcy, and is that bad?
It can, and it isn’t the disaster people fear. Bankruptcy is a legal protection that exists for exactly this — an income shock you didn’t choose. Research from Federal Reserve economists shows filers recover faster than those who keep struggling. Credit scores often rise after filing, and your retirement is protected.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: Losing your job is a cash-flow crisis, not a character failure — and it’s survivable. Protect your survival money and your retirement, pay for housing and food before credit cards, and ask for hardship help early. See all your debt relief options, and the sooner you act, the more options you keep.
The Bottom Line
You are not bad with money because you lost your income — almost nobody has a cushion deep enough for a sudden job loss, and that’s a failure of how thin most household budgets have to run, not of you. The law built in protections for exactly this moment: exempt income, garnishment caps, hardship programs, and a fresh start if you need one. The people who come through this best are the ones who triage calmly and ask for help early instead of draining everything to keep up appearances. If someone you know just lost their job and is panicking about their bills, send them this page — it might be the thing that stops them from making the one move they can’t undo. Start with the Find Your Path quiz to see what fits your situation.
Layoffs hit even high earners — when Microsoft cut thousands of Xbox jobs, the same first-week rules applied. Here’s the first-week money playbook for a tech layoff, including stock options and severance timing.
If job loss has put your utilities at risk of disconnection, the utility shutoff crisis guide covers LIHEAP emergency grants, medical-necessity protections, and how to stop a shutoff in the next 48 hours.
Related: what to do if the state says you were overpaid unemployment.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
If you’re leaning on a cash-advance app to bridge the gap, read first why earned-wage-access apps are payday loans in a costume — they can deepen the hole, not bridge it.
Losing a job right now isn’t bad luck in a strong market — it’s happening while the unemployment rate is falling for the worst possible reason: hundreds of thousands of people have stopped looking for work altogether. Knowing that can help you plan for a longer search, not a quick one.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



