

Here’s something I want you to know before you ever Google the name of a company that’s collecting on a debt: the phone number at the top of your search results may not belong to the collector at all. People have told the federal government, in their own words, that they searched for their debt collector, called the first number they saw, and found they were on the phone with a credit repair company instead. The name that comes up in those complaints is Credit Sage (and a company under the same CEO, Credit Glory).
I’m Steve Rhode. For more than 30 years — since 1994 — I’ve helped people understand how the debt-relief industry really works, and this is a pattern worth understanding so it doesn’t catch you off guard.
The one-sentence version: If you search for a debt collector’s name and call a number from an ad or a look-alike page, confirm who actually answered before you give out a single piece of personal information. Ask directly: “Are you [the collector I searched for], yes or no?”
Let me be clear up front about what this is and isn’t. Everything below comes from public records — complaints consumers filed with the Consumer Financial Protection Bureau and the Better Business Bureau, and court and corporate filings anyone can pull. I’m reporting what’s in those records. I am not saying any of these companies has been found by a court or a regulator to have broken the law, and as far as I can find, no government agency has made any such finding. I’ll tell you exactly where the record is solid and exactly where it stops.
What people told the government
These are real complaints, filed by real people, in the CFPB’s public complaint database. Among consumer complaints naming Credit Sage, the most common issues consumers chose were “charged upfront or unexpected fees,” “didn’t provide services promised,” and “confusing or misleading advertising or marketing.” Here is what some of them described, in their own words (the bracketed names are redacted by the database):
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
- A consumer wrote that while “looking up the phone number for [a collector], I was directed to Credit Sage. While speaking to Credit Sage, I was under the impression I was speaking to [the collector]…” (CFPB complaint #8274947)
- Another: “I called Credit Sage to get my debt settled. The representative told me that he would get it settled. I paid $200 to have this done. I called the collection agency to see if my debt had been paid off and they told me no…” (CFPB complaint #12647335)
- At the Better Business Bureau, a consumer described calling LVNV Funding to pay off a debt and being “rerouted to Credit Glory,” and not realizing until later in the conversation that the person was not from LVNV.
I want to be fair about what these are: they’re consumer complaints, which means they are one side of a story, unproven, and not a court’s finding. But they are numerous, they’re hosted by a federal agency, and they describe the same experience again and again — a person looking for their collector who found they were on the phone with a credit repair company.
The same pattern shows up on other platforms too. On Trustpilot, a customer wrote in a recent review that they were quoted a $24.99 monthly fee but then saw Credit Sage attempt to charge $99 “without my knowledge or authorization,” and that they paid $1,215 the same day on a promise that a collection would be removed — which didn’t happen, and the refund was refused. That mirrors what people described to the CFPB almost word for word. I’ll be straight about Trustpilot, though: Credit Sage and Credit Glory both carry high overall Trustpilot scores, but those are paid Trustpilot subscriptions, Trustpilot itself notes the companies have “no history of asking for reviews” so the ratings “may not be representative,” and neither replies to negative reviews. So I’m not pointing you at the star rating — I’m pointing you at the specific complaints that match the government record, which you can read for yourself.
Why this matters: Credit repair is a legal, regulated service. But the federal Credit Repair Organizations Act exists precisely because this corner of the industry has a history of problems — it generally forbids charging you before the work is done and requires a written contract and a three-day right to cancel. (It’s also the same corner of the industry that sells myths like the “609 letter” that supposedly erases any debt — it doesn’t.) If you think you’re talking to your collector and you’re actually talking to a credit repair salesperson, you can’t make an informed choice. That’s the whole risk.
What’s on the pages
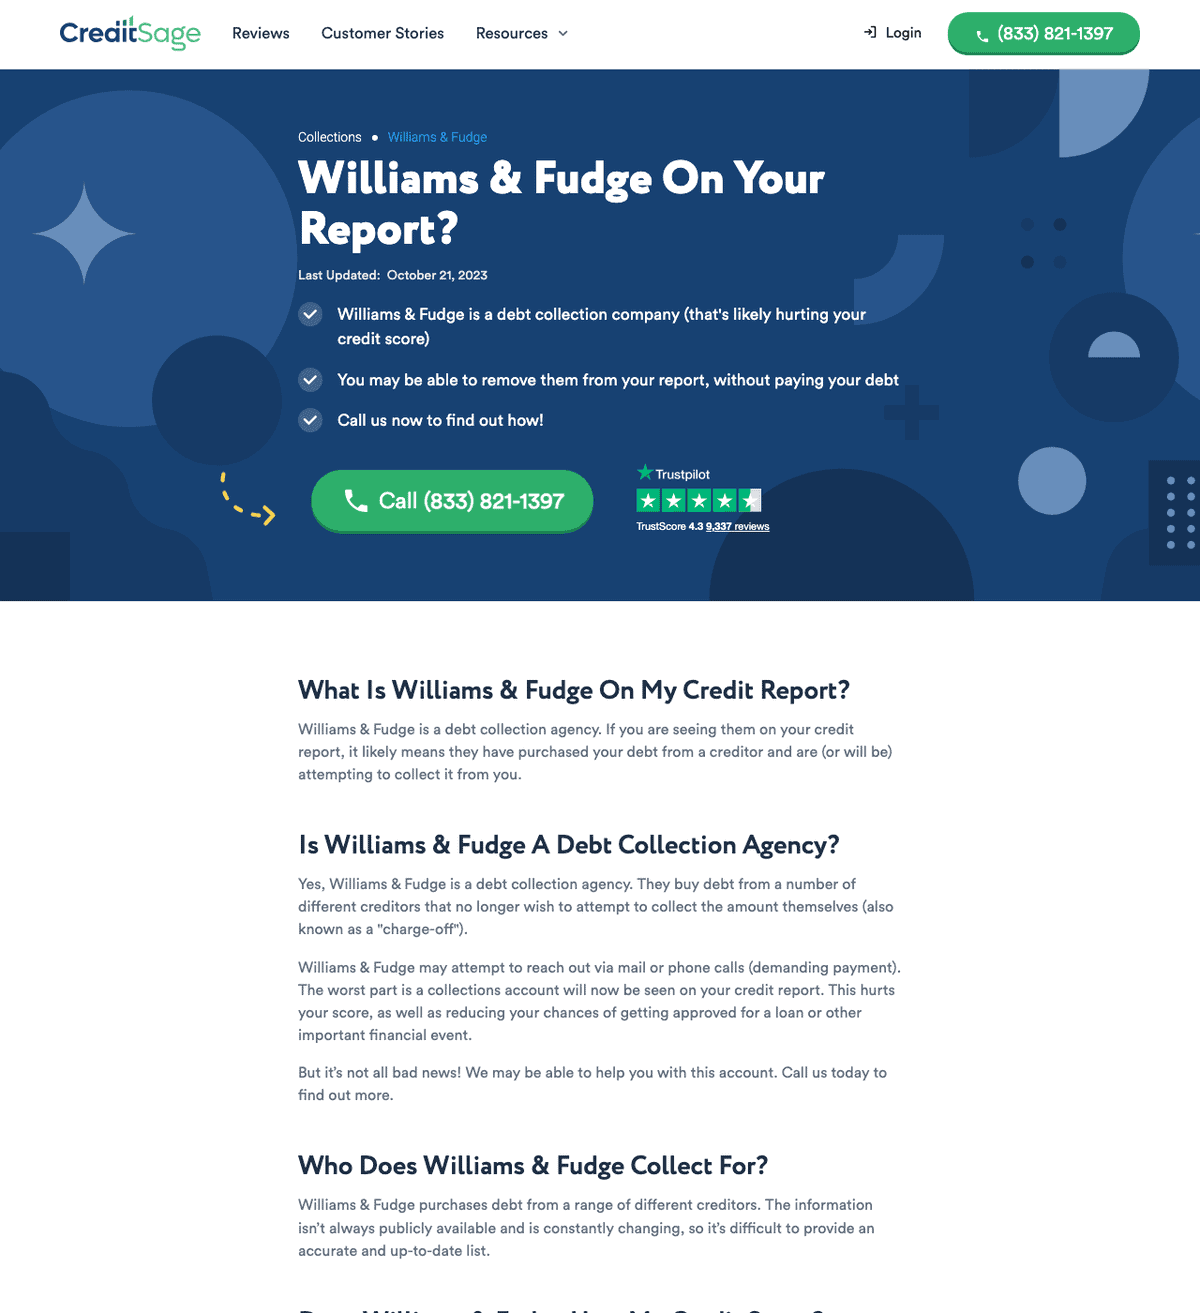
Here’s what I could confirm directly, and I saved a snapshot of each page to the Internet Archive on the day I looked, so you can see exactly what it said. Credit Sage and Credit Glory both publish web pages built around the names of specific collection agencies — for example, pages about removing “Williams & Fudge” or “Midland Credit Management” from your credit report, each showing a “call now” phone number.
In fairness to the companies: those pages identify themselves as Credit Sage or Credit Glory. They are not fake websites pretending to be a collector — a person who reads carefully would see the company’s real name.
One piece of context: Google has prohibited credit repair advertising since November 2019.


A pattern I found across other sites
The document I received also pointed to a set of other websites that follow the same pattern — pages built around the names of collection agencies, each ending in a “call now” number. I went and looked at the live sites myself. I want to be careful here about what I am and am not telling you.
What I can confirm: these sites are live, and they follow the same look-alike-the-collector pattern. Here are several of them, with an archived snapshot of each as it appeared the day I reviewed it:
collection-removal.com(archived)collections-dispute.com(archived)collections-expert.org(archived)collections-review.com(archived)collections-specialist.com(archived)review-collections.com(archived)
What I cannot confirm: who owns them. Like a great many websites today, these domains hide their registration behind WHOIS privacy services — the public records simply say “redacted for privacy.” So I am not telling you who runs these sites, because honestly, I can’t see it, and I won’t guess.
One similarity I did notice, and I’ll share it as nothing more than that — a similarity I discovered, not a conclusion I’m drawing: when I looked at the page code on the six sites listed above, each one carried the same Google Ads conversion-tracking ID (AW-11291188616). You can check this yourself by viewing the page source on any of them. I’m not going to tell you what it means. I’m just telling you what I found, and leaving the conclusion to you.
Please do your own research here too. I’d rather hand you what I can verify and let you weigh it than tell you what to think.
What the record does — and does not — show
- I could find no government enforcement action against Credit Sage or Credit Glory — no FTC case, no CFPB action, no state attorney-general judgment. What exists is a body of consumer complaints. Complaints are allegations, not findings. I’m telling you that plainly.
- There is one federal court judgment against Credit Sage — Hunsley v. Credit Sage, under the Credit Repair Organizations Act — but it was a default judgment. A default judgment is entered when the defendant doesn’t show up to contest the case; the court does not weigh both sides or hold a trial. It establishes liability on the filing, and that’s all. It is not a court finding, after hearing evidence, that the company committed fraud.
- Some lawsuits get cited in this context that actually have Credit Sage or Credit Glory as the plaintiff — the company suing someone else. Those say nothing about wrongdoing by the company, and I won’t present them as if they do.
- Credit Sage and Credit Glory are commonly controlled — a 2024 press release named Marko Petkovic as CEO of both. Beyond that confirmed connection, I’ve seen claims of a wider web of related companies that I could not independently verify, so I’m leaving those out.
- Large “consumers harmed” and “revenue” figures circulate in connection with this. They’re estimates, with no primary source behind them, so I’m not repeating them as fact.
I’d rather give you a smaller set of things that are solid than a bigger set that’s shaky. The solid part is enough to act on: people searching for their collector have reported, to the government, ending up on the phone with a credit repair company.

Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
How to protect yourself in 30 seconds
- Don’t trust the first number. Get your collector’s phone number from your written collection notice or the collector’s own verified website — not from an ad or a third-party page.
- Ask the direct question. The moment a call connects: “What company am I speaking with?” and “Are you [the collector], yes or no?” A legitimate business will answer plainly.
- Give nothing until you’re sure. No Social Security number, no date of birth, no card number, no photo of your ID — not until you’ve confirmed who you’re talking to.
- Know the law is on your side. A credit repair company generally cannot charge you before it does the work, and it must give you a written contract and a three-day right to cancel. If someone wants money up front to “remove” a collection, treat that as a red flag.
- You usually don’t need to pay anyone. You can dispute genuine credit report errors yourself, for free, directly with the credit bureaus.
These are the facts I was able to confirm from public records, and I’ve linked every one of them above so you don’t have to take my word for it. Please do your own research and come to your own conclusion. And as always, I welcome a statement from any company named in this post — Credit Sage, Credit Glory, or anyone else — through my contact form, and I’ll add it here.
My honest take
I’m not here to sling mud, and I sell nothing, so I have no dog in this fight except yours. The thing that bothers me isn’t that a credit repair company exists — it’s that a person in a stressful moment, trying to do the responsible thing and deal with a debt, could end up paying a stranger they never meant to call. You deserve to know who’s on the other end of the line before you trust them with your money and your identity.
My advice is input — only you decide what to do with your money. But if you take one thing from this: confirm who answered before you say anything else. That single question protects you.
If this could help someone you know who’s dealing with collectors right now, please send it to them. It’s the kind of thing nobody warns you about until after it’s already happened.
Before You Sign Anything: Run any debt relief contract through the free Contract Decoder to spot hidden fees and unfair terms. Check the company’s complaint history with the Scam-O-Meter.
Compare Your Real Options: Most debt relief companies won’t tell you about all your options — especially the ones they can’t profit from. Credit counseling has a 21-27% completion rate. Settlement resolves about 1% of enrolled debts fully. Bankruptcy has a 95% discharge rate — and protects your retirement. Take the Find Your Path quiz for a recommendation based on your actual numbers.
Sources I reviewed
Each company-controlled page links to an Internet Archive snapshot taken the day I reviewed it, so you can see exactly what it said even if the page later changes.
- CFPB consumer complaint database — search “Credit Sage” (primary government source; archived 2026-06-25): live
- CFPB consumer complaint database — search “Credit Glory” (archived 2026-06-25): live
- Google advertising policy — credit repair prohibited (archived 2026-06-25): snapshot
- Credit Sage — Williams & Fudge collection page (archived 2026-06-25): snapshot
- Credit Glory — homepage (archived 2026-06-25): snapshot
- Press release naming Marko Petkovic CEO of both Credit Glory & Credit Sage, 2024 (archived 2026-06-25): snapshot
- BBB profile — Credit Sage (archived): snapshot
- Credit Sage LLC v. Credit Wellness LLC docket — note: Credit Sage is the plaintiff here (archived): snapshot



