

Written by Steve Rhode, consumer debt expert since 1994 • Last updated June 29, 2026
Quick Answer: If your only income is Social Security, SSI, SSDI, VA benefits, or a federal pension, that money is protected by federal law from private debt collectors — even if they sue you and win. That’s what “judgment-proof” means: they can get a judgment, but they can’t legally collect. Your fastest protection is to make sure your benefits arrive by direct deposit, which triggers an automatic bank shield. Collectors can still call — but you have the right to make them stop in writing, and they cannot touch protected income. Don’t pay a collector out of fear when the law already protects you. And being judgment-proof does not stop a creditor from getting a writ of execution and sending a sheriff to your door — it just means most of what they find is exempt. If that happens, claim your exemptions on time; the protection is real but it is not automatic.
What Just Happened — And What “Judgment-Proof” Really Means
Yes — if your income is Social Security, SSI, SSDI, or VA benefits, federal law already protects it from private debt collectors, even after a court judgment. Here’s the situation a lot of people on fixed incomes find themselves in: a debt collector keeps calling, maybe they’ve even sued you and won a judgment — and yet they still can’t actually take anything from you. That’s not luck. It’s federal law.
You’re “judgment-proof” (lawyers call it “collection-proof”) when all of your income and assets are the kind a creditor legally cannot reach. A collector can still win a lawsuit on paper. But a judgment is just permission to try to collect — and if everything you have is federally protected, there’s nothing for them to collect. The judgment sits there, unenforceable against your protected income. Some creditors respond by ordering you to a debtor’s examination to make you prove it under oath — here’s what to expect and how to handle being called into court to answer questions about your money.
The Mistake You’re About to Make: Paying a collector out of money you can’t spare — or worse, draining a protected Social Security account — because the calls scared you into thinking you have no choice. If your income is exempt, that collector cannot legally take it no matter how many times they call. Before you hand over a dollar, confirm whether you’re judgment-proof. Many people pay debts they were never at risk of losing anything over.
Your Options Right Now
What to Do in the Next 48 Hours
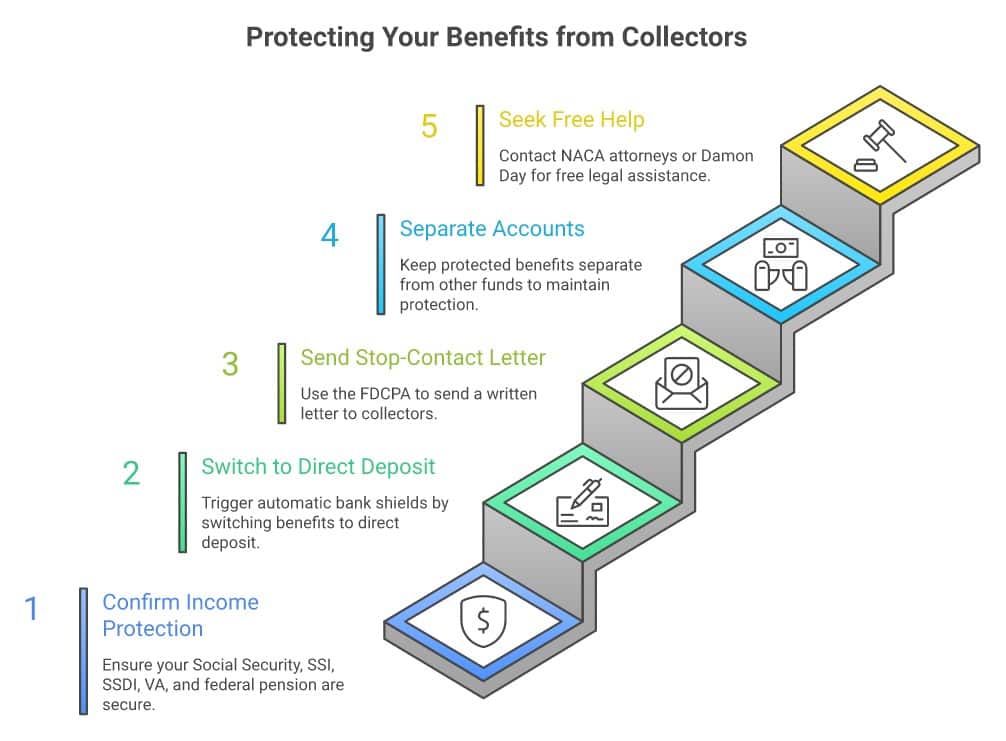
- Confirm your income is protected. Federally protected income includes Social Security, SSI, SSDI, veterans’ benefits, federal civil-service and railroad retirement, and federal student aid. The CFPB confirms these are exempt from private debt collectors.
- Switch every benefit to direct deposit. This is the single most important step. When benefits land in your account by direct deposit, federal rule 31 CFR Part 212 forces your bank to automatically protect up to two months’ worth of benefits from any garnishment order — without you having to do anything. Benefits cashed as a paper check and deposited by hand do NOT get this automatic shield.
- Send the collector a written “stop contact” letter. Under the Fair Debt Collection Practices Act, once you tell a collector in writing to stop contacting you, they must — with only narrow exceptions. Keep a copy and send it so you have proof of delivery. Important: this right applies only to third-party debt collectors — collection agencies and debt buyers. If the original bank or credit card company is calling you directly, the FDCPA does not bind them, though your state may offer added protection.
- Don’t mix protected and unprotected money. If you deposit non-exempt cash (like wages from a part-time job) into the same account as your benefits, you can muddy the automatic protection. Keep protected benefits in their own account where possible.
- If you’re being harassed or sued, get free help. NACA can connect you with a consumer attorney, and many will review a collector’s conduct for free. Or talk to Damon Day for free about whether you’re judgment-proof and what to do next.
How to Actually Make It Stop — Your Paths Forward
- Assert your exemptions and let the judgment die on the vine. If all your income is protected, a collector with a judgment still gets nothing. Many judgments eventually expire if never collected, though the timeline varies by state and some can be renewed. Being judgment-proof can be a complete, if uncomfortable, answer on its own.
- Bankruptcy — if the calls and stress aren’t worth it. Even people who are judgment-proof sometimes file bankruptcy simply to make the whole thing stop and get a clean slate. The automatic stay takes effect the moment you file — not weeks later. Every collection call, lawsuit, and garnishment attempt must halt immediately. Federal Reserve research shows people who file recover faster than those who don’t. Find a bankruptcy attorney through NACBA, or for seniors and disabled people living on protected benefits, HELPS is a nonprofit law firm built for exactly this situation.
- Negotiate from strength — carefully. If you have a small amount of non-exempt money and want the debt gone, you can sometimes settle for far less than owed because the collector knows you’re hard to collect from. Get any agreement in writing before you pay a cent.
- What WON’T help: A debt settlement company. They charge fees to “negotiate” debts you may already be protected from — and they can’t change your judgment-proof status. Don’t pay someone to solve a problem federal law may have already solved for you.
What You Need to Know About Your Protected Income
of direct-deposited benefits your bank must automatically protect from garnishment
that private credit-card or medical-debt collectors can take from exempt Social Security
is what triggers the automatic shield — paper checks deposited by hand do not
Federal law protects Social Security, SSI, SSDI, VA benefits, and federal retirement from private creditors. The protected-account rule is 31 CFR Part 212; the broader benefit protection comes from 42 U.S.C. § 407 (Social Security) and 38 U.S.C. § 5301 (veterans’ benefits). But the protection is not absolute — here’s who can still reach your benefits and who can’t.
| Type of Debt | Can it reach your Social Security / SSDI? | Notes |
|---|---|---|
| Credit card, medical, personal loans (private debt) | No | Fully exempt — this is most collectors |
| Federal back taxes (IRS) | Yes, up to 15% | The IRS can levy up to 15% per month through the Federal Payment Levy Program — with no protected floor for tax debts (it can take 15% even if that drops your benefit below $750). The $750 floor only protects against NON-tax government debts. SSI is fully exempt. |
| Federal student loans | Yes, within limits | Can offset benefits after default — but see the June 2026 update below |
| Child support / alimony | Yes, capped 50–65% | Family-support orders can reach SS/SSDI but are capped at 50–65% of benefits. SSI is exempt. |
| Any debt vs. SSI specifically | No | SSI is protected even from the government exceptions above |
June 2026 update on defaulted student loans: The U.S. Department of Education paused all involuntary collections — including Social Security offsets and wage garnishment — on January 16, 2026, with a restart targeted for around July 2026 as new repayment options launch. If you have defaulted federal student loans, contact your servicer now about rehabilitation or an income-driven repayment plan before collections resume. The pause is temporary and doesn’t erase the default.
The takeaway: if your debt is an ordinary private debt — a credit card, a medical bill, an old loan in collections — your Social Security and similar federal benefits are off-limits to that collector. The exceptions are the government and family-support debts in the table above.
If a collector is still trying to garnish protected income, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, so I know how it feels when the phone won’t stop ringing. But here’s what I want you to hear: if you’re living on Social Security or disability, the law already built a wall around your money. The collectors calling you know it too — they’re hoping you don’t. I’ve watched too many people on fixed incomes scrape together payments out of fear, money they needed for food and medicine, on debts that could never have touched them. Find out where you stand before you pay anyone a dime. Being judgment-proof isn’t a loophole. It’s the protection your country deliberately gave you.
Filed bankruptcy and got a discharge, but a creditor is still calling on a debt that was included in your case? That’s a discharge injunction violation, not just judgment-proof status — see A Creditor Won’t Stop Collecting After My Bankruptcy Discharge. Here’s What to Do Right Now..
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Frequently Asked Questions
I’m judgment-proof but the collector won’t stop calling — can I make them stop?
Yes. Under the Fair Debt Collection Practices Act (15 U.S.C. § 1692c), once you send a written request to stop contact, the collector must stop, with only narrow exceptions like notifying you of a specific legal action. Send it in writing and keep proof.
Can a debt collector take my Social Security if they won a judgment against me?
For ordinary private debts — credit cards, medical bills, personal loans — no. 42 U.S.C. § 407 exempts Social Security from private creditors even after a judgment. The exceptions are federal taxes, federal student loans, and child or spousal support.
What does “judgment-proof” actually mean?
It means that even if a creditor sues you and wins, they can’t legally collect because all of your income and assets are exempt under federal or state law. The judgment exists, but it’s unenforceable against your protected income.
How do I protect my benefits in my bank account?
Use direct deposit. Under 31 CFR Part 212, when a garnishment order hits your account, your bank must automatically protect up to two months’ worth of direct-deposited federal benefits. Benefits received as a paper check and deposited manually do not get this automatic protection.
I filed bankruptcy — how fast does it stop the collection calls?
Immediately. The automatic stay under 11 U.S.C. § 362 takes effect the moment your case is filed. Every call, lawsuit, and garnishment attempt must stop at once — not weeks later.
If I’m judgment-proof, do I even need to do anything?
Sometimes the protection works on its own — the collector gets a judgment they can never enforce. But you should still switch to direct deposit, avoid mixing protected and unprotected money, and send a written stop-contact request if the calls are wearing you down. Staying judgment-proof is partly about not accidentally exposing protected money.
Can a debt settlement company help if I’m judgment-proof?
No. A settlement company can’t change your judgment-proof status, and they charge fees to negotiate debts you may already be protected from. Don’t pay someone to solve a problem federal law may have already solved for you.
Can a debt collector garnish my Social Security check?
Not for ordinary private debts. Social Security is exempt from private creditors under 42 U.S.C. § 407, even after a judgment. It can be reached only for federal taxes, federal student loans, and child or spousal support — and SSI is protected even from those.
Can a collection agency freeze my bank account if I get Social Security by direct deposit?
Your bank must automatically protect up to two months of direct-deposited federal benefits under 31 CFR Part 212. If your account is frozen and holds only direct-deposited benefits, call your bank immediately and ask them to review it under that rule. If they refuse, file a complaint with the CFPB.
Am I judgment-proof forever, or can that change?
It can change. If you take a job with garnishable wages, inherit money, or build up non-exempt savings, you may no longer be judgment-proof. And some judgments can be renewed by the creditor, so the debt itself may not simply vanish even while it’s uncollectable today.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Related: If collectors are trying to enforce a judgment you never knew about, you may also have grounds to challenge the judgment itself. See: A Default Judgment Was Entered Against Me. Here’s What to Do Right Now.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
Key Takeaway: If you live on Social Security, disability, VA benefits, or a federal pension, the law already shields your income from private debt collectors — even after a judgment. Switch to direct deposit, send a written stop-contact request, and don’t pay out of fear. Check the full picture of your options before deciding anything. The collectors are counting on you not knowing your rights.
Being judgment-proof protects you from ordinary creditor garnishments, but not necessarily from a support order or a tax levy stacked on top. See my guide on multiple wage garnishments at the same time if more than one order shows up.
The Bottom Line
Being judgment-proof doesn’t mean you failed — it means the system built protections for people living on fixed incomes, and those protections are working exactly as intended. The people who learn their rights stop paying out of fear and start keeping the money they need to live. If someone you know is on Social Security and being hounded by collectors, send them this page — they may be protected and not even know it. See the Find Your Path quiz for a recommendation based on your actual situation.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.

