

Quick Answer: The Fed just held rates at 3.50%–3.75% again — and on July 1, 2026, new Fed Chair Kevin Warsh said inflation is “too high” and declined to signal a July cut. More important: the Fed’s own June dot plot flipped to show the median policymaker now expects rates to end 2026 higher than today, with 17 of 18 officials seeing inflation risk on the upside. Millions of people are waiting for a rate-cut rescue that the Fed’s own projections say could go the other direction — a hike. If you have variable-rate debt or high-APR credit cards, waiting is a plan based on a hope the data doesn’t support.
Expert Context: I’ve been watching the Federal Reserve’s relationship with consumer debt since the early 1990s — including through the cycle that preceded my own bankruptcy in 1990. I’ve seen people delay hard decisions because they were counting on cheaper rates to bail them out. Sometimes it worked. More often, the wait turned a manageable problem into a crisis. The June 2026 dot plot is the clearest signal I’ve seen in years that the Fed is not coming to the rescue on the timeline most debtors are hoping for.
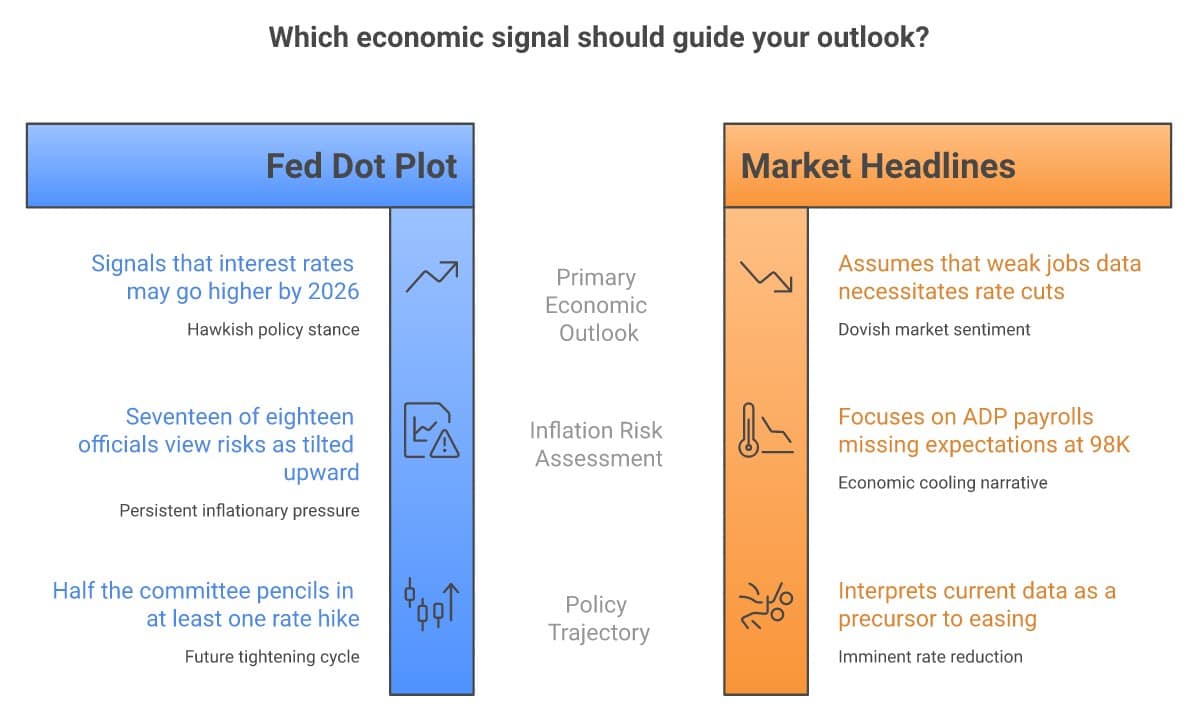
The crowd heard “weak jobs” on July 1 and assumed rate cuts are coming. The Fed just told you the opposite may be true — and if you’re carrying high-rate variable debt, you need to hear the version of this story the headlines buried.
What You Need to Know Right Now (July 2026)
On July 1, 2026, speaking at the ECB’s annual forum in Sintra, Portugal, Fed Chair Kevin Warsh said inflation is “too high” and declined to hint at what the Fed might do at its July meeting. That same morning, the June ADP private payrolls report came in at just 98,000 — well below the roughly 120,000 economists expected, according to ADP’s official release.
Here’s where the crowd goes wrong: weak jobs data usually reads as “economy is softening, the Fed will cut soon to stimulate.” That’s the reflex. But the Fed literally told you a different story three weeks earlier.
At Warsh’s first FOMC meeting as Chair on June 16–17, 2026, the Fed held rates at 3.50%–3.75% in a unanimous 12-0 vote. But the real signal wasn’t the hold — it was the Summary of Economic Projections (the “dot plot”) released at the same time. The dot plot flipped: the median policymaker now sees rates ending 2026 higher than today — that’s a flip from the March projection, which had implied a cut. And 17 of 18 officials on the committee see the risks to inflation tilted to the upside. About half the committee pencils in at least one rate hike this year.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Let that sink in. The Fed’s own officials are telling you — in their own projections — that the next move is more likely to be up than down. And Warsh’s July 1 statement confirmed he is not in a hurry to change that.
The Assumption: “The jobs numbers are weak — that means the Fed will have to cut rates soon, and my credit card APR will come down.”
The Reality: Weak jobs and sticky inflation at the same time is exactly the environment where the Fed is most constrained. The June dot plot shows the median Fed official sees rates ending higher than today. Waiting for a rate cut to fix your debt problem means betting against what the Fed just published.
Why This Matters If You’re Carrying Variable-Rate Debt
Here’s the practical impact. Most credit card APRs are pegged to the prime rate, which moves directly with the Fed funds rate. At 3.50%–3.75% fed funds, prime sits at 6.50%–6.75%, and the average credit card APR has been running in the 20%–24% range for the better part of two years.
If you’ve been making minimum payments and telling yourself “I’ll attack this debt once rates come down and the APR drops” — that plan just got harder to defend. According to the Fed’s own data, “later” may mean higher rates, not lower ones.
I’ve seen this pattern before. In my experience helping people navigate debt since 1994, one of the most common traps is what I call waiting for a rescue. The interest keeps compounding while the rescue stays theoretical. The math doesn’t care about hope.
I wrote about this exact dynamic back in June when bond traders started pricing in hikes — if you read that piece, check the update here because the dot plot has now confirmed what the bond market was anticipating. This isn’t a prediction anymore. It’s a projection from the people who actually set the rate.
What This Doesn’t Mean (Be Honest About the Nuances)
I want to be careful here, because one-size-fits-all panic is as bad as false hope.
If your debt is low-rate or fixed, “do nothing and monitor” is a legitimate position. A fixed-rate car loan or a fixed-rate mortgage doesn’t care what the Fed does next month. This analysis is specifically about variable-rate credit card debt, variable-rate home equity lines, and any balance carrying an APR above 15%.
The 0% balance transfer option is real — but it’s not free. A 0% balance transfer can genuinely help if you can clear the balance before the promotional period ends. But the math includes a transfer fee of roughly 3%–5% of the balance, plus the full standard APR applies to whatever remains when the promo expires. Run the actual numbers before you move. A $5,000 balance with a 3% transfer fee costs $150 upfront — that’s not nothing, and if life interrupts your payoff plan, the reversion rate will likely be just as high as what you left behind.
The June ADP number is one data point, not a trend. I’m not saying the economy is fine — I’m saying the Fed has made clear that its primary concern right now is inflation, not jobs. One soft payroll reading will not flip that calculus. That’s Warsh’s message, and it’s worth taking seriously.
Things to Consider Doing Now
Here’s what I think makes sense given what the Fed just told us:
1. Call your card issuer and ask for a hardship rate reduction. This is the least-discussed option and one of the most effective. Credit card issuers have hardship programs — lower temporary APRs, reduced minimums, waived fees — that they do not advertise. They exist, I’ve seen them work, and a 10-minute phone call is free. You’re not asking for charity; you’re asking to use a program that exists. The worst they say is no.
2. Attack your highest-APR balance aggressively now, not after the next Fed meeting. Every month you wait at 22% APR is money that does not come back. The math on compound interest doesn’t pause for macroeconomic uncertainty. If you have any surplus above your 3-month emergency cushion — and that cushion is non-negotiable — put it at the highest-rate balance first.
On the emergency cushion point: I wrote about this when readers were asking whether to drain savings to pay off debt. The answer is almost always no — here’s the reasoning. High-rate debt is expensive. But no emergency cushion means the next car repair or medical bill goes right back on the card at 22% APR, erasing everything you just paid down. Keep the cushion, attack the debt with surplus only.
3. If you can genuinely pay off the transferred balance within the promo window, a 0% balance transfer is worth running the numbers on. But model the transfer fee, model your realistic monthly payment, and have a plan B for what happens if the balance isn’t gone when the clock runs out. “I’ll figure it out” is not a plan B.
4. For aspirational savers who are watching this: If the Fed’s own dots are right and rates aren’t falling soon, that’s actually good news for high-yield savings accounts and short-term CDs. Those rates are still attractive by historical standards. If you’ve got an emergency fund sitting in a standard savings account earning nothing, moving it to a high-yield account costs you nothing and earns you meaningfully more while you wait. Just don’t lock money you might need in a CD with a penalty for early withdrawal — liquidity first.
5. If your debt load is genuinely unmanageable regardless of the rate environment, this is a good moment to get clear-eyed about your options. Debt is math, not morality. The Find Your Path quiz can walk you through your actual situation in about two minutes. And if you want to talk through the specifics with someone who knows this space cold, I’d point you to Damon Day — he offers free initial calls and has no product to sell you.
Key Takeaways
- The Fed held rates at 3.50%–3.75% in June 2026, unanimous 12-0.
- The dot plot flipped: median Fed official now sees rates ending 2026 higher, not lower, than today.
- 17 of 18 officials see inflation risk tilted upward; roughly half pencil in at least one hike in 2026.
- July 1: Warsh said prices are “too high,” declined to hint at a July cut.
- Weak jobs (June ADP: +98K) fuels false “cuts are coming” hope — but the Fed’s inflation concern outweighs one soft report.
- “Do nothing and monitor” is valid for fixed-rate, low-APR debt — NOT for variable or high-APR balances.
- 0% balance transfers can help but carry a 3%–5% transfer fee and a reversion rate; model the math first.
- Hardship rate reduction calls to your card issuer are free and often work — they just don’t advertise the program.
The Bottom Line
If you’re lying awake waiting for the Fed to cut rates so your credit card debt gets cheaper — I understand. I’ve been there. But the Fed just handed you a clear signal, and it’s not what the “weak jobs” headlines implied: the median policymaker’s own projection shows rates ending the year higher, not lower. Debt is math wrapped in emotion, and the math right now says waiting is expensive. The moves that matter — calling your issuer for a hardship rate, attacking the highest-APR balance with your surplus, keeping your emergency cushion intact — don’t require a favorable Fed announcement. They work regardless of what happens in July. You don’t need a rescue from Washington. You need a plan that works without one.
Free Tool — Cost of Inaction Calculator: Thinking about waiting to deal with your debt? The free Cost of Inaction Calculator shows exactly how much more you'll owe — in interest and lost retirement savings — for every month you delay. Calculate the Cost →
Frequently Asked Questions
Will the Fed cut rates in July 2026?
As of July 1, 2026, Fed Chair Kevin Warsh declined to signal a July rate cut and said inflation remains “too high.” The June dot plot — the Fed’s own projection — shows the median official sees rates ending 2026 higher than today, not lower. A July cut is possible but would require a significant shift in the inflation data between now and the July meeting. I wouldn’t plan your debt strategy around it.
Should I wait for lower interest rates before paying off my credit card debt?
I wouldn’t recommend it for high-APR variable debt. At 20%+ APR, every month you wait costs you real money. The Fed’s June 2026 projections suggest rates may go up before they go down. The better move is to attack the highest-rate balance now with any surplus above your 3-month emergency fund, and call your issuer to ask about a hardship rate reduction — it’s free and often works.
What does the Fed dot plot flip mean for my credit card APR?
The dot plot flip means the median Fed official now expects to raise rates at least once more in 2026, which would push the prime rate higher, and your variable-rate credit card APR with it. If the dots are right, your credit card APR could end 2026 higher than it is today. That’s the opposite of what many people have been counting on.
Is a 0% balance transfer a good idea right now?
It can be, but it’s not free. You’ll pay a transfer fee of roughly 3%–5% of the balance moved, and when the promotional period ends, the full standard APR (typically 20%+) applies to any remaining balance. Run the actual math: calculate your transfer fee, set a realistic monthly payment that clears the balance before the promo expires, and have a plan for what happens if you can’t. If you can genuinely pay it off in the window, it’s a useful tool. If you’re hoping you’ll “figure it out,” it can make things worse.
What if my debt feels completely unmanageable at today’s rates?
Then the rate environment is almost a side issue — and it’s worth looking honestly at all your options, not just the ones that feel safest from the outside. Bankruptcy, for instance, stops interest accrual completely, discharges eligible debt, and protects your retirement accounts. Federal Reserve research shows filers rebuild credit faster than people who struggle for years without filing. I filed myself in 1990 and rebuilt everything. The Find Your Path quiz can give you a sense of where you stand, and Damon Day offers free initial calls if you want to talk through specifics with someone independent.
My take is always input, not prescription. You know your situation better than I do. Whatever you decide, make sure it’s based on complete information — including the options most people don’t talk about.
If this helped you see through the noise, send it to someone else who’s been waiting on the sidelines for a Fed rescue that may not come the way they’re expecting.
Update (July 15, 2026): The June CPI data arrived the next day and told a different story. Headline CPI fell 0.4% for the month; core inflation was flat. The hike trigger Gov. Waller named did not trip. Read what the data actually said — and what it means for your debt plan.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



