

Quick Answer: On June 30, 2026, two federal judges struck down a Trump administration rule that would have stripped Public Service Loan Forgiveness (PSLF) from workers whose employers the Education Department decided had a “substantial illegal purpose” — just one day before it was set to take effect. For now, the existing PSLF program stands: teachers, nurses, and other public servants can still earn forgiveness after 10 years of qualifying payments. But if you feel jerked around by rule after rule, court after court, administration after administration — you are not imagining it, and it is not your fault.
And you never have to pay a company to pursue PSLF — here is why “pay us to get your loans forgiven faster” is a scam.
Expert Context: I’ve tracked federal student loan programs since I started helping people with debt in 1994, and I’ve watched multiple administrations rewrite the rules mid-stream — Biden’s forgiveness plans blocked by one set of courts, Trump’s overhaul blocked by another. I’ve seen borrowers make life decisions based on promises that got yanked out from under them. The whiplash is the story here, and it’s the part almost no one is talking about.
Here is the thing that makes my blood boil: none of the people this rule targeted did anything wrong. They took jobs as public defenders, immigration lawyers, nurses at nonprofit clinics, and counselors at community organizations — often for less money than the private sector pays — because Congress promised them in 2007 that 10 years of that work would erase their federal student loans. Then, nearly two decades later, they woke up to find their forgiveness might vanish not because of anything they did, but because of what a political appointee decided about their employer. That is what it looks like to be a pawn.
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 16): The truck was $28,999 online. At the desk it’s $31,400. As of yesterday, the FTC says the ad was the lie.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
Let me walk you through exactly what happened, why it matters, and — most importantly — what you should actually do if you’re chasing PSLF right now.
Key Terms Defined
Public Service Loan Forgiveness (PSLF): A federal program created by Congress in 2007. If you work full-time for a qualifying public service employer (government or eligible nonprofit) and make 120 qualifying monthly payments, the government forgives your remaining federal Direct Loan balance — tax-free. See the official PSLF page at StudentAid.gov.
“Substantial illegal purpose”: The phrase at the center of this fight. The Education Department’s final rule (published October 31, 2025) would have let the Secretary of Education disqualify an employer from PSLF if the agency judged the organization to have a “substantial illegal purpose” — a definition the agency wrote itself, reaching beyond existing criminal law.
What the judges actually ruled
Two federal district judges — both appointed by President Biden — blocked the rule in separate cases on June 30, 2026, hours before it was scheduled to take effect on July 1.
In Massachusetts, U.S. District Judge Myong Joun issued a 68-page decision finding the rule “contrary to law,” beyond the Department’s statutory authority, “arbitrary and capricious,” and a likely violation of the First Amendment. His line that stuck with me:
“The Department cannot create new criminal prohibitions through rulemaking.”
— U.S. District Judge Myong Joun, June 30, 2026
Joun also wrote that “the Final Rule has already chilled protected speech” — meaning the mere threat of losing forgiveness was already pushing people and organizations to censor themselves, according to Bloomberg Law’s coverage of the decision. Separately, in Washington, D.C., U.S. District Judge Amir Ali struck down the same rule in a case brought by four nonprofits that advocate for immigration rights.
The challenge came from more than 20 states plus a coalition of nonprofit groups, who argued the rule would let the Education Department target organizations whose causes the administration disfavored. The rule was vacated entirely — it will not take effect. For now.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Why this is really about using debtors as pawns
Here’s what I want you to see clearly. This rule never punished a borrower for a borrower’s conduct. It punished the borrower for the employer’s politics — as decided by whichever party controls the Education Department at the moment.
Judge Joun caught exactly why that’s so dangerous: the rule “effectively compelled employers to affirm the administration’s view that all diversity, equity, and inclusion practices are illegal — a belief, not settled law.” In plain English, your ability to erase your student debt would have depended on your boss agreeing with the party in power. Change administrations, change the definition of an “illegal purpose,” and a whole different group of workers loses their forgiveness.
And this is the pattern I’ve watched for years, swinging both directions:
One administration blocked
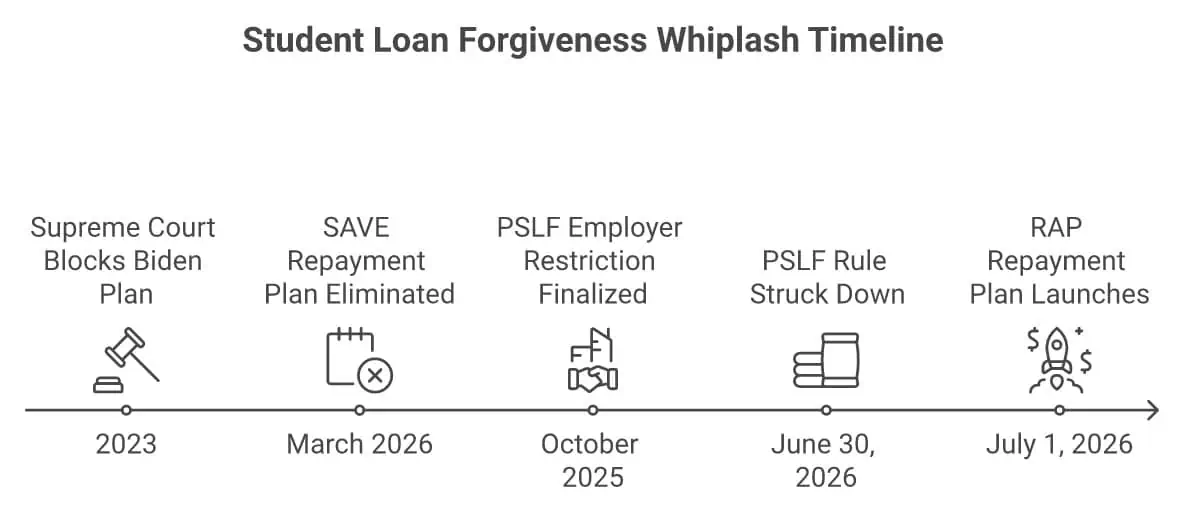
- Biden’s broad forgiveness plan was killed by the Supreme Court in 2023
- The SAVE repayment plan was ruled illegal and eliminated in March 2026
- Borrowers who enrolled in good faith were told to scramble to a new plan
The other administration blocked
- Trump’s PSLF employer restriction struck down June 30, 2026
- Blocked by courts one day before it took effect
- Public servants nearly lost forgiveness over their employer’s viewpoint
I wrote back in 2023 about what it feels like when the courts block forgiveness and leave you in purgatory. Different administration, same purgatory. The only constant is the borrower stuck in the middle, unable to plan a life around a promise that keeps getting rewritten. When forgiveness becomes a political football, the person kicked back and forth is you.
The Claim: “Student loan forgiveness is unreliable, so PSLF is probably dead — I should just give up on it.”
The Reality: PSLF itself was created by Congress in 2007 and is still the law. What just got struck down was an attempt to narrow it by rule, not the program. More than 1 million Americans have already had their loans canceled through it. Giving up on a program you legally qualify for — because of noise from a rule that a court just vacated — would be handing away real money. Don’t quit the game because the sideline is loud.
The cruelest timing: this all landed on July 1
Here’s a detail that shows just how much churn borrowers are being asked to absorb. The very same day this PSLF rule was supposed to take effect — July 1, 2026 — is also the day the new Repayment Assistance Plan (RAP) launched, replacing the eliminated SAVE plan. So on a single day, borrowers were simultaneously facing a new PSLF restriction (now blocked), the death of one repayment plan, and the birth of another with completely different math.
If your head is spinning, that is a rational response to an irrational amount of change. I broke down what actually changed on that date in my guide to the student loan changes that hit July 1 — including the auto-enrollment trap for former SAVE borrowers. If you were on SAVE, read that one next.
What you should actually do right now
Enough about the politics. Here is the practical part — what I’d tell a friend chasing PSLF today.
- Keep making qualifying payments and keep working. The existing PSLF rules are intact. The blocked rule doesn’t change your path — if you qualify today, keep going.
- Certify your employment every year. File the PSLF form annually (not just at the end) so your qualifying payment count stays current and any employer-eligibility question gets flagged early, not at year 10. Use the PSLF Help Tool at StudentAid.gov.
- Keep your own records. Save pay stubs, employment certification approvals, and payment confirmations. When rules change, the borrower with documentation wins.
- Don’t cash out retirement to “escape” the uncertainty. I say this in every debt post because it’s the most expensive mistake people make in a panic. Draining a 401(k) to pay off loans that might be forgiven — or to buy peace of mind during political noise — is almost always the wrong move.
- If your loans feel impossible no matter what, learn all your options. Forgiveness is one path. There are others, and the right one depends on your numbers, not the headlines.
Not sure which path fits you? Take my free Find Your Path quiz. It walks through your actual situation — income, loan types, goals — and points you toward the options that make sense for you, not for a politician’s talking point.
Key Takeaways
- Two federal judges struck down Trump’s PSLF employer-eligibility rule on June 30, 2026, one day before it took effect.
- The rule would have disqualified workers based on their employer’s alleged “substantial illegal purpose” — a definition the Education Department wrote itself.
- Existing PSLF is unchanged and still the law: 120 qualifying payments in public service = forgiveness.
- This is the same whiplash I’ve watched hit borrowers from both directions — Biden’s plans blocked one way, Trump’s overhaul blocked the other.
- Keep paying, certify employment annually, keep records, and never raid retirement out of panic.
The Bottom Line
If you took a public service job on the promise of forgiveness and you’re exhausted by every new rule and ruling — I see you, and none of this churn is a reflection of you. You did the honorable thing: you served, you paid, you kept your end of the deal. The rules keep changing because your debt became a political weapon, not because you did anything wrong. Here’s the truth to hold onto: the courts just protected your path, PSLF is still the law, and over a million people have already crossed that finish line. You are not a pawn in your own life — you’re the one who keeps showing up and doing the work. Keep going. The promise is still standing, and so are you.
Frequently Asked Questions
Is Public Service Loan Forgiveness still available after this ruling?
Yes. The June 30, 2026 rulings blocked a new restriction on PSLF — they did not touch the underlying program. PSLF remains the law Congress passed in 2007. If you work full-time for a qualifying government or nonprofit employer and make 120 qualifying payments, you can still earn forgiveness. Certify your employment annually through the PSLF Help Tool to keep your count current.
What was the “substantial illegal purpose” rule the judges struck down?
It was a Department of Education final rule, published October 31, 2025, that would have let the Secretary of Education disqualify an employer from PSLF if the agency decided the organization had a “substantial illegal purpose” — defined to include things like aiding illegal immigration, supporting terrorism, or providing gender-affirming care to minors. Two federal judges found the agency lacked authority to create these categories and that the rule likely violated the First Amendment. The rule was vacated before its July 1, 2026 effective date.
Could this PSLF rule come back?
It’s possible. Under Secretary of Education Nicholas Kent said the agency is “evaluating next steps,” which usually means an appeal or a revised rule. That’s exactly why documentation matters: certify your employment every year and keep your own records so that if the rules shift again, your qualifying payment history is already established. Rule changes generally can’t retroactively erase payments you’ve already made and certified.
I was on the SAVE plan — how does this affect me?
This PSLF ruling is separate from SAVE, but the timing overlaps. SAVE was ruled illegal and eliminated in March 2026, and its replacement — the Repayment Assistance Plan (RAP) — launched July 1, 2026, the same day this PSLF rule was blocked. If you were on SAVE, your most urgent task is choosing a new repayment plan before you get auto-enrolled into something more expensive. I cover exactly what to do in my guide to the July 1 student loan changes.
Should I stop paying my loans while the rules are being fought over in court?
No. Stopping payments doesn’t pause the clock in your favor — it can knock you off track for forgiveness and, depending on your loan status, push you toward delinquency or default. The existing PSLF rules are in effect, so keep making qualifying payments. If the payment itself is unaffordable, look at an income-driven plan rather than simply not paying. When you’re unsure which plan is cheapest over the life of the loan, run the numbers before you decide — and if the whole picture feels hopeless, take my Find Your Path quiz to see every option on the table.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



