

Written by Steve Rhode, consumer debt expert since 1994 • Last updated July 2, 2026
Quick Answer: The letter demanding money after your car was taken is called a deficiency balance — the gap between what you owed and what the lender got selling your car, plus their repo and sale costs. It’s real, but it is NOT automatically correct: federal commercial law required them to sell the car in a commercially reasonable way and to show you the math. You can demand the accounting, challenge a bad sale, negotiate, or — fastest for many people — wipe the whole deficiency out in bankruptcy. Don’t ignore it: unanswered, it becomes a lawsuit, then a judgment, then wage garnishment.
What Just Happened to Your Loan
When the lender repossessed your car, your debt didn’t go with it. The lender sold the car — usually at a dealer auction, usually for far less than retail — and applied the sale money to your loan after deducting the towing, storage, and auction costs, which is exactly the order UCC § 9-615 allows. Whatever is left over is the deficiency, and under the law of most states they can pursue you for it like any other unsecured debt.
That’s why the number on the letter feels absurd: you lost the car AND you still owe thousands. A $14,000 loan balance minus a $7,500 auction sale plus $1,200 in repo and sale fees leaves a $7,700 deficiency — on a car you no longer have. And if you handed the keys back voluntarily, the math is the same — voluntary surrender does not erase a deficiency.
One important exception: if the repossessed vehicle was a title loan, not a standard auto loan, several states (Georgia is the clearest) treat the transaction as a pawn — the debt is satisfied by law once the lender takes the car, with no deficiency lawsuit possible. See the title loan seizure crisis guide for how that works state by state.
The Mistake You’re About to Make: Panic-agreeing to a payment plan on the phone — or sending a “good faith” payment — before you’ve seen the sale accounting. You have a legal right to a written explanation of how the deficiency was calculated (UCC § 9-616), and in many states a payment or written acknowledgment can restart the clock they have to sue you. Demand the math first. Check your options first. Agree to nothing on the phone.
Your Options Right Now
What to Do in the Next 48 Hours
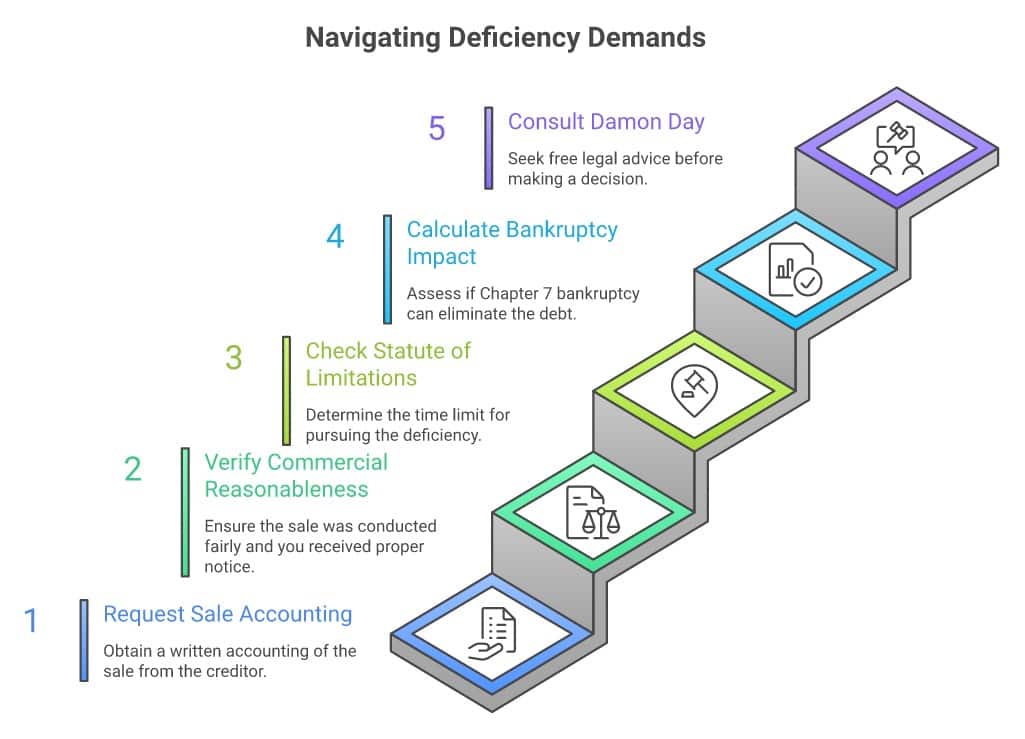
- Demand the written deficiency explanation. Send a letter (keep a copy) asking for the accounting of the sale under UCC § 9-616: sale price, sale date and method, and every fee they added — once your written request is received, they have 14 days to send the explanation. If a debt collector — not the original lender — is demanding the money, also send a written dispute within 30 days of their first contact under the Fair Debt Collection Practices Act; collection must pause until they validate. If the letter comes from a debt buyer that purchased the account, your position is often stronger still — buyers frequently cannot produce the notice and sale paperwork the law required.
- Check whether the sale was done right. The sale had to be commercially reasonable and you were entitled to advance written notice telling you how and when the car would be sold. No notice, or a sale far below what similar cars actually bring, can reduce — sometimes eliminate — the deficiency, and in consumer cases UCC § 9-625 sets minimum statutory damages of the credit service charge plus 10% of the principal, even without proving actual dollar harm.
- Find your state’s statute of limitations before you pay anything. Lenders typically have roughly 3 to 6 years to sue on a deficiency — most states fall in the 3-to-5-year range — but the window varies by state — and in some states a partial payment can restart it. If the demand is about an old repossession, check the date before you do anything else.
- Run the bankruptcy math. A deficiency is unsecured debt — exactly the kind Chapter 7 wipes out completely, and the automatic stay stops all collection the moment you file — not weeks later (11 U.S.C. § 362). If the deficiency sits on top of credit cards or medical bills, one filing can clear all of it. Find a bankruptcy attorney through NACBA, or take the free 2-minute bankruptcy quiz.
- Talk it through with someone who sells nothing. Talk to Damon Day for free about whether to challenge, negotiate, or discharge — before the lender’s timeline makes the choice for you.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
How to Actually Stop It — Your 4 Paths
- Bankruptcy — the full reset. The deficiency is unsecured, so Chapter 7 discharges it entirely, along with the credit cards that usually travel with a repo. The automatic stay halts the collection calls and any lawsuit instantly. Federal Reserve research shows filers recover financially faster than people who limp along without filing.
- Challenge the sale. If they can’t produce the required notice or the sale wasn’t commercially reasonable, the deficiency can shrink or die. A NACA consumer attorney can evaluate this quickly — many take these cases on contingency because the statute awards damages for violations.
- Negotiate a settlement — in writing. Deficiency paper is weak paper: lenders know their sale can be attacked, and they routinely accept a fraction as payment in full. Never pay a dime until the deal is in writing and says “settled in full.” A partial payment without that language can restart the lawsuit clock.
- What WON’T work: ignoring it. An ignored deficiency becomes a lawsuit; an ignored lawsuit becomes an automatic default judgment; a judgment becomes wage garnishment. Every escalation removes options you have today.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
What You Need to Know About Your Rights
You’re entitled to a written explanation of the deficiency math
Typical window to sue on a deficiency — varies by state
What a discharged deficiency costs you after Chapter 7
The automatic stay stops collection the moment you file
The rules below come from Article 9 of the Uniform Commercial Code, which nearly every state has adopted for auto loans, plus federal protections:
| Your right | The rule | What it means |
|---|---|---|
| Notice before the sale | UCC § 9-611 / § 9-614 | Written notice of how and when your car would be sold, before it was sold |
| A fair sale | UCC § 9-610 | Every aspect of the sale must be “commercially reasonable” |
| See the math | UCC § 9-615 / § 9-616 | Proceeds applied in a fixed order; written deficiency calculation for consumers |
| Damages for violations | UCC § 9-625 | Statutory damages when they break the rules — leverage for you |
| Active-duty military | SCRA, 50 U.S.C. § 3952 | No repossession without a court order — applies only to loans taken (with a payment made) BEFORE active duty |
| Bankruptcy protection | 11 U.S.C. § 362 | Automatic stay stops deficiency collection immediately on filing |
Your state may limit or even bar the deficiency entirely. A number of states restrict deficiency claims on consumer vehicle loans — some bar them below a balance threshold, and some make the lender choose between keeping the car and suing you. This is exactly the question to put to a NACA consumer attorney in your state before you pay anything. For the moment-of-repossession playbook (getting your belongings back, redemption, reinstatement), see the companion guide: My Car Was Just Repossessed.
If the collector is threatening you, calling relentlessly, or won’t show the sale accounting, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, and I know the exact feeling this letter creates — they already took the car, and somehow you owe more? It reads like a punishment for being broke. It isn’t. It’s arithmetic the law lets them do, and the same law gives you real counters most people never use. You are not bad with money; you hit a rough stretch in a system built to protect the lender first. The people I’ve watched come through this best did one thing differently: they responded in the first week — demanded the math, checked the sale, ran the bankruptcy numbers — instead of hoping it would go away. It never just goes away. But it is very, very fixable.
Frequently Asked Questions
My car was repossessed and they say I still owe money — is that even legal?
In most states, yes. The sale price minus costs gets applied to your loan under UCC § 9-615, and the shortfall — the deficiency — survives as unsecured debt. But the amount is only enforceable if they followed the notice and fair-sale rules, and you have the right to see the calculation.
They sold my car at auction for way less than it was worth — can I fight the number?
Possibly, and this is the most commonly missed defense. The disposition must be commercially reasonable in every aspect — method, time, place, and terms. A sale wildly below what comparable cars actually bring, or a sale you never received proper notice of, can reduce or eliminate the deficiency and even entitle you to damages under UCC § 9-625.
Can they garnish my wages over a repo deficiency?
Not without suing you first and winning a judgment. That’s why ignoring the letter is the one guaranteed losing move — an unanswered lawsuit becomes a default judgment, and a judgment unlocks wage garnishment in most states.
I filed bankruptcy — how fast does it stop the deficiency collection?
The moment your case is filed. The automatic stay takes effect immediately — not weeks later — and stops the calls, letters, and any lawsuit. In Chapter 7, a deficiency balance is ordinary unsecured debt and is typically discharged completely — see the complete Chapter 7 guide. (One caveat: if you signed a reaffirmation agreement on the car loan during a past bankruptcy and defaulted afterward, that debt survived the discharge.)
Do they have to show me how they calculated what I owe?
Yes. In consumer-goods transactions, UCC § 9-616 requires a written explanation of the deficiency — the sale proceeds, the costs added, and the arithmetic. If they demand money but won’t show the math, put your request in writing and mention this section. Their silence is leverage.
Should I just set up a payment plan to make it stop?
Not before you’ve seen the accounting, checked the sale, and looked at the statute of limitations. In many states a payment — or even a written acknowledgment of the debt — can restart the clock they have to sue you. If you do settle, get “payment in full” in writing before any money moves.
I’m in the military — do I have extra protections?
Yes. If you took the loan — and made at least one payment or deposit — before entering active duty, the Servicemembers Civil Relief Act bars repossession without a court order, and courts can adjust the obligation. It does not cover loans taken out after you entered active duty. (For a real-world example of SCRA enforcement, see the CarMax repossession settlement.) A repo done in violation of the SCRA is a serious problem — for the lender. Raise it immediately with a NACA attorney or your installation’s legal assistance office.
How long can they come after me for this?
It varies by state — commonly in the range of 3 to 6 years from default, with most states at 3 to 5. A debt too old to sue on can’t be won in court, but collectors may still ask you to pay. If the repossession was years ago, verify the date and your state’s window before responding — and be careful, because in some states a new payment revives an expired clock.
One more thing — everything I share here comes from more than 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A deficiency balance is real debt, but it’s negotiable, challengeable, and dischargeable. Demand the written sale accounting this week, compare all your debt relief options, and talk to an attorney before you pay anything. The longer you wait, the closer it gets to a lawsuit — and a judgment takes away the leverage you have right now.
The Bottom Line
You are not bad with money — you’re a person whose car was taken in a system designed to protect the lender at every step. The same law that let them sell your car also handed you rights most people never use: the right to see the math, the right to a fair sale, and the right to erase the whole thing in bankruptcy if that’s what your numbers say. The people who come through this best act in the first week. If someone you know just got a deficiency letter after a repo, send them this page — it may be worth thousands of dollars and a lot of sleep. Start with the Find Your Path quiz, and if you’re facing the tow truck moment itself, here’s the companion guide.
If you’re a servicemember and the original repossession happened while you were on active duty, that repossession may have violated federal law on its own, separate from the deficiency balance — here’s how the Servicemembers Civil Relief Act protects your vehicle from repossession without a court order.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



