

Quick Answer: The “debt consultant” who answers when you call a debt settlement company is typically a commissioned salesperson working under a monthly enrollment quota — not a financial advisor with any duty to you. A handwritten journal filed as an exhibit in a June 2026 federal lawsuit shows what that job looks like from the inside: 40-person sales training classes, a 12-enrollments-a-month quota, managers jumping onto live customer calls yelling “wrap it up” — and not one page about whether a single client ever got out of debt.
Part of the Debt Research Library: This post is one piece of my complete Debt Research Library — academic research on why consumers make the wrong debt choices, what outcomes actually show, and how to evaluate your options without a conflict of interest attached to the answer.
Expert Context: I ran a credit counseling organization from the inside, and I’ve spent the years since 1994 documenting how debt relief really gets sold. I’ve read a lot of court filings about this industry. This is the first time I’ve seen the daily life of a debt settlement salesperson written down in his own handwriting, on yellow legal pads, and entered into a federal court record — and it confirms what insiders have whispered to me for decades.
A fired debt settlement salesman kept a journal of his 17 days on the phones, and it just landed in federal court. If you’ve ever wondered who’s really on the other end of that “free debt consultation,” you now have an answer under a case number.
Where This Story Comes From
On June 26, 2026, a former employee of a large debt settlement company filed a lawsuit against his old employer in federal court in Arizona. I’m deliberately not naming the company or the man, because the company isn’t my point. The job is. His legal claims are about how he was treated as an employee — he says he asked for disability accommodations and was denied, and a court will sort that out. What stopped me cold was everything else in the file.
Attached to his complaint are 57 pages of exhibits: his handwritten day-by-day journal on yellow legal pads, plus screenshots of employee reviews of the company. Everything below comes from those court exhibits. Keep in mind these are allegations and one man’s account — the company hasn’t told its side in court yet. But I’ll tell you this: after documenting this industry since 1994, nothing in that journal surprised me. It reads like the industry insiders have always described it. Years ago I published a confession from another one — “I Was a Bait and Switch Debt Relief Sales Person” — and the two accounts rhyme.
Seventeen Days on the Phones
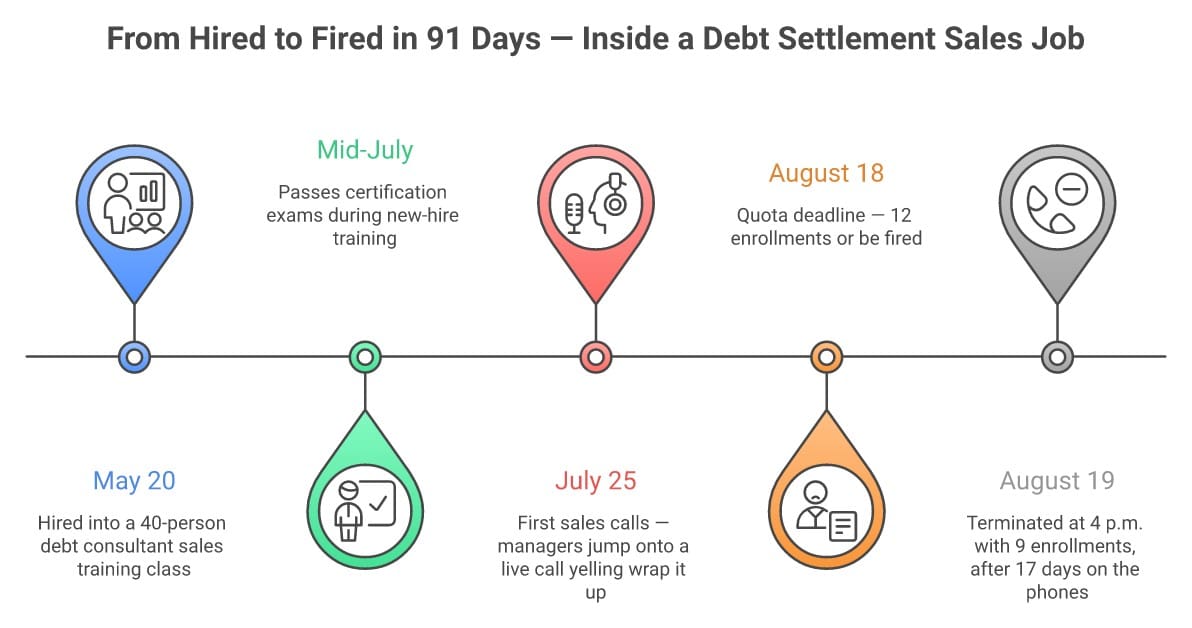
Here’s the timeline the journal lays out. Hired in May 2025 into a training class of 40 people — all of them “debt consultants.” Passed the company’s exam and an industry certification test in mid-July, during training. Started making sales calls in late July. Terminated at 4:00 p.m. on August 19, 2025 — about 17 working days after he first picked up the phone.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
In between, his journal describes a job I’d recognize anywhere, and it’s not financial advising:
- On one of his first calls with a genuinely interested customer, he says two managers jumped into his headset mid-conversation yelling “wrap it up, wrap it up, wrap it up!” — while he wasn’t sure whether the customer could hear them too. Five minutes later, a manager was back in his ear: there’s no overtime, get off the phone.
- Forced to end that call and schedule a Monday callback, he wrote down exactly what he knew would happen next: over the weekend “the customer would either be called from a different settlement company.” She was. She texted him that she’d gone with a competitor.
- He says a manager made him put a live customer on hold — someone mid-conversation about their debts — to discuss taking a longer lunch so he wouldn’t hit overtime.
- He says he worked unpaid on a Saturday to finish setting up two enrollments.
- When he asked two managers point-blank whether he’d be fired if he didn’t hit 12 enrollments, he wrote that they “laugh and shrug it off like it is nothing.”
- He was terminated, he says, the same day he completed his ninth enrollment of the month. The quota was 12.
Read that list again and ask one question: where, in any of it, is you — the person with the debt? Every pressure in that room points at closing you, not helping you.
What the Attached Employee Reviews Describe
The exhibits also include screenshots of reviews written by people identifying themselves as current and former employees of the company. These are anonymous and unverified — treat them as claims, not findings. But the picture they paint is remarkably consistent:
- “You are chained to your desk … dial 200-300 dials a day on an autodialer and click a button every 10 secs,” with 250 or more voicemails a day. The same reviewer’s summary of the product: negotiating debt down while “rolling in 25% of their debt as fees … It’s all bait and switch.”
- Several reviews describe a lead game: new salespeople get good leads for their first 90 days, then the quality leads get routed to managers’ favorites — one reviewer says the only way to earn is “working 80+ hours a week.”
- One review claims the company changed the commission structure “the day before they are to pay out the commission.” Another describes a compensation system that, in the reviewer’s words, “rewards shady sale[s].”
- Another describes new-hire classes held to escalating quotas — a class of 31 held to a 12-deal number, later raised to 15, with the majority of a class terminated or recycled through training for missing it.
Anonymous reviews can be unfair. But notice what they’re all arguing about: leads, dials, quotas, commissions. Not one of them is arguing about whether clients ended up better off. In 57 pages of exhibits about daily life inside a debt settlement sales floor, client outcomes never come up. That silence is the story.
Not One Minute of This Is About Your Financial Life
The debt relief industry has understood for more than a century that selling is psychology, not accounting. As one of the earliest sales-training texts put it:
“A sale is the action and reaction of mind upon mind, according to well established psychological principles and rules.”
— William Walker Atkinson, The Psychology of Salesmanship (1913)
That was written 113 years ago. The autodialer just made it scale.
The Claim: “Your certified debt specialist will review your situation and find the best way out of debt for you.”
The Reality: According to this court filing, the “consultant” on your call may have passed his industry certification exam a couple of weeks earlier — during new-hire sales training — and is working a script, on commission, under a monthly enrollment quota, with managers listening live and pushing him to close. He is evaluating exactly one option for you: the one he’s paid to sell.
This matters because the choice between debt settlement, a debt management plan, bankruptcy, or simply riding things out for a season is one of the biggest financial decisions of your life. It deserves someone who will run all your options honestly — including the ones nobody earns a commission on. My research hub on why most debt advice is wrong walks through the conflict of interest baked into nearly every corner of this industry, and a court case I covered earlier laid out how the attorney-model version of this business works, dollar by dollar.
The Law Already Treats That Call as Telemarketing — So Should You
Here’s a detail most people never hear on the “free consultation”: federal regulators don’t classify that call as advice. They classify it as telemarketing. The FTC’s Telemarketing Sales Rule contains a special advance-fee ban written just for this industry — under 16 C.F.R. § 310.4(a)(5), a debt relief company generally cannot collect a fee until it has actually settled or renegotiated at least one of your debts and you’ve made at least one payment under that new agreement. Regulators didn’t write a rule like that for an industry with a clean sales record.
The CFPB’s plain-language warning about debt settlement says the rest: these companies “often charge expensive fees,” some of your creditors “may refuse to work with the company you choose,” the approach typically requires you to stop paying your bills while late fees and penalty interest pile up, and — their words — “debt settlement may well leave you deeper in debt than you were when you started.”
If You’re on One of These Calls
I’m not telling you every debt settlement salesperson is a bad human being. The man who wrote this journal comes across as someone genuinely trying to do right by his customers inside a system that punished him for it — he lost a customer because managers yelled over the call, and he got fired days after his ninth enrollment. The problem isn’t the person. It’s the incentive structure wrapped around the person. So protect yourself accordingly:
- Remember who’s on the other end. A quota, a script, a commission, and possibly a manager listening live. Warmth is part of the training.
- Ask two questions: “How are you paid?” and “What percentage of your clients complete the program and settle all their enrolled debts?” Vague answers are answers.
- Ask them to compare bankruptcy. A real advisor compares every option, including the one that pays them nothing. If bankruptcy gets waved away in a sentence, you’ve learned what the call is.
- Never enroll on the first call. The urgency is manufactured — remember, the journal shows the salesman worried a competitor would poach his customer over a weekend. Your situation can wait three days. Their commission can’t.
- Do the math on your whole life, not just the pitch. The Find Your Path quiz gives you a recommendation based on your actual numbers, with no quota behind it.
Before You Sign Anything: Run the agreement through my free Contract Decoder — it reads debt relief contracts and flags the fees, terms, and traps in plain English. And if you want an actual human being to talk it through with, Damon Day offers a free call and sells no program. If you’ve already enrolled and nothing seems to be happening, start with what to do when you’ve paid a debt settlement company and nothing happened.
Key Takeaways
- A journal filed in a June 2026 federal lawsuit gives a rare inside view of a debt settlement sales floor: 40-person training classes, a 12-enrollments-a-month quota, managers jumping into live calls to push the close.
- In 57 pages of exhibits about the job, client outcomes are never mentioned — the entire system described runs on dials, leads, and enrollments.
- “Certified debt specialist” can mean an exam passed during new-hire sales training, not independent expertise — this filing shows exactly that sequence.
- Federal law treats debt relief sales calls as telemarketing, with a special advance-fee ban (16 C.F.R. § 310.4(a)(5)) — and the CFPB warns settlement “may well leave you deeper in debt.”
- Never enroll on the first call. Compare all your options — including the ones no salesperson earns a commission on.
The Bottom Line
If you’ve been on one of those calls and felt rushed, confused, or strangely pressured, it was never because something is wrong with you — a federal court exhibit now shows the pressure was coming from a manager in the salesperson’s other ear. You are not your debt, and you don’t owe a stranger with a quota a decision on their timeline. The math of your situation belongs to you, and when you compare every option calmly — settlement, a payment plan, bankruptcy, or waiting — most people discover they have more power than the person on the phone wanted them to know. Take the pressure out of the decision, and the decision gets a whole lot clearer.
One personal note: my advice is input, not instruction. You’re the only one who knows your full situation, and you’re the only one who gets to decide. I just want you walking into that decision with your eyes open.
If someone you care about is talking to a debt settlement company right now, send them this before they sign anything. It might be the most valuable thing they read this year.
Frequently Asked Questions
Is the debt settlement person on the phone a financial advisor?
No. The “debt consultant” or “certified debt specialist” on a debt settlement sales call is typically a commissioned salesperson with no fiduciary duty to you. A June 2026 federal court exhibit shows one company’s consultants trained in 40-person sales classes, certified during onboarding, and held to monthly enrollment quotas. Federal regulators classify these calls as telemarketing under the FTC’s Telemarketing Sales Rule.
How do debt settlement salespeople get paid?
Primarily through commissions tied to enrollments — how many people they sign up, not how many people become debt-free. Employee reviews filed in the same court case describe low base pay near minimum wage, commission structures that changed without warning, and quota systems where missing the monthly enrollment number meant termination.
What does “certified debt specialist” actually mean?
It usually means the salesperson passed an industry certification exam — which can happen during new-hire training. In the court filing described here, the employee passed his certification test in mid-July during his training class and was making sales calls by the end of that same month. It is not a license, not a fiduciary standard, and not comparable to a certified financial planner or attorney.
Why do debt settlement companies pressure me to sign up on the first call?
Because if you hang up, a competitor may reach you first. The journal in this court filing shows the salesman knew that letting a customer wait over a weekend meant she “would either be called from a different settlement company” — and that’s exactly what happened. The urgency on these calls reflects competition between sales floors, not anything about your financial situation. Any option that’s right for you today will still be right after three days of thought.
What should I do before signing a debt settlement agreement?
Compare every option first — debt management plans, negotiating yourself, bankruptcy, and doing nothing for a season are all real choices. Run the contract through a tool like my free Contract Decoder, confirm the company cannot legally charge fees before settling a debt (16 C.F.R. § 310.4(a)(5)), and get an opinion from someone who isn’t paid to enroll you. Bankruptcy in particular deserves an honest look: Federal Reserve research shows filers recover faster than people who struggle on without filing.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



