

Quick Answer: Minnesota’s Attorney General has sued the cash advance app Brigit, alleging that its “earned wage advances” are really unlicensed payday loans carrying effective interest rates the state says regularly top 300% — and sometimes 700% — far above Minnesota’s 50% cap. Whether or not you use Brigit, this lawsuit is a reason to do one thing today: add up what your cash advance app is actually costing you, because the “optional tip” almost never is.
Expert Context: I’ve been helping people dig out of high-cost debt since 1994, and I’ve watched the payday loan playbook get rebranded over and over. The storefront lenders became online lenders, and the online lenders became friendly-looking apps with cartoon logos and a “tip” jar. The costume changes. The trap underneath — borrowing against next week’s paycheck at a rate that keeps you borrowing again — stays exactly the same.
On June 10, 2026, Minnesota Attorney General Keith Ellison filed a lawsuit against Bridge It, Inc., the company that does business as Brigit, alleging it is operating as an unlicensed lender and disguising payday loans as “earned wage advances.” I want to be careful with my words here: these are allegations. A court has not ruled, and Brigit has not been found to have broken any law. But the complaint is public, and what the state describes is worth every cash-advance-app user’s attention — not because of one company, but because of a business model millions of people are using without doing the math.
Key Terms Defined
Earned wage access (EWA): Getting a piece of pay you’ve technically already earned before your official payday. Some versions run through your employer’s payroll; others, like the apps in this story, are direct-to-consumer and front you the money themselves.
APR (annual percentage rate): The real yearly cost of borrowing, including fees, expressed as a percentage. A “$5 tip” on a $50 advance you repay in a week doesn’t feel like interest — but annualized, it can dwarf a credit card.
What Minnesota Says Brigit Is Doing
According to the Attorney General’s announcement and the complaint filed in court, the state alleges that Brigit markets itself as offering “earned wage advances” while actually functioning as an “unlicensed, unregistered, consumer small-loan and consumer short-term lender.” In plain English: the AG says it’s a payday lender wearing a different name tag.
The specific mechanics the complaint points to are what caught my eye, because I’ve seen this exact structure before:
- The app allegedly requires you to preauthorize Brigit to pull the advance amount — plus any fees — straight out of your bank account on a set date.
- The state says the app does not clearly disclose, in the normal flow, that repayment is supposedly “voluntary,” and offers no easy in-app way to decline or cancel that automatic repayment.
- The AG alleges customer service responses reinforce that you owe the money back — which, if true, is hard to square with the “it’s just a voluntary tip” marketing.
Attorney General Ellison put it bluntly in the announcement: “Regardless of how Brigit markets itself, the advances it offers consumers in need of cash are clearly loans.” That’s his position, and a court will decide whether it holds. But you don’t need a judge to tell you that money automatically debited from your account on payday is a loan repayment, no matter what the app calls it.
The Claim: “We’re not a payday lender. Tips are optional, and there’s no interest.”
The Reality: Minnesota isn’t the first state to push back on this framing, and courts elsewhere have already looked past the “voluntary” label. New York’s Attorney General sued a different cash advance company, MoneyLion, in 2025 on the same theory, and the National Consumer Law Center has documented courts in several states ruling that these products are loans subject to lending law. The “optional tip” defense is being tested — and it’s not winning cleanly.
Why This Matters Even If You’ve Never Heard of Brigit
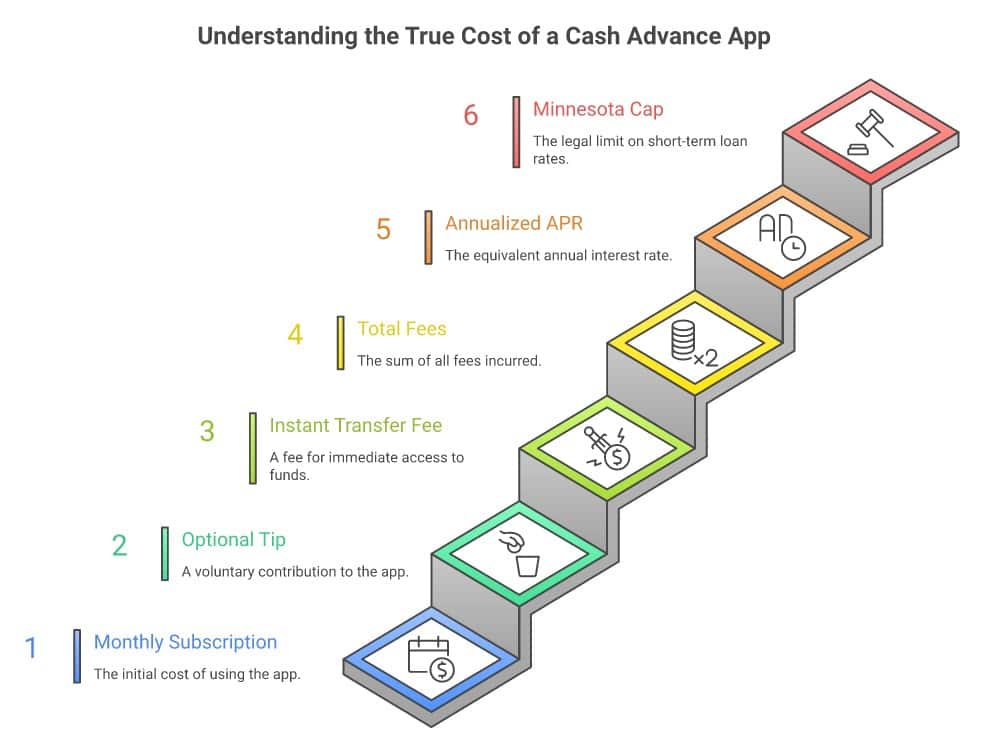
Here’s the part I care about most. This isn’t really a story about one app. Brigit, Dave, Earnin, MoneyLion, and a handful of others all run some version of the same model: a monthly subscription, a “tip” on each advance, an extra fee if you want the money instantly instead of in a few days. Each piece feels tiny. Stacked together, and repeated every single pay period, they add up to a rate that would make a storefront payday lender blush.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
And the deeper trap isn’t the fee — it’s the cycle. If you’re pulling an advance every payday to cover the gap the last advance left behind, you’re not bridging an emergency. You’re renting your own paycheck back from an app, over and over. I’ve watched that loop swallow people for years. The apps didn’t invent it. They just made it frictionless.
The math nobody shows you: A “$4.99 subscription + $3 tip + $2 instant fee” on a $60 advance repaid in a week isn’t $10. Annualized, that’s an APR north of 800%. The whole design depends on you never running that number. So run it.
What To Actually Do This Week
You don’t have to wait for a court ruling to protect yourself. Here’s what I’d tell my own family:
- Audit your app. Open whichever cash advance app you use. Add up every subscription fee, every tip, and every instant-transfer fee you’ve paid over the last six months. Divide that by the total dollars you actually borrowed. That percentage is your real cost. If it shocks you, that’s the point.
- Break the cycle before you cancel. If you’re advancing every payday, canceling cold turkey just recreates the shortfall. Cover the gap once — with a one-time budget reset, a credit union or CDFI small-dollar loan at a legal rate, or even your bank’s overdraft protection — then stop the recurring drain.
- If you’re in Minnesota, speak up. You can file a complaint with the Minnesota Attorney General’s office. Complaints are part of how these cases get built.
- Do nothing — if the math is genuinely fine. If you’ve used an app once for a true emergency and paid a few dollars, that’s not a crisis. This isn’t about shame. It’s about knowing your number.
If this all sounds familiar, it should. I wrote recently about how earned-wage-access apps are payday loans in a costume — that piece looked at the employer-integrated versions like DailyPay and Payactiv. This Brigit lawsuit is the direct-to-consumer cousin: same underlying question, different plumbing. A regulator is now asking a court to call it what it is.
The Bottom Line
If you’re leaning on a cash advance app to make it to payday, you are not careless and you are not alone — you’re doing exactly what the app was designed to make easy. But easy and cheap are not the same thing. The label on the fee doesn’t matter; the drain on your paycheck does. Run your own number this week, and if it scares you, treat that as good news — because now you can stop feeding the cycle instead of wondering why the gap never closes. You earned that paycheck. You shouldn’t have to keep renting it back.
Frequently Asked Questions
Is Brigit illegal?
No court has found Brigit did anything illegal. Minnesota’s Attorney General has alleged in a lawsuit that Brigit operates as an unlicensed lender, but those are allegations a court still has to decide. Brigit is entitled to defend itself, and I’m not going to convict a company a judge hasn’t.
What’s wrong with a “tip-based” cash advance app?
Nothing is automatically wrong with using one for a rare emergency. The problem is when the “optional” tips, subscription fees, and instant-transfer charges add up to an effective interest rate far higher than a normal loan — and when you’re advancing every single payday, which turns a one-time bridge into a permanent, expensive cycle.
How do I figure out the real cost of my cash advance app?
Add up every fee you’ve paid over the last six months — subscription, tips, instant-transfer charges — then divide by the total amount you actually borrowed. That gives you your real cost as a percentage. Annualize it and it often lands in triple digits, well above a credit card.
What should I use instead of a cash advance app?
For a true one-time gap, a small-dollar loan from a credit union or CDFI at a legal interest rate, or your bank’s overdraft protection, is usually far cheaper. The bigger fix is breaking the payday-to-payday cycle so you don’t need the advance next month — that’s where the real savings live.
Are other states doing anything about these apps?
Yes. Minnesota is not the first. New York’s Attorney General sued MoneyLion in 2025 on a similar theory, and courts in several states have already ruled that cash advance app products can be loans subject to lending law. This is a growing area of regulatory attention, not a one-off.
Before You Sign Anything: Run any debt relief contract through the free Contract Decoder to spot hidden fees and unfair terms. Check the company’s complaint history with the Scam-O-Meter.
Compare Your Real Options: Most debt relief companies won’t tell you about all your options — especially the ones they can’t profit from. Credit counseling has a 21-27% completion rate. Settlement resolves about 1% of enrolled debts fully. Bankruptcy has a 95% discharge rate — and protects your retirement. Take the Find Your Path quiz for a recommendation based on your actual numbers.



