

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 4, 2026 • Every claim below links to a primary source.
And if the fear stopping you is losing everything you own, that’s a myth — here’s what bankruptcy exemptions actually protect.
The verdict: Partly true — and the true part isn’t what you think. Yes, a bankruptcy can appear on your credit report for up to 10 years. But that is how long it’s reported, not how long you’re frozen out of credit. Federal Reserve research shows credit scores often recover to their pre-filing levels within about a year of filing — still subprime, but climbing, not frozen. The honest catch: your available credit limits tend to stay lower for a while afterward — on average. This post shows you the truth and the concrete moves that improve your odds against that average. Federal Reserve Bank of Philadelphia research confirms it.
Well, Actually…
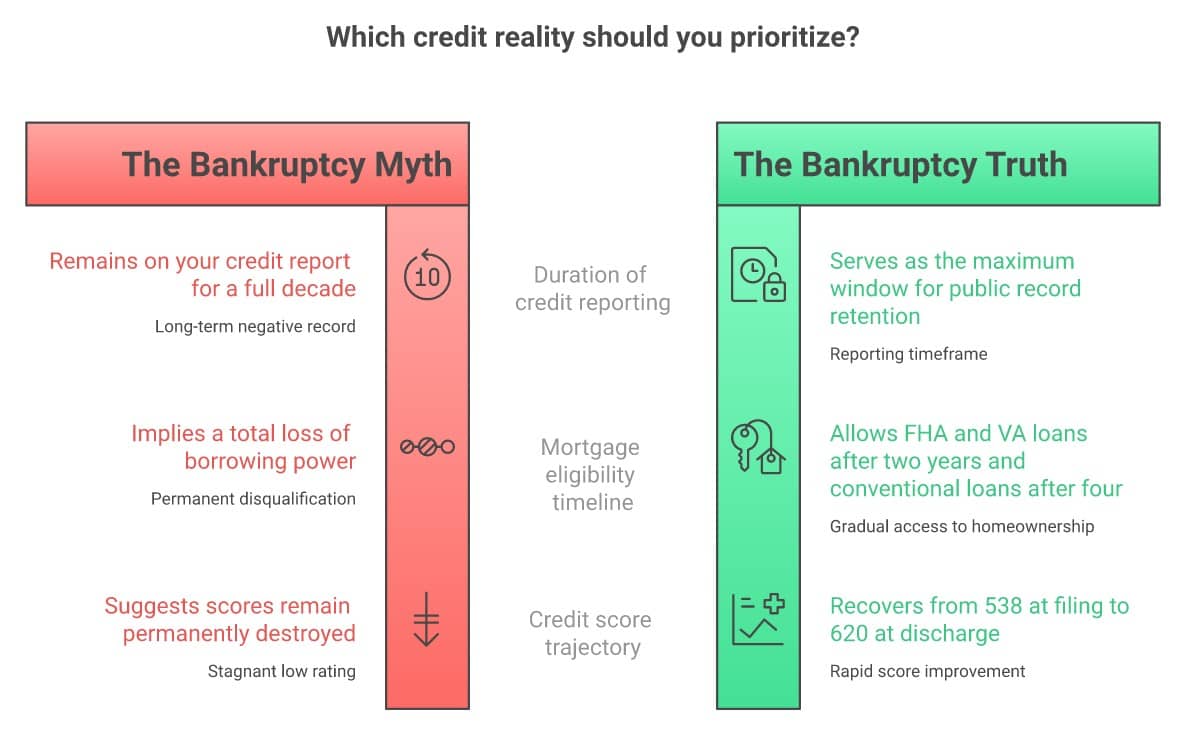
Here’s the part that gets left out. The “10 years” everyone repeats is a reporting rule, not a lending rule. Under the Fair Credit Reporting Act, a bankruptcy can stay on your credit report for up to 10 years. That’s the maximum window a credit bureau is allowed to show it — it is not a decade-long ban on borrowing, renting, or living your life. Those are two completely different things, and the whole myth survives by blurring them together.
And your credit score? It doesn’t sit at the bottom for ten years. Researchers at the Federal Reserve Bank of Philadelphia found that bankruptcy filers “returned roughly to their previous risk score levels within about one year after filing” — long before the bankruptcy itself falls off the credit report. For Chapter 7 filers the study tracked, that meant climbing from an average around 538 at filing back toward roughly 620 — a jump of about 80 points in months. One year, not ten. (Those are research figures from a specific study, and “recovered” means back to their pre-filing levels, which were already subprime — not instant prime credit. But the direction is unmistakable, and it’s nothing like a decade of ruin.)
So why does the fear feel so real? Because there’s a kernel of truth buried in it — just not the kernel people think. Let me show you all three pieces.
“Bankruptcy ruins your credit for 10 years.”
Ten years is the maximum time a Chapter 7 filing can be reported on your credit — not how long your credit is “ruined.” (Chapter 13 is removed in 7 years in practice, because all three major bureaus follow that policy — though the statute technically allows 10 years for every bankruptcy type.) Scores typically recover to their pre-filing level within about a year of filing. The one honest caveat: your available credit limits tend to stay lower for a while afterward — something you can actively work to improve, as I’ll show below.
Fair Credit Reporting Act, 15 U.S.C. § 1681c • Federal Reserve Bank of Philadelphia (Jagtiani & Li, 2014)
“No one will lend to you for a decade.”
You can get a mortgage in years, not a decade. An FHA loan is available 2 years after a Chapter 7 discharge; a VA loan for veterans, also 2 years; a conventional Fannie Mae loan, 4 years (2 with documented extenuating circumstances). These are minimum waiting periods, and they assume you’ve re-established good credit in the meantime — meeting the wait is necessary, but you still have to qualify. And secured cards and credit-builder loans are available almost immediately. The clock starts at discharge — which for Chapter 7 is usually just 3 to 6 months after you file.
HUD/FHA • VA Lenders Handbook 26-7 • Fannie Mae Selling Guide
“No one will even rent to you.”
There is no decade-long rental blackout. Landlord screening varies enormously, and a great many private landlords — especially individual owners rather than big management companies — don’t pull a credit report at all. A bankruptcy on your record is one factor a landlord might consider, not an automatic denial. Steady income and honest references carry real weight.
Landlord practices vary by owner; no federal rule bars renting to bankruptcy filers.
Why You Were Told This
Follow the incentive. Fear of a “ruined” credit score for a decade is one of the most effective tools the debt-relief industry has to steer people away from bankruptcy and toward years of debt settlement or a payment plan they profit from. If you believe bankruptcy is financial death, you’ll pay almost anything to avoid it — even when the math says it’s your fastest, cleanest path to a fresh start. The 10-year number is technically real, so it sounds honest. But quoting the reporting window as if it were a lending ban is how a true fact gets weaponized into a false conclusion.
And here’s what almost no one tells you: the research points the opposite way from the fear. Economists at the Federal Reserve Bank of New York studied what happened after a 2005 law made bankruptcy harder to access — and found that the people who ended up staying in debt distress instead of filing had worse outcomes than those who filed. Compared to people denied protection, those granted it earned more and faced far fewer foreclosures. The honest, uncomfortable truth is that avoiding bankruptcy to “protect” your credit often does more lasting damage than the bankruptcy would. I pulled that Federal Reserve research together in one place if you want to see it.
The One Real Catch — and How to Beat It
I promised you honesty, so here it is. The same Federal Reserve Philadelphia research that shows scores bounce back fast also found something less cheerful: “Despite speedy recovery in their risk scores after bankruptcy filing, most filers have much reduced access to credit in terms of credit limits, and the impact seems to be long lasting (well beyond the discharge date).” Even filers whose scores had recovered still had lower credit limits than their scores alone would predict — and it’s the lenders pulling back on the supply side, not the filers failing to apply.
I’m not going to wave that away. Reduced access is real, it can persist for years, and no clever trick erases it overnight. But read the finding for what it is: it measured what happens to the average filer, many of whom take no deliberate action at all. It’s an average, not a sentence. You’re not on autopilot — you’re sitting here reading a 2,000-word breakdown of exactly how this works. Rebuilding access is genuinely slower than rebuilding your score — I won’t pretend otherwise — but each of these moves is a documented way to push your available credit back up faster than doing nothing:
- Open a secured credit card after discharge. You put down a deposit, use the card lightly, and pay the balance in full every month. The CFPB lists this as a core rebuild tool. Many major secured cards offer a path to “graduate” to a regular unsecured card and return your deposit once you’ve shown a track record — but not all do, so confirm the issuer’s graduation policy before you open one.
- Add a credit-builder loan. In a CFPB study, opening one raised the likelihood of having a credit score by about 24 percentage points — the biggest benefit going to people who started with no active loan; if you already have credit history, the gain is more modest. Credit unions and community lenders (CDFIs) are the usual source.
- Become an authorized user on the account of a family member with strong, long-standing credit. Their limit and payment history can report on your file — access you didn’t have to qualify for alone.
- Keep your reported utilization low. Use the card lightly and pay it in full before the statement closes. Over time, a low-utilization, on-time record is what prompts issuers to raise your limits — and that’s the exact “access” the average filer never actively builds. (You never need to carry a balance or pay interest to do this.)
- Bank where relationships matter. Credit unions and CDFIs practice relationship lending and are often more willing to extend credit to a recent filer than a big national bank running a pure algorithm.
None of this is instant, and I won’t promise you a specific limit by a specific date — some tightness may linger for years no matter what you do. But these are the levers that actually move available credit, and the filer who pulls them ends up in far better shape than the passive average in that study. For the full month-by-month rebuild timeline, I mapped it out in my deeper guide on how your credit score actually recovers after bankruptcy.
Steve’s Take
I filed bankruptcy myself in 1990, after a real estate deal collapsed and took everything with it. I was sure my financial life was over. It wasn’t — it was the beginning of the rest of it. The decade-of-ruin story kept me frozen far longer than the bankruptcy ever did. If the math says a fresh start is your best path, don’t let a misquoted reporting rule scare you into three more years of grinding on debt that a discharge could erase. Your score is not your worth, and it recovers a lot faster than the people selling you fear want you to know.
Frequently Asked Questions
How long does bankruptcy really stay on my credit report?
Up to 10 years for Chapter 7 and, in practice, 7 years for Chapter 13 (all three major credit bureaus follow that Chapter 13 policy, though the Fair Credit Reporting Act technically allows 10 years for any bankruptcy). That’s how long it’s reported — not how long your credit is damaged.
How fast does my credit score recover after bankruptcy?
Faster than most people think. Federal Reserve Bank of Philadelphia research found filers returned roughly to their pre-filing risk-score levels within about a year of filing — long before the bankruptcy falls off the credit report. (For the Chapter 7 filers in that study, that meant rising from an average near 538 to about 620.) “Recovered” means back to your prior level, which was already subprime — not instant prime credit — but it’s a matter of months, not a decade.
Can I get a mortgage after bankruptcy?
Yes, and sooner than you’d guess. FHA and VA loans are available 2 years after a Chapter 7 discharge, and conventional loans at 4 years (2 with documented extenuating circumstances). These are minimum waits, and they assume you’ve re-established good credit in the meantime — you still have to qualify. The waiting period starts at discharge, not at filing.
Will a landlord refuse to rent to me after bankruptcy?
Not automatically. Landlord screening varies widely, and many private landlords don’t run a credit report at all. A bankruptcy is at most one factor a landlord might weigh — steady income and good references matter more than most people expect.
Is it true my credit limits stay lower even after my score recovers?
On average, yes — and this is the honest catch. Federal Reserve research found available credit limits stay reduced well beyond discharge, because lenders pull back — and some of that tightness can persist for years. But that’s the average across filers, many of whom do nothing. Actively rebuilding with a secured card, a credit-builder loan, low utilization, and credit-union relationships improves your access faster than sitting still, even if it doesn’t erase the gap overnight.
What’s the single best first move to rebuild credit access after bankruptcy?
A secured credit card opened right after discharge, used lightly and paid in full every month. The CFPB recommends it as a foundational rebuild tool. Many major secured cards graduate to unsecured credit once you’ve built a track record — but not all do, so confirm the issuer’s graduation policy before you open one.
This is one informed perspective after 30 years of helping people with debt — and having lived through bankruptcy myself. Only you know your full situation, so take this as input for your decision, not instruction. Nobody gets to tell you what to do with your money. Not me, not anyone.
The bottom line: “Ten years” is how long bankruptcy is reported, not how long it hurts — scores recover in about a year of filing, mortgages come back in 2 to 4 years, and the one real catch (tighter credit limits) is something you can actively work to improve. If someone you love is avoiding bankruptcy because they think it means a decade of financial ruin, send them this.
Tax debt is another place the “bankruptcy can’t help” myth falls apart — see when older IRS income tax actually can be discharged.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and Federal Reserve research shows bankruptcy filers recover faster than those who don’t file. For the full recovery timeline, see my guide on how credit recovers after bankruptcy.



