

Quick Answer: The SAVE student loan repayment plan is ending, and New York’s attorney general just issued a formal consumer alert urging the roughly 7.5 million borrowers on it to pick a new plan now. Here’s the trap: notifications started going out July 1, 2026, and if you don’t choose a new plan within 90 days of getting yours, you’ll be automatically dropped into the Standard Plan — which ignores your income and often means a much higher monthly bill. And while your loans have been “paused” in SAVE forbearance, interest has quietly been piling up since August 2025. This isn’t a drill. Log in, look at your options, and choose on purpose.
One caution while you switch plans: this kind of upheaval is bait for scammers. No company can move you to a new repayment plan faster or better than you can do yourself for free — here is why paying a company to “handle” your student loan forgiveness is a myth (and often illegal).
Expert Context: I’ve tracked federal student loan programs since their creation, and I’ve watched multiple administrations change the rules mid-stream while borrowers got whipsawed in between. The pattern is always the same: the people who get hurt aren’t the ones who make a bad choice — they’re the ones who make no choice and let the system pick the most expensive option for them by default.
If you’re one of the millions of people who enrolled in the SAVE plan because it gave you the lowest monthly payment you could find, I need you to stop what you’re doing and read this. SAVE is going away, the clock has already started, and doing nothing is the single most expensive move you can make.
On July 6, 2026, New York Attorney General Letitia James put out a consumer alert with a line I want every borrower to hear: “Student loans are already a heavy burden, and no New Yorker should find themselves in an expensive repayment plan they didn’t choose.” She’s right — and the warning applies to borrowers in every state, not just New York.
What’s Actually Happening to the SAVE Plan
SAVE (Saving on a Valuable Education) launched in 2023 as an income-driven repayment plan built to be one of the most affordable options ever offered. Then the courts got involved. In 2024, a federal court ordered the U.S. Department of Education to place every SAVE borrower into a mandatory forbearance and, eventually, to end the plan. The current administration announced its steps to wind SAVE down in December 2025. So this is a court-ordered shutdown working its way through the system — not a political talking point, just the reality landing in your loan account.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
Starting July 1, 2026, your loan servicer began sending notices telling you to choose a different repayment plan. That notice is what starts your personal clock.
The 90-Day Trap: If you don’t actively choose a new repayment plan within 90 days of receiving your servicer’s notice, you’ll be automatically moved to the Standard Plan. The Standard Plan does not look at your income — it just splits your balance into fixed payments, which for a lot of people means a monthly bill that’s far higher than what they were paying under SAVE.
The Part the Headlines Aren’t Telling You: Interest Never Stopped
Here’s what worries me most, and it’s the thing almost nobody is talking about. While your loans sat in that SAVE forbearance and you weren’t required to make payments, interest has been accruing the entire time — since August 2025, according to the Department of Education’s own SAVE forbearance guidance.
A “pause” that still charges you interest isn’t really a pause — it’s a quiet balance-builder. So the number you’re about to pick a new plan around is probably bigger than the last one you looked at. That doesn’t mean you did anything wrong. It just means you should go in with your eyes open and check your actual current balance before you commit to anything.
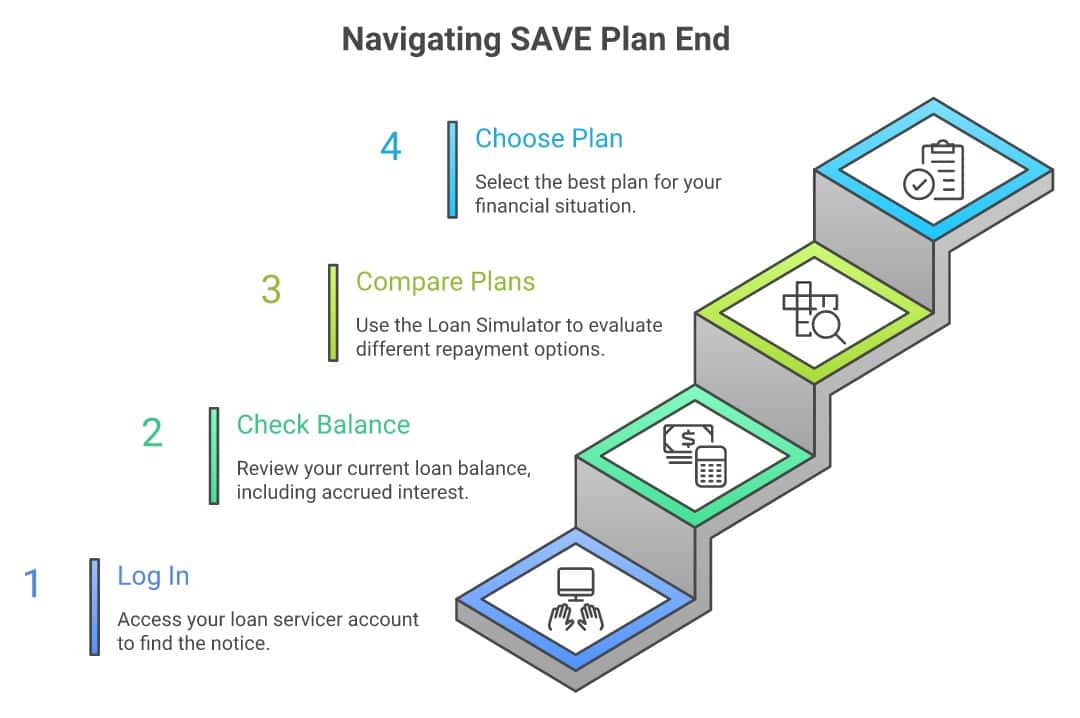
What to Do Right Now
- Log into your loan servicer account this week and read the notice. Note the date you received it — that’s the start of your 90-day window.
- Check your current balance, including the interest that’s built up during forbearance. Don’t assume it’s the same as before.
- Run your numbers before you choose. Use the free Loan Simulator at studentaid.gov to compare what each plan would actually cost you month to month and over the life of the loan.
- Choose a plan on purpose — don’t let the 90 days run out and get defaulted into the Standard Plan.
- Get free help if you’re unsure. New Yorkers can reach the Education Debt Consumer Assistance Program (EDCAP) at 888-614-5004 or edcap@cssny.org. Everyone can check official status at StudentAid.gov/courtactions.
For the full mechanics of the transition — how the new plans compare, what RAP is, and how to switch step by step — I walked through all of it in my guide to the July 1 student loan changes. And before you assume the plan with the lowest monthly payment is the cheapest, read why a lower payment can quietly cost you thousands more over time. This post is the “act now” alarm; those two are the deeper how-to.
Which Plans Are Even on the Table
What you can choose depends on when your most recent loan was disbursed or consolidated. If it was before July 1, 2026, you can generally pick from Income-Based Repayment (IBR), Pay As You Earn (PAYE), Income-Contingent Repayment (ICR), the new Repayment Assistance Plan (RAP, available as of July 1, 2026), or the Standard, Graduated, and Extended plans. If your most recent loan was disbursed or consolidated on or after July 1, 2026, your choices narrow to RAP or the Standard Plan.
One more date to file away: borrowers on the older PAYE and ICR plans will face their own deadline to choose new options by July 1, 2028. That’s further out, but it’s coming.
Key Takeaways
- SAVE is ending under a court order; servicer notices started July 1, 2026.
- You have 90 days from your notice to choose a new plan, or you’re auto-enrolled in the higher-cost Standard Plan.
- Interest has been accruing during the SAVE forbearance since August 2025 — your balance is likely bigger than you think.
- Run your options through the free studentaid.gov Loan Simulator before you commit.
The Bottom Line
If you’re staring at a student loan notice and feeling that familiar knot in your stomach — you’re not behind, and you’re not in trouble yet. You just have a decision to make, and a little bit of time to make it well. The borrowers who come through this fine aren’t the ones with the most money; they’re the ones who opened the letter, ran their numbers, and chose on purpose instead of letting a default rule choose for them. Take twenty minutes this week, log in, and pick your plan. That one small act of paying attention is worth more than any repayment trick anyone will ever sell you. You’ve got this.
This is what I’m seeing after more than 30 years of helping people navigate debt, and I’m watching this SAVE transition closely because I’ve seen how these mid-stream rule changes trip people up. Take it as one informed perspective — but only you know your full situation and your numbers. Use it as input for your decision, not a directive. Nobody gets to tell you what to do with your money. Not me, not anyone.
If you know someone with student loans — a kid, a friend, a coworker who mentioned they were on SAVE — send them this today. A five-minute heads-up now could save them from a payment they never chose.
Frequently Asked Questions
What happens if I do nothing on the SAVE plan?
If you don’t choose a new repayment plan within 90 days of receiving your servicer’s notice, you’ll be automatically moved to the Standard Plan. That plan ignores your income and often means a higher monthly payment than you had under SAVE. Doing nothing is the most expensive option.
Is interest accruing on my SAVE forbearance?
Yes. According to the Department of Education’s SAVE forbearance guidance, interest has been accruing on SAVE-plan loans since August 2025, even though payments weren’t required. Check your current balance before choosing a new plan — it’s likely grown.
What is the RAP plan?
RAP (the Repayment Assistance Plan) is a new income-driven repayment option that became available July 1, 2026. It’s one of the plans SAVE borrowers can switch into. As with any plan, run it through the studentaid.gov Loan Simulator — a lower monthly payment doesn’t always mean a lower total cost.
Which repayment plan should I choose after SAVE?
It depends entirely on your income, your balance, and your goals (lowest monthly payment vs. lowest total cost vs. progress toward forgiveness). Use the free Loan Simulator at studentaid.gov to compare, and if you want free personalized help, New Yorkers can contact EDCAP at 888-614-5004.
Does this SAVE plan change affect borrowers outside New York?
Yes. The SAVE wind-down is a federal, court-ordered change that affects SAVE borrowers nationwide. The New York attorney general’s alert was directed at New Yorkers, but the 90-day deadline and the auto-enrollment into the Standard Plan apply to everyone on SAVE.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



