

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 9, 2026 • Every claim below links to a primary source.
The verdict: Myth. For most people who file Chapter 7 bankruptcy, the honest answer is you lose nothing — though if you own something valuable with a lot of unprotected equity, that’s the exception worth checking. Federal law sets aside a list of property — called exemptions — that creditors cannot touch: equity in your home, your car, your household goods, and, most importantly, your retirement accounts. 11 U.S.C. § 522 is the law that protects it.
I have to tell you about this one. It’s the single most common fear I’ve heard in over 30 years of doing this work: some version of “I can’t file bankruptcy — they’ll take my house and leave me with nothing.” It’s repeated in TV ads, in break rooms, and by the very companies that want to sell you a slower, more expensive “alternative.” Here’s the belief, stated the way people actually carry it:
Every weekday I read the enforcement actions, filings and fine print the outlets skip, and turn them into the one or two moves that actually improve your position — a rate worth moving for, a fee you can refuse, a deadline to beat before it costs you.
In the latest issue (Sep 11): You drive to the dealership to pick up the car. There is no car. There was never a car.
I write Your Money Actually most weekdays — actionable money information you will not find anywhere else, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.
“If you file bankruptcy, you lose your house, your car, and everything you own.”
I couldn’t let that keep scaring people away from the one tool that could actually give them a fresh start. If you believe it — and most people do — let me walk you through what the law actually says.
Well, Actually…
Here’s the part the scary version leaves out: bankruptcy was never designed to strip you bare. It was designed to give honest people a fresh start — and a fresh start doesn’t work if you walk out the door with no home, no car, and no way to get to a job. So the law does the opposite of what people fear. It draws a protective circle around a set of your property called exemptions, and everything inside that circle is off-limits to your creditors.
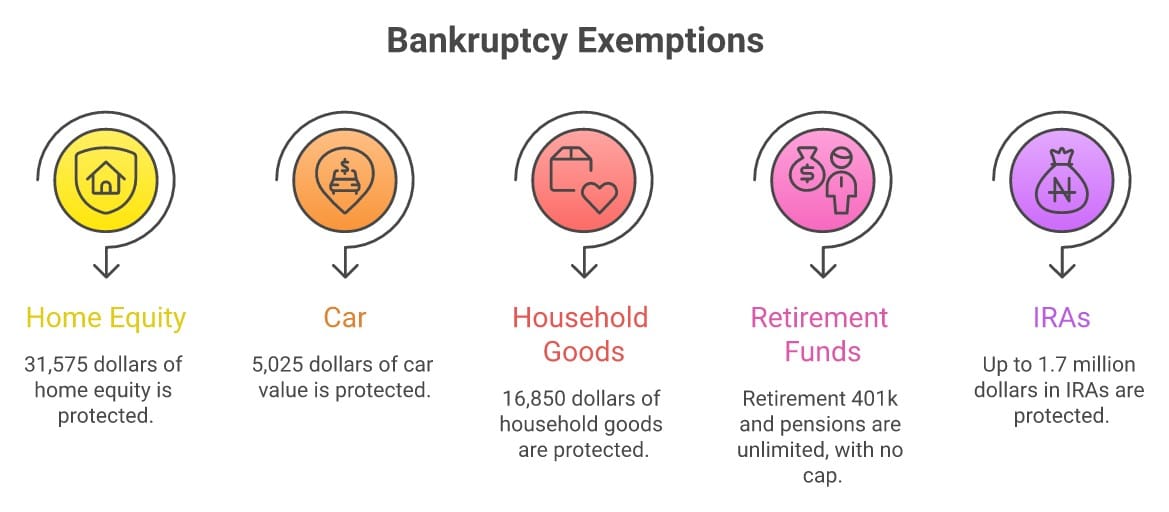
Under the federal exemptions in 11 U.S.C. § 522 (the amounts adjusted every three years; these took effect April 1, 2025), you can protect up to $31,575 of equity in your home, $5,025 in a car, $16,850 in household goods and furnishings, and a $1,675 “wildcard” you can apply to anything — plus up to $15,800 of any homestead exemption you didn’t use, which you can move onto other property. And notice these are equity figures. If you owe $280,000 on a house worth $300,000, your equity is $20,000 — comfortably inside the protection.
But the exemption that matters most to the most people is the one nobody talks about: your retirement. Your 401(k), 403(b), pension, and similar employer plans are protected with no dollar cap at all, and IRAs are protected up to more than $1.7 million. That’s the nest egg the fear-mongers imply you’ll lose — and it’s the one thing bankruptcy almost never touches. This is a big part of why I tell people that draining a 401(k) to avoid bankruptcy is usually exactly backwards.
The result: the overwhelming majority of Chapter 7 cases are what the courts call “no-asset” cases — the filer keeps everything, and unsecured debts like credit cards and medical bills are wiped out. Not most of it. Everything the exemptions cover.
If you file bankruptcy you lose your house, your car, and everything you own.
Federal bankruptcy exemptions protect your property. As of April 1, 2025: up to $31,575 of home equity, $5,025 in a vehicle, $16,850 in household goods, and a $1,675 wildcard (plus up to $15,800 of unused homestead). Retirement accounts — 401(k)s and pensions with no cap, IRAs up to $1,711,975 — are separately and broadly protected. Most Chapter 7 filers keep everything they own.
11 U.S.C. § 522 (exemptions), amounts effective April 1, 2025
The exemption amounts are the same everywhere, so the federal numbers are all that matter.
The federal figures above are the baseline, but many states require you to use their own exemption lists instead — and some are far more generous. Texas and Florida, for example, protect an unlimited amount of home equity (within acreage limits) — though a federal rule (11 U.S.C. § 522(p)) caps that protection at $214,000 if you acquired the home fewer than about 40 months (1,215 days) before filing, which stops people from moving to a generous state right before bankruptcy to shield a fortune. Because the rules vary by state and by how long you’ve owned the home, the exact dollars protecting your house depend on your situation, which is one reason to have a bankruptcy attorney run your specific numbers.
11 U.S.C. § 522(b) (states may opt out of the federal list); U.S. Courts — Bankruptcy Basics
Why You Were Told This
Follow the incentive. The debt-relief and debt-settlement industry sells products that compete directly with bankruptcy — programs that often cost more, take longer, and carry real risk. “You’ll lose everything” is a powerful sentence for steering a frightened person away from the free, court-supervised option and toward a paid one. It isn’t always malice; sometimes it’s just an old rumor nobody bothered to correct. But the effect is the same: fear keeps people trapped in debt they could have legally discharged, protecting the very assets they were afraid to lose. I ran a credit counseling organization for years, and I watched this fear cost people far more than bankruptcy ever would have.
What to Actually Do
- Add up your equity, not your value. What you’d actually lose is equity above the exemption — and if your home and car have loans, your equity is usually small. Most people are shocked to find they’re fully protected.
- Protect your retirement by knowing it’s already protected. Do not cash out a 401(k) or IRA to pay debts before you’ve talked to an attorney — those accounts are among the most protected things you own. See our research on how bankruptcy filers recover.
- Find out your state’s exemptions. Because roughly 35 states require you to use their own exemption lists instead of the federal ones, run your real numbers with a bankruptcy attorney. NACBA can help you find one, or talk to Damon Day for free about whether it’s even the right move for you.
- Check whether you qualify first. The Find Your Path quiz gives you a recommendation based on your actual numbers — including options that aren’t bankruptcy.
Steve’s Take
I filed bankruptcy in 1990, and I want you to hear this from someone who’s been on your side of it: I didn’t lose my future — I got it back. The fear that you’ll be left with nothing is the single most effective lie keeping good people stuck in debt they can’t pay. Bankruptcy is a legal protection your own government built for you, with a list of things it specifically will not take. Don’t let anyone weaponize your fear of losing everything to keep you from the one tool designed to make sure you don’t.
Frequently Asked Questions
If I file Chapter 7, will I lose my house?
Usually not. Bankruptcy only threatens the equity above your exemption. Federal law protects up to $31,575 of home equity (more in some states, and effectively unlimited in a few like Texas and Florida — though a federal $214,000 cap applies if you bought the home within about 40 months of filing), and if you have a mortgage your equity is often well under that. If you’re current on the mortgage and within the exemption, you keep the house.
Will they take my car?
Typically no. The federal motor-vehicle exemption protects $5,025 of equity in one vehicle, and the $1,675 wildcard can be stacked on top. If you owe money on the car and stay current, or your equity is modest, the car is generally safe.
Do I lose my 401(k) or retirement savings in bankruptcy?
Almost never. Employer retirement plans like 401(k)s, 403(b)s, and pensions are protected with no dollar cap, and IRAs are protected up to $1,711,975 under 11 U.S.C. § 522. This is why draining your retirement to avoid bankruptcy is usually the wrong move — you’re spending down protected money to pay debts that could be discharged.
What is a “no-asset” bankruptcy?
It’s the most common kind of Chapter 7 case: everything the filer owns fits within their exemptions, so there’s nothing for the trustee to sell, and the filer keeps it all while their qualifying debts are wiped out. For most consumers, this is what filing actually looks like.
Are the exemption amounts the same in every state?
No. The federal figures are a baseline, but roughly 35 states require you to use their own state exemption lists instead, some of which are more generous (and a few less). Because it varies, have an attorney check the numbers for where you live.
Could I actually lose something in bankruptcy?
It’s possible if you own something valuable with a lot of equity that no exemption covers — a paid-off vacation home, an expensive boat, a large stock account outside a retirement plan. But for the typical filer with a mortgage, a car loan, and a retirement account, the answer is almost always that you keep what you have.
This is one informed perspective from someone who’s spent 30 years watching how this plays out — not legal advice for your specific case. Only you can decide what’s right for your situation. Take this as input, look at your own numbers with an attorney, and make the call that serves your future.
The bottom line: Bankruptcy doesn’t take everything you own — the law specifically protects your home equity, your car, your household goods, and especially your retirement, and most filers keep it all. If someone you know is staying trapped in debt because they’re afraid they’ll lose everything, send them this page.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



