

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 10, 2026 • Every claim below links to a primary source.
The verdict: Half-true — and the half everyone gets wrong is costing people a fresh start. Federal student loans have always been dischargeable in bankruptcy if you can prove “undue hardship” — that part never changed. What changed is that since the Justice Department’s November 2022 guidance, the government is now directed to actively support discharge for borrowers who meet clear financial criteria, using a simple attestation form instead of a courtroom brawl. It is not automatic, and it is not easy — but “never” is flatly wrong.
Well, Actually…
Here’s the part that got buried. For decades, the conventional wisdom hardened into a flat “you can’t discharge student loans in bankruptcy, period.” It was never actually true — the law always allowed it if you could prove repaying the loans would be an “undue hardship.” (If a defaulted loan is already garnishing your paycheck while you weigh this, start with what to do right now — the garnishment runs on its own clock.) The problem was that proving it meant a brutal, expensive court fight (an “adversary proceeding”) where the government fought you tooth and nail, and the standard felt impossible. So attorneys stopped even trying, and “technically possible but practically hopeless” got flattened into “impossible” in the public mind.
Then, in November 2022, the Department of Justice and Department of Education rolled out new guidance that changed the practice — not the law. Now, instead of the government reflexively fighting every discharge, borrowers fill out a standardized attestation form about their income, expenses, and ability to repay. If your numbers meet the criteria, government attorneys are directed to recommend discharge rather than oppose it. The Education Department’s guidance to loan holders (updated August 5, 2024) spells this out. The undue-hardship legal standard is the same; the government simply stopped treating every struggling borrower like an adversary.
That’s the whole “well, actually.” The door was always there — the 2022 change unlocked it and posted a map to it. If you were told to never even try, you were told wrong.
“Student loans can never be discharged in bankruptcy — don’t even try.”
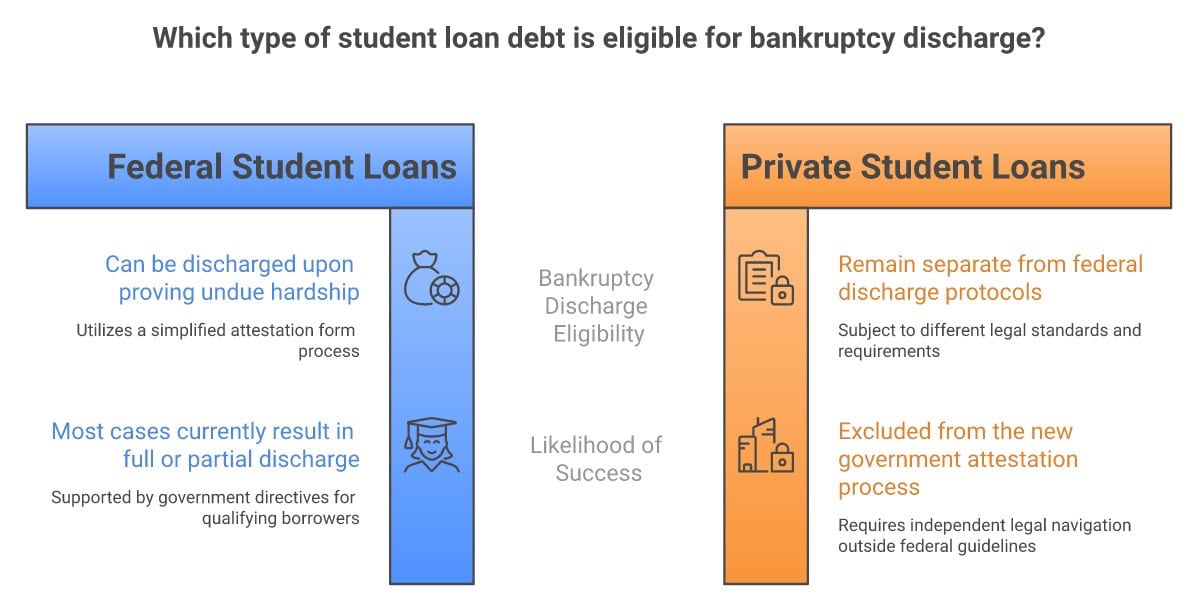
Federal student loans can be discharged in bankruptcy if you prove “undue hardship” — and they always could. That statutory standard did not change. What changed in November 2022 is that the government now uses an attestation-form process and is directed to support discharge for borrowers who meet objective financial criteria (a minimal standard of living, a persistent inability to repay, and a good-faith effort). It is not automatic — you still must file an adversary proceeding — but “never” is wrong.
U.S. Justice Department, Student Loan Guidance (November 2022)
“Even under the new rules, almost nobody actually wins.”
The opposite is true for those who file. Two figures matter, and they measure different things. When the government recommends discharge under the new process, the Justice Department reports courts grant a full or partial discharge in roughly 98% of those cases — a figure drawn from the government’s own reporting of decided cases, which independent researchers note may leave out neutral or dismissed cases. The independent, peer-reviewed count is more conservative because it uses a broader denominator that includes all case outcomes: about 87% of all adversary proceedings resolved in the first year ended in discharge — up from 61% before the 2022 guidance. The catch isn’t losing; it’s that, by that same study’s count, only about 1.5% of eligible borrowers even file. Almost nobody tries — not because they lose, but because they were told not to bother.
DOJ U.S. Trustee Program; Iuliano, “Bridging the Student Loan Bankruptcy Gap,” American Bankruptcy Law Journal, Vol. 99, Issue 3 (2025)
Why You Were Told This
Two things kept this myth alive. First, the old reality really was grim: before 2022, fighting for a discharge meant an expensive lawsuit against a government that opposed you by default, so attorneys honestly advised most people not to bother. That advice calcified into a blanket “you can’t.” Second, nobody has a financial incentive to tell you the door opened. The servicers, the collectors, and the debt-relief outfits all do better when you keep paying. A borrower who learns they might qualify for a bankruptcy discharge is a borrower who stops being a revenue stream. So the update — one of the most meaningful pro-consumer changes in years — traveled quietly while the old “never” kept getting repeated.
What to Actually Do
- Know which loans qualify. This process applies to federal student loans held by the Department of Education. Private student loans follow a separate path. A narrow subset of private loans that don’t fit the legal definition of a “qualified education loan” can be easier to discharge — but most private loans do qualify, so never assume yours is in the easier category without an attorney confirming it.
- Look honestly at the three criteria. Can you maintain a minimal standard of living if forced to repay? Is that likely to persist? Have you made a good-faith effort? If yes, you may be a real candidate. See how the discharge process actually works.
- Talk to a bankruptcy attorney who knows this process. The attestation form changed the game, but you still file an adversary proceeding — this is not a DIY moment. NACBA can help you find a bankruptcy attorney.
- Don’t let interest keep piling up while you wait. Interest keeps accruing until a discharge is granted — so if you qualify, moving sooner beats waiting.
Steve’s Take
I filed bankruptcy in 1990, so I know what it feels like to be told a door is bolted shut when it isn’t. For years I watched good people carry federal student loans into their sixties, convinced there was no legal way out, because “you can never discharge student loans” was repeated so often it felt like law. It never was. The 2022 change didn’t rewrite the statute — it just told the government to stop fighting people who genuinely can’t pay. If that’s you, please don’t let an outdated myth talk you out of a fresh start you may have every right to. Check the criteria. Ask the question. The worst answer is the one you never pursued because someone told you not to bother.
Frequently Asked Questions
Can I really discharge my federal student loans in bankruptcy?
Yes, if you can prove “undue hardship.” That has always been the law. Since the November 2022 DOJ guidance, the government uses an attestation form and is directed to support discharge for borrowers who meet the financial criteria — so it’s far more accessible than the old “impossible” reputation suggests. It is not automatic, and you still file an adversary proceeding.
Did the law change, or just the process?
Just the process. The statutory “undue hardship” standard for discharging student loans did not change. What changed is how the government evaluates and litigates these cases — the Department of Education guidance (updated August 5, 2024) directs holders to support discharge when the borrower’s attestation meets the criteria.
What are the criteria for undue hardship?
The attestation process looks at whether you can maintain a minimal standard of living while repaying, whether that inability is likely to persist for much of the repayment period, and whether you’ve made a good-faith effort to repay (courts know these three factors as the “Brunner test”). The DOJ guidance uses objective financial standards (including IRS living-expense standards) to assess this.
Does this cover my private student loans?
No. This process applies to federal student loans held by the Department of Education. Private student loans are treated separately in bankruptcy. A narrow subset of private loans that don’t meet the legal definition of a “qualified education loan” can actually be easier to discharge. I break down exactly what a “qualified education loan” means — using SoFi’s own SEC filing — here. But most private loans do qualify, and whether yours falls in the easier category is a technical legal call. Don’t assume it without an attorney reviewing your specific loans.
How often does this actually work?
For borrowers who pursue it, quite often — but be careful which number you’re reading. The Justice Department reports courts grant discharge in roughly 98% of cases where the government recommends it. A broader peer-reviewed study of all adversary proceedings filed in the new process’s first year found an overall success rate of about 87% (up from 61% before 2022). The real problem is how few eligible borrowers know to try — by that study’s count, only about 1.5% even file.
Do I need a lawyer to do this?
Practically, yes. Even with the simpler attestation form, discharging student loans requires filing an adversary proceeding within your bankruptcy case. This isn’t a do-it-yourself step. NACBA can help you find a bankruptcy attorney experienced with student loan discharge.
If I stopped trying years ago because someone said it was hopeless, is it too late?
Not necessarily. The 2022 change reopened this path for many people who were told to give up under the old regime. If your financial situation is genuinely difficult, it’s worth having a bankruptcy attorney look at your case under the current process rather than assuming the old “never” still applies.
This is one informed perspective after more than 30 years of watching people navigate exactly this. Take it as input for your decision, not instruction — only you know your full situation. Talk to a bankruptcy attorney, look at your real numbers, and make the choice that serves your future. Nobody gets to decide that for you.
The bottom line: “You can never discharge student loans in bankruptcy” is a myth — federal loans can be discharged for undue hardship, and since 2022 the government is directed to support discharge for borrowers who qualify. If someone you know is still carrying federal student loans they can’t afford because they were told there’s no way out, send them this — the door isn’t bolted shut, and it hasn’t been.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



