

Quick Answer: The FTC has alleged that RentGrow, Inc., a Massachusetts-based tenant-screening company, violated the Fair Credit Reporting Act by letting duplicate criminal and eviction records inflate applicants’ histories — making people look worse than they actually were. RentGrow agreed to pay $2.25 million to settle those allegations. The critical thing most people don’t know: your tenant screening report is a completely separate system from your credit report, it’s covered by the FCRA, and you have the right to see it, dispute it, and demand corrections.
Expert Context: I ran a nonprofit credit counseling organization and reviewed thousands of credit and consumer reports over more than 30 years. I’ve watched the same pattern repeat itself: people get denied housing, jobs, or credit because of errors in specialty consumer reports — and they have no idea the report even exists, let alone that they’re entitled to see it. Tenant screening is one of the most under-the-radar FCRA-covered systems I’ve seen weaponized against ordinary people, and this RentGrow settlement is a perfect example of why that blind spot costs real money.
The FTC announced in July 2026 that RentGrow, Inc. — a Massachusetts-based tenant-screening company that sells background and screening reports to landlords and property managers — will pay $2.25 million to settle federal allegations it violated the Fair Credit Reporting Act. The complaint was filed by the Department of Justice on referral from the FTC. According to the FTC, RentGrow allegedly knew about accuracy problems in its own system and didn’t fix them until regulators came knocking.
Key Terms Defined
Consumer Reporting Agency (CRA): Any company that assembles or evaluates consumer information for third parties to use in credit, employment, housing, or other eligibility decisions. Credit bureaus (Equifax, Experian, TransUnion) are CRAs. So are tenant-screening companies like RentGrow — all covered by the Fair Credit Reporting Act (15 U.S.C. § 1681 et seq.).
Adverse Action Notice: When a landlord or employer uses a consumer report to deny you housing or a job, federal law requires them to tell you — including the name, address, and phone number of the screening company, plus how to get your free copy. No notice? That’s a separate potential FCRA violation.
Specialty Consumer Report: A consumer report from a company other than the three major credit bureaus, covering a specific niche — tenant history, background checks, employment history, insurance claims, medical payments. Covered by the FCRA but tracked in separate systems your regular credit report won’t show.
What RentGrow Allegedly Did Wrong — and Why It Matters
According to the FTC’s press release, the complaint alleged three distinct problems:
1. Duplicate records made people look worse than they were. The FTC alleged RentGrow included the same criminal case or eviction proceeding multiple times in a single report — so a person with one eviction action in their past could appear to have two or three. Even when RentGrow’s own data vendor supplied the information correctly, the FTC alleged RentGrow displayed some proceedings multiple times. That’s not a small data glitch. A duplicated eviction on a tenant-screening report is the difference between getting an apartment and sleeping in your car.
2. Incomplete disclosures made disputes nearly impossible. When consumers exercised their FCRA right to see their own file, the FTC alleged RentGrow failed to disclose all the information in the report or all the sources of that data. If you can’t see where the information came from, you can’t effectively dispute it.
3. Landlords were told there was “no change” after disputes were actually resolved. This is the most infuriating one to me. According to the FTC’s allegations, after a consumer successfully disputed information and got it modified or deleted, RentGrow told the consumer it had notified the landlord of the change — but allegedly told the landlord there was no change. Think about what that means: you fight a wrong record, you win, and you never know the landlord still has the original bad information in hand.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
As Christopher Mufarrige, Director of the FTC’s Bureau of Consumer Protection, put it: “Inaccurate background reports can have a real impact on people by affecting their ability to obtain housing or a job.”
Framing Note: This is what the FTC alleged and what RentGrow agreed to settle — not a finding of guilt in court. Settlements are not admissions of wrongdoing. What I can tell you is that the FTC investigated, filed a federal complaint through the DOJ, and RentGrow agreed to pay $2.25 million. Draw your own conclusions about what that means.
The Thing Almost Nobody Knows: Tenant Screening Is a Separate System
Here’s where I want to slow down, because this is the part that gets people in trouble.
Everyone knows — or at least has been told — to check their credit report. You pull your Equifax, Experian, and TransUnion reports. You look for errors. Good. Do that. But credit report errors are only one piece of the puzzle.
Tenant-screening reports are a completely different system. They’re compiled by specialty consumer reporting agencies — companies like RentGrow, CoreLogic Rental Property Solutions (also marketed as SafeRent), TransUnion SmartMove, and RealPage, among others. These companies collect eviction records, criminal background data, rental payment history, and other information landlords use to screen applicants. Your standard free credit report at AnnualCreditReport.com won’t show you what’s in any of these files.
Over more than 30 years since I founded Debt Counselors of America in 1994, I’ve watched people lose good apartments — and get pushed into pricier, lower-quality housing — because of errors in specialty reports they didn’t know existed. Forced into extended-stay hotels or overpriced month-to-month leases, the cost spiral begins. Background check errors are not rare, and in the tenant-screening world, one duplicated eviction record can follow you from application to application because screening companies often pull from the same underlying data sources.
Your FCRA Rights on Tenant Screening Reports
The Fair Credit Reporting Act covers tenant-screening companies just like it covers credit bureaus. That means you have specific rights:
- Right to your file: You can request a copy of your report directly from any specialty CRA. Under the FCRA, the screening company must provide it. After an adverse action (a denial), you’re entitled to a free copy within 60 days of requesting it.
- Right to dispute errors: If the report contains inaccurate or incomplete information, you can dispute it in writing. The company must investigate and correct or delete information it cannot verify.
- Right to know who screened you: If you were denied housing or a job in the last two years, the landlord or employer was required by the FCRA to send you an adverse action notice naming the screening company and explaining how to get your report. If they didn’t send it, that itself may be a FCRA violation — and you may have a right to sue.
Also worth knowing: errors tend to propagate. If one company has a duplicated criminal record on you, there’s a real chance another company’s database has the same bad data. The underlying public records sources are often shared. Checking more than one is not paranoid — it’s practical.
I’d also point you toward the FCRA’s right to dispute errors as a parallel process to fighting a background check denial — the legal framework is nearly identical whether it’s housing or employment.
What to Do Right Now — Concrete Steps
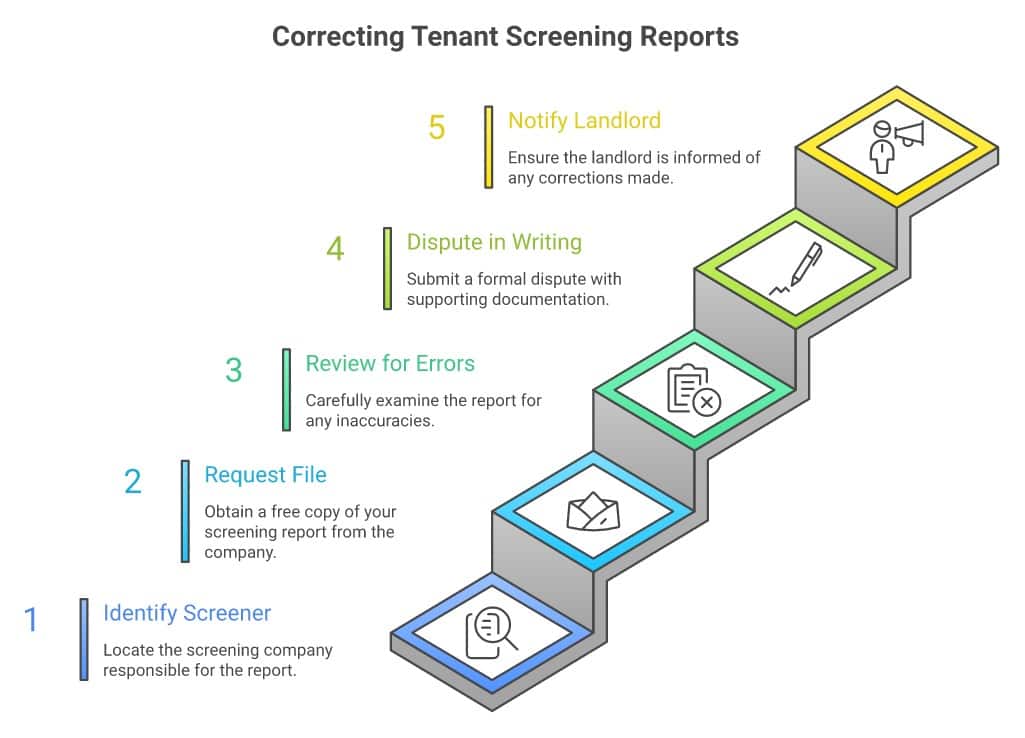
Step 1: Find out which company screened you. If you were recently denied a rental, pull out every piece of paper you got from the landlord. The adverse action notice should name the screening company. If you didn’t get one — contact the property manager and ask directly. Note the company name, address, and contact information.
Step 2: Request your file. Contact the screening company directly and request a copy of your consumer report. Common companies to check include RentGrow (now under the settlement order), CoreLogic Rental Property Solutions/SafeRent, TransUnion SmartMove, and RealPage. These are names to search for on your adverse action notice — I’m listing them as examples of where you might need to look, not as accusations against any of them.
Step 3: Review it carefully for duplicate entries. Look for any eviction or criminal record listed more than once. Even if you have a real eviction in your history, it should appear once — not two or three times. Also look for records that belong to someone else with a similar name, which is a known problem with tenant-screening databases.
Step 4: Dispute in writing with documentation. Do not call — write. Send a dispute letter by certified mail, return receipt requested. Attach copies (not originals) of any documents proving the error: court records, dismissal orders, settlement agreements. The same discipline that applies to disputing credit report errors applies here.
Step 5: If something smells wrong, consult a consumer attorney. If you were denied housing and never received an adverse action notice, or if a screening company confirmed a dispute was resolved but you discover the landlord received different information, you may have grounds for an FCRA lawsuit. Many consumer rights attorneys take FCRA cases on contingency — meaning no money out of pocket for you. The National Association of Consumer Advocates (NACA) at consumeradvocates.org maintains a directory of attorneys who handle these cases. If your situation involves a background check for employment specifically, I’ve covered the FCRA enforcement options available when a CRA gets it wrong.
The Claim: “My credit report is clean, so I won’t have any problem renting.”
The Reality: Your credit report and your tenant-screening report are separate systems. A clean credit score does nothing to fix a duplicated eviction record in a specialty screening database. I’ve seen people with 750 credit scores get denied rentals because of errors in a tenant-screening file they didn’t know existed.
Key Takeaways
- The FTC alleged RentGrow included duplicate criminal and eviction records in reports — making applicants look worse than they were — and agreed to a $2.25 million settlement.
- No consumer money is available from this settlement — the $2.25M is a civil penalty.
- Tenant-screening reports are a separate FCRA-covered system from your credit report — you have the same right to see and dispute them.
- If you were denied housing or a job, you should have received an adverse action notice naming the screening company. No notice = possible FCRA violation.
- Errors in screening databases get copied across companies — check the specific company named on your denial, not just one.
- FCRA disputes must be in writing, with documentation, sent by certified mail.
The Bottom Line
If you’ve been denied a rental — or if you’re about to apply for one — you need to know that your credit report is not the only consumer file that can sink your application. Tenant-screening reports are a shadow system most people don’t know exists, covered by the same federal law as your credit report, and just as prone to errors. The RentGrow settlement is a reminder that these companies are regulated, that they do make mistakes, and that those mistakes have real consequences for where people sleep at night. You have the right to see your file. You have the right to dispute what’s wrong. And if a landlord denied you housing without giving you the legally required notice, you may have grounds to do more than just dispute. The information is out there — debt is math wrapped in emotion, and the math here strongly favors knowing what’s in your file before anyone else does.
Related: If you’re dealing with a denied rental application AND debt collectors at the same time, here’s how to protect your housing first.
Frequently Asked Questions
Do I get any money from the RentGrow FTC settlement?
No. The $2.25 million RentGrow agreed to pay goes to the federal government as a civil penalty, not to consumers. This settlement does not include a consumer redress fund, and there is no claim to file. The actionable move here is not to file a claim — it’s to pull and check your own tenant-screening reports and dispute any errors you find.
How do I find out which company screened me when I applied for an apartment?
Under the Fair Credit Reporting Act, if a landlord used a consumer report to deny you housing, they were required to send you an adverse action notice. That notice must identify the consumer reporting agency by name, address, and phone number. If you did not receive an adverse action notice and were denied, the landlord may have violated the FCRA. Check your email and any physical mail from the property, and follow up in writing with the landlord or property management company asking which company they used.
Is a tenant-screening report the same as a credit report?
No. They are separate systems. Your credit report is maintained by the three major bureaus — Equifax, Experian, and TransUnion — and reflects your credit history. A tenant-screening report is compiled by specialty consumer reporting agencies like RentGrow, CoreLogic/SafeRent, TransUnion SmartMove, or RealPage, and typically includes eviction records, criminal background data, and rental payment history. You cannot see your tenant-screening file on AnnualCreditReport.com — you have to request it directly from whichever company your landlord used.
How do I dispute an error on a tenant-screening report?
Dispute in writing — not by phone. Send a certified letter (return receipt requested) to the screening company’s dispute address, describe the error clearly, and attach copies of any documents that support your dispute (court records, dismissal orders, proof of identity). The FCRA requires the company to investigate within 30 days and correct or delete information it cannot verify. Keep copies of everything. If the company fails to investigate or correct a legitimate error, you may have grounds for an FCRA lawsuit — an attorney at consumeradvocates.org (NACA) can evaluate your situation.
What if the landlord didn’t give me an adverse action notice?
Failing to provide a required adverse action notice is itself a potential FCRA violation. The landlord was required to tell you in writing that a consumer report was used in the decision, which company provided it, and that you have the right to get a free copy. If you were denied and received nothing, document that fact. Contact a consumer rights attorney through the National Association of Consumer Advocates (NACA) for an evaluation — many attorneys take FCRA cases on contingency, so the consultation costs you nothing out of pocket.
If you found this useful, please share it with anyone apartment-hunting right now — or anyone who’s been turned down for a rental and doesn’t know why. The information in your screening file can change everything about that outcome, and most people have no idea they can even access it.
A note before you go: nothing here is legal advice and I’m not your lawyer. I’m sharing information so you can make an informed decision and walk into any conversation — with a landlord, an attorney, or a screening company — knowing your rights. What you do with that is up to you.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Claiming money you are owed is one good day. What you do over the following year is what actually changes your position.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



