

Written by Steve Rhode, consumer debt expert since 1994 • Last updated July 15, 2026
Quick Answer: A utility shutoff notice is serious — but you have real options right now, and most people don’t know about them. Federal law funds LIHEAP (Low Income Home Energy Assistance Program) for exactly this crisis: apply today and some states require the utility to hold off while your application is pending (many do not, so get any hold in writing). If anyone in your household depends on electrically powered medical equipment, a doctor’s letter can legally block the disconnection. Cold-climate states ban wintertime shutoffs. Your state’s Public Utility Commission (PUC) has complaint and hold powers. You have more leverage than the shutoff notice implies — use it before the crew shows up.
What Just Happened: How the Shutoff Process Works
Utilities don’t flip a switch the moment you miss a payment. There’s a legal sequence — and knowing where you are in it changes everything about your options.
It usually goes like this: you fall behind, the utility applies late charges, a past-due balance accumulates. When that balance crosses a threshold, the utility sends a written disconnection notice. Depending on your state’s Public Utility Commission rules, that notice is often 10 to 30 days — but a few states set no minimum and allow very short or even same-day cutoff, so never count on having a month. After disconnection, reconnection usually requires paying the full past-due balance, late fees, and sometimes a security deposit — which is how a manageable situation becomes an expensive one.
The key fact most people don’t realize: that notice is not the end of the road. It is the start of a window where federal protections, state rules, and utility assistance programs are designed to intervene. The disconnection hasn’t happened yet. The window is open. Use it.
If you’re also struggling with credit card bills, medical debt, or other debts alongside this, the job loss and debt crisis guide covers the broader picture. But if keeping your lights on is the crisis right now, this guide is your 48-hour plan.
The Mistake You’re About to Make: Borrowing from a payday lender, title loan company, or “utility assistance” scammer to pay the bill before you have called the utility and applied for LIHEAP. Every year, people in this exact panic hand triple-digit-interest money to a lender to buy one more month — and end up owing two crises instead of one. The federal LIHEAP program exists precisely to cover this. Your utility almost certainly has a deferred payment plan that doesn’t cost you a dime in interest. The state PUC has complaint authority that can halt disconnection during investigation. None of those levers cost you interest. The payday lender costs you everything. Call the utility first. Apply for LIHEAP second. Then and only then, if those doors are closed, talk about borrowing.
Your Options Right Now
What to Do in the Next 48 Hours
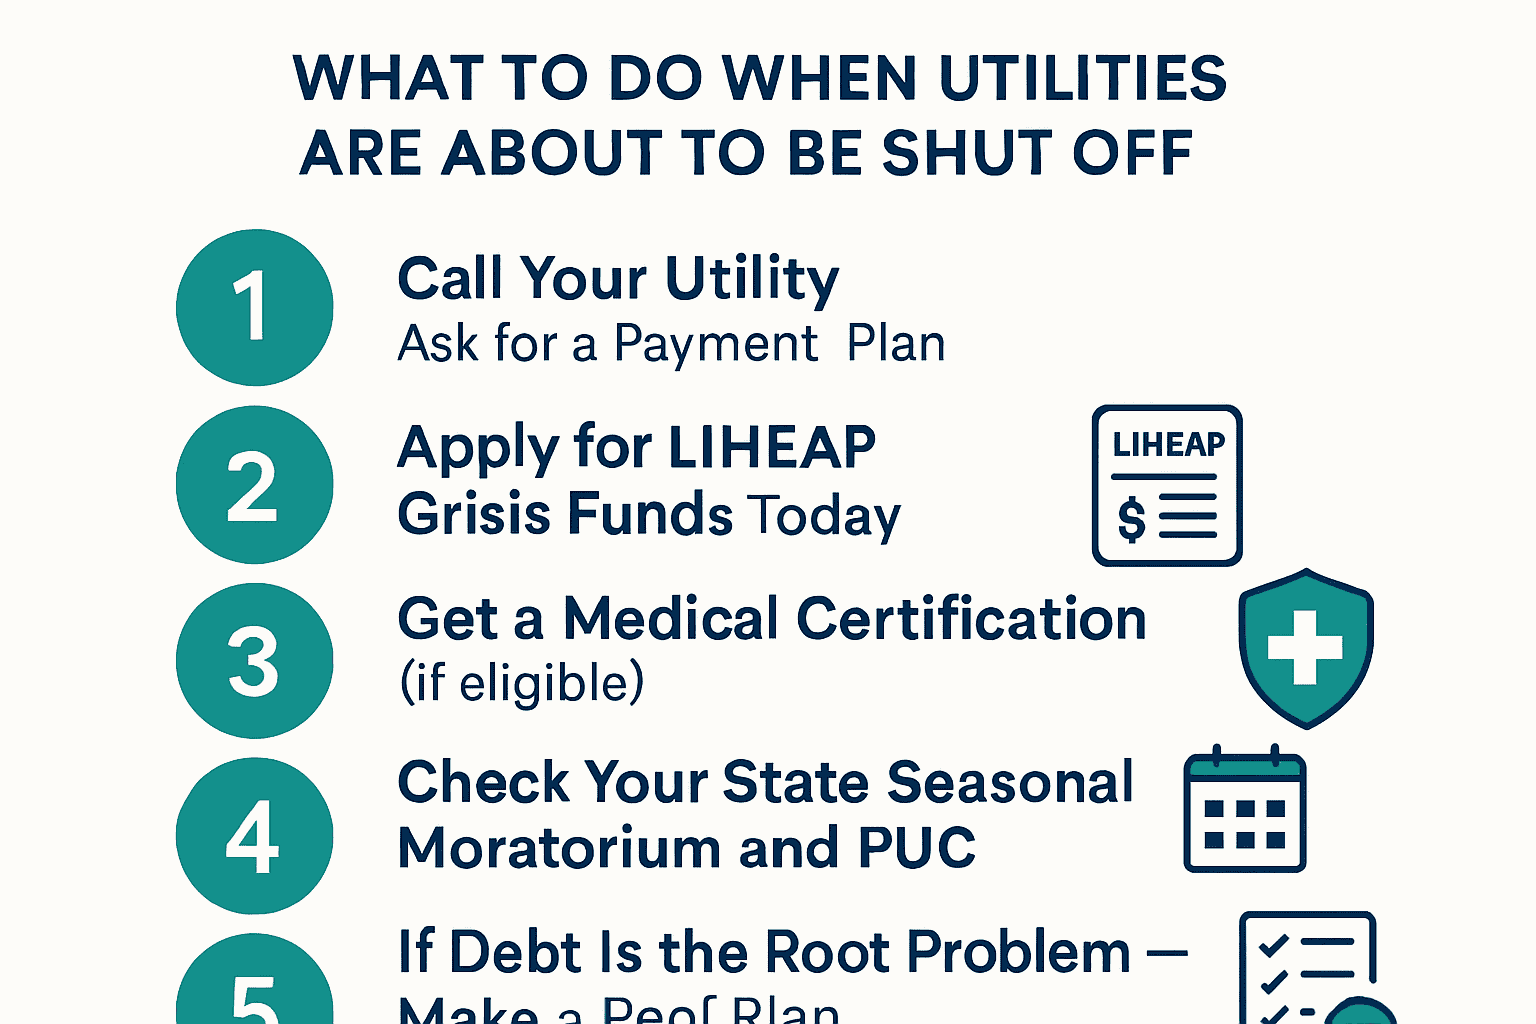
- Call your utility today and ask for a deferred payment agreement (DPA). Most utilities are required by their state PUC to offer a payment plan before disconnecting residential customers. Ask specifically for a “deferred payment agreement” or “payment arrangement.” Get any agreement confirmed in writing (ask for an email or letter). While a plan is in place and you’re current on it, disconnection is typically suspended.
- Apply for LIHEAP crisis assistance today — and tell the utility you’ve applied. LIHEAP is a federal program that provides direct payment assistance when you face a shutoff. Income limits are generous: the program serves households at the GREATER of 150% of the federal poverty guideline OR 60% of state median income, per ACF.gov. Critically, some states require the utility to delay disconnection while a LIHEAP application is pending — but many do not, so do not assume it. Tell the utility in writing the moment you apply, and get their confirmation of any hold in writing. Find your state’s LIHEAP office at liheapch.acf.hhs.gov. Tell your utility the moment you apply — that call may freeze the disconnection clock.
- If anyone in your household depends on electrically powered medical equipment or has a serious health condition, get a doctor’s letter immediately. Nearly every state has a medical-necessity protection that blocks (or at least delays) utility disconnection when a household member’s health or life is at risk. Ask your doctor for a letter stating the medical necessity, or ask your utility for the official medical-certification form. Submit it to the utility in writing, and keep a copy. This is the single fastest hard stop available to qualifying households — it typically suspends disconnection for 30 to 60 days (renewable, usually annually). See Step 4 below for more detail.
- Check whether your state’s seasonal moratorium applies. Many cold-climate states prohibit residential utility disconnection roughly from November 15 through March 31 — dates and conditions vary by state. Some hot-weather states restrict summer disconnections during extreme heat — Arizona’s major utilities, for example, observe a flat June 1–October 15 shutoff ban, while Texas ties its protection to National Weather Service heat alerts. The rules vary by state and even by utility, so confirm yours. If you’re in a protected period, disconnection may be illegal right now regardless of what the notice says. Call your state PUC to confirm, or visit their website. Find your state’s commission through the LIHEAP Clearinghouse state-by-state pages. Do NOT just assume you’re covered — rules vary widely and have exceptions.
- If the utility violated its own rules, file a complaint with your state PUC. If you didn’t receive the required written notice, the utility refused to offer a payment plan, tried to disconnect during a protected moratorium period, or ignored your pending LIHEAP application, that may violate your state’s utility service rules. Filing a formal PUC complaint often triggers a hold on disconnection while the complaint is investigated. Most state PUC websites have an online complaint form. This is not a nuclear option — it is a routine protection the system built in for exactly these situations.
- If debt is the real root problem, make an honest plan — not a temporary patch. If this shutoff is happening because overall debt has consumed your income, then paying the utility bill just moves the crisis one month forward. A real plan means looking at all your options. Talk to Damon Day for an honest read on whether a payment plan, Chapter 7 bankruptcy, or another path fits your numbers. Bankruptcy’s automatic stay under 11 U.S.C. § 362 stops a pre-petition utility disconnection; a utility can still require a deposit for future service, but the court can reduce it to a reasonable amount — so if you’re drowning in overall debt, bankruptcy may solve more than just the utility crisis.
Free Tool — Benefits & Free Money Finder: There may be government programs, creditor hardship options, or nonprofit grants available to you. The free Benefits Finder personalizes results by state and situation — SNAP, Medicaid, LIHEAP, and more. Find Your Benefits →
How to Actually Stop It — Your Paths
- LIHEAP crisis grant (fastest financial lever). Apply through your state office at liheapch.acf.hhs.gov. Congress funded LIHEAP at about $4 billion for fiscal year 2026. Federal law requires states to hold some crisis funds in reserve until at least March 15 each year — but many states run out well before then, so apply immediately rather than assuming money is still there each year. The grant pays the utility directly — you don’t see or handle the money. Income limit: the GREATER of 150% of the federal poverty guideline OR 60% of your state’s median income, per ACF.gov. The moment you apply and notify your utility, some states require the utility to hold off (many do not — get any hold in writing).
- Medical certification (fastest legal hard stop). If a household member depends on electrically powered medical equipment — oxygen concentrator, home dialysis, ventilator, feeding pump — or if shutoff would pose a serious health threat, nearly every state provides some medical-necessity protection (the duration varies widely by state — from around 10 days to, in a few states, effectively indefinite if you keep a payment plan — and in most states it delays disconnection rather than permanently preventing it, so check your state’s public utility commission rules). Get your doctor to complete the utility’s medical-certification form or write a letter. File it in writing with the utility. Disconnection is typically blocked for 30 to 60 days and can usually be renewed annually. This is the single fastest non-financial block for qualifying households.
- Payment plan / deferred payment agreement. Call your utility and ask explicitly for a payment arrangement before the shutoff date. Most states require utilities to offer one. Structure it so that monthly installments cover both current charges and part of the past-due balance. Get the agreement in writing. Missing a payment plan installment can restart the disconnection clock, so be realistic about what you can sustain.
- Seasonal moratorium. Many cold-climate states ban winter disconnections (approximately Nov 15–Mar 31, with state-by-state variation). Hot-weather states like Texas and Arizona restrict summer shutoffs at extreme temperatures. Check your state’s PUC website or the LIHEAP Clearinghouse for your state’s current rules. If you’re in a protected period, tell the utility — in writing.
- PUC complaint. If the utility skipped required notice, refused a payment plan, or tried to disconnect during a legally protected period, file a complaint with your state Public Utility Commission. Filing triggers a review and often an automatic hold on disconnection. Most state PUC websites have an online complaint form. You can also reach the CFPB at consumerfinance.gov/complaint if a financing arrangement (like a utility deposit financing scheme) is involved.
- What won’t work: a payday or title loan to cover it. Borrowing at triple-digit interest to pay a utility bill just shifts the crisis forward by 30 days while adding debt to the pile. The math never works. The utility has a federally supported assistance program and a PUC-regulated payment plan system. Use those before any high-cost borrowing. If debt is the real problem, a loan deepens it.
The Legal Limits — What Federal Law and Common State Rules Require
150% FPG
LIHEAP income limit — the GREATER of 150% of the federal poverty guideline OR 60% of state median income (ACF.gov)
$4B
FY2026 LIHEAP appropriation for home energy assistance nationally (about $4.03 billion, fully disbursed by April 2026) (ACF.gov)
10–30 days
Typical written disconnection notice window before shutoff (varies by state PUC — check yours)
Nov 15–Mar 31
Typical cold-weather moratorium window in cold-climate states (dates vary — many states differ)
The table below shows the federal baseline and how some states differ. It is illustrative — state rules change frequently. Always verify your state’s current rules at your state’s LIHEAP office or PUC website before assuming a protection applies to you.
Federal / Common Baseline
- LIHEAP crisis assistance available through at least March 15 each year
- Income limit: greater of 150% FPG or 60% state median income
- Medical-necessity protection in nearly every state (form and duration vary; check your state)
- Bankruptcy automatic stay (11 U.S.C. § 362) stops pre-petition disconnection instantly
- Written disconnection notice required before shutoff
- Payment plan / DPA required (most states)
Cold-Weather States (examples)
- Winter moratoriums typically Nov 15–Mar 31 (Illinois, Michigan, Minnesota, others)
- Some states require utilities to offer budget billing and arrearage management plans
- Medical cert blocks disconnection year-round
- Moratorium dates and income thresholds vary — never assume one state’s rules match another’s
Hot-Weather States (examples)
- Texas: PUC rules restrict disconnection when heat index is fthe National Weather Service issues a Heat Advisory for your county — the protection runs that day plus the next two calendar days; check your utility’s tariff
- Arizona: utilities typically ban disconnection June 1–Oct 15 if temperature exceeds 105°F
- Medical cert available year-round in both states
- Rules vary by utility within the same state — verify with your specific provider
These examples are illustrative only. State PUC rules change. For your state’s current disconnection rules, contact your state PUC or the LIHEAP Clearinghouse.
Key Action Links:
- LIHEAP: Find your state office at liheapch.acf.hhs.gov — apply today if facing shutoff
- CFPB: File a complaint at consumerfinance.gov/complaint if a financing or loan product is involved
- State Attorney General: usa.gov/state-attorney-general for consumer complaints against the utility
- Free Legal Aid: lsc.gov connects you to federally funded legal aid programs at no cost
- State PUC Complaint: Search “[your state] Public Utility Commission complaint” for the online form — most states have one and filing often triggers a disconnection hold
- Bankruptcy Attorney: nacba.org if you need to stop disconnection plus handle overall debt
Steve’s Take
I filed bankruptcy in 1990. I know what it’s like to sit in a house wondering if the lights are going to go out — the shame, the helplessness, the certainty that you’ve failed. Let me tell you what I know from more than 30 years of helping people through this: a utility shutoff notice is not a moral verdict. It’s a math problem. And math problems have solutions. The federal government put roughly $4 billion into LIHEAP this year specifically for people in your situation. Your state built a medical-certification process specifically for this. Your utility is required — in most states, by law — to offer you a payment plan. None of those protections know you’re embarrassed. They just work. Make the calls. Use the tools. And if the real problem is that overall debt has made it impossible to keep up, that’s a separate conversation — and Damon Day can have it with you for free. You are not your debt. This is a crisis with exits.
If a hospital stay is why the utility bill (and everything else) fell behind, see the complete guide to debts that piled up during a hospital stay.
Frequently Asked Questions
My power is being shut off tomorrow — can I stop it?
Possibly, yes — but you need to act today. Call your utility right now and ask for an emergency payment agreement. At the same time, contact your state’s LIHEAP crisis office (find it at liheapch.acf.hhs.gov) — many states allow same-day or next-day emergency crisis assistance that pays the utility directly and halts disconnection. If anyone in your household has a medical condition that depends on electricity, get a doctor’s letter or the utility’s medical-certification form submitted today. And call your state’s PUC emergency line — if the utility is trying to disconnect you during a protected period or without proper notice, the PUC can issue an emergency hold. Do not wait until tomorrow morning.
Can they shut off my electricity in winter?
It depends entirely on your state. Many cold-climate states ban winter disconnections during a moratorium period — typically something like November 15 through March 31, though dates, conditions, and exceptions vary significantly by state. Some states protect only low-income households or households with medical conditions during winter months; others apply the moratorium broadly. There is no single federal winter-shutoff ban. Check your state’s Public Utility Commission website or call them directly. You can also find state-specific information through the LIHEAP Clearinghouse. Do not assume you’re protected without confirming — the consequences of a wrong assumption are real.
Does LIHEAP really stop a shutoff?
Yes — in two ways. First, LIHEAP crisis assistance pays the utility directly, which eliminates the past-due balance that triggered the shutoff notice. Second, and more immediately powerful: some states require the utility to hold off disconnection while a LIHEAP application is pending (many do not, so confirm any hold in writing). That means the act of applying — not just receiving the grant — can stop the clock. You must notify your utility that you have applied (ask for their written confirmation that the disconnection is on hold). LIHEAP is a federal program administered state-by-state through the ACF. Apply at liheapch.acf.hhs.gov.
I’m on disability and my medical equipment runs on electricity — am I protected?
In nearly every state, yes — there is a medical-necessity protection that blocks or delays utility disconnection when a household member depends on electrically powered medical equipment (oxygen concentrators, home dialysis machines, ventilators, infusion pumps, and similar equipment) or when shutoff would create a serious health threat. The protection is available year-round — not just in winter. Contact your doctor today and ask them to complete your utility’s medical-certification form (ask the utility for their specific form) or write a letter. Submit it to the utility in writing and keep a copy. The disconnection hold is typically for 30 to 60 days and can usually be renewed annually with an updated doctor’s certification. Get this documentation submitted before the shutoff date.
What if I can’t afford to pay even a partial payment?
There are two parallel tracks that don’t require you to come up with money immediately. First, LIHEAP crisis assistance is a grant — not a loan. You don’t repay it. Apply at liheapch.acf.hhs.gov today. Second, your utility’s deferred payment agreement structures repayment of the past-due balance over time, typically 3 to 12 months, while you stay current on new charges going forward. If neither option resolves the situation because debt has consumed your entire income, that’s the real problem — and that’s a different conversation about your overall financial picture. The can’t-make-payments crisis guide covers that bigger picture. For immediate utility help: LIHEAP first, payment plan second, and get a medical certification if anyone qualifies.
My utility skipped the required notice — what can I do?
A utility that disconnects service without providing the required written notice has likely violated your state’s PUC service rules. File a complaint with your state Public Utility Commission immediately — most states have online complaint forms and emergency contact numbers. Filing a complaint often triggers an automatic hold on disconnection while the complaint is investigated, and if service has already been cut, it can require reconnection. You can also contact your state attorney general’s consumer protection office at usa.gov/state-attorney-general. If you can’t afford legal help, LSC.gov connects you to free legal aid programs.
Will filing bankruptcy stop a utility shutoff?
Yes — and it does more than just stop the shutoff. Under 11 U.S.C. § 362, the automatic stay takes effect the instant you file a bankruptcy petition, halting all disconnection actions for pre-petition unpaid utility bills. Beyond the stay, under 11 U.S.C. § 366, a utility cannot cut you off solely because of the old pre-petition debt — but there is a catch you must know: § 366(b) gives the utility the right to demand “adequate assurance of payment” for future service, usually a deposit, within 20 days of filing. If you do not provide it, the utility can legally disconnect you even in bankruptcy. So bankruptcy buys you time and leverage on the old balance — it does not give you free ongoing service. A bankruptcy attorney can ask the court to reduce that deposit to a reasonable amount, which is one more reason to talk to one before you rely on this. The utility may require a security deposit as assurance of future payment, but that deposit is capped — it must be “adequate assurance” of payment, not an unreasonable barrier. If you’re facing a utility shutoff as part of a broader debt crisis — multiple bills you can’t pay, collectors calling, nothing left over — bankruptcy may solve more than just this month’s utility bill. Find a bankruptcy attorney through nacba.org.
Is there help for water bills too, or just gas and electric?
LIHEAP’s primary focus is home heating and cooling energy costs — electricity and gas. Water bills are generally not covered by LIHEAP directly, though some states have used LIHEAP flexibility to address energy-related water heating costs. For water shutoffs specifically, your best paths are: (1) a payment plan with your water utility (most municipal water systems have them), (2) your state or local assistance programs (some states have separate low-income water assistance programs — check with your state health department or local community action agency), and (3) your state PUC or local utility board, which regulates water disconnection procedures in many jurisdictions. The water bill assistance guide on this site covers state-by-state water assistance programs in more detail.
One more thing — everything I share here is based on more than 30 years of helping people through exactly this kind of crisis. But my advice is input for your decision, not the decision itself. Only you know your full situation. Make the calls, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Utility regulations and assistance programs vary significantly by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A utility shutoff notice opens a window — not a wall. LIHEAP crisis grants pay utilities directly, and applying often freezes the disconnection clock while the application is processed. Medical-necessity certifications block shutoff immediately for qualifying households. State seasonal moratoriums may make disconnection illegal right now. And if the real issue is debt that has consumed your income, bankruptcy’s automatic stay stops a pre-petition shutoff instantly, though the utility can still ask for a reasonable deposit for future service. Use the Find Your Path quiz to see what makes sense for your full picture. The window is open — act before it closes.
The Bottom Line
You are not a bad person. You are a person facing a math problem — one that a federal assistance program, a medical certification process, a utility payment plan system, and a body of state utility law were all specifically designed to help solve. The people who make it through situations like this are not the ones who had more money. They are the ones who made the calls. Called the utility. Applied for LIHEAP. Got the doctor’s letter. Filed the PUC complaint. If someone you know is sitting in the dark right now wondering what to do, send them this page. Finding out you have options is the first step to using them. Start with LIHEAP or the all your debt relief options page to see what’s realistic for your situation.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



