

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 20, 2026 • Every claim below links to a primary source.
The verdict: MYTH. Paying only the minimum is not “fine” — it is, by design, the slowest and most expensive way to pay back what you owe. The math is so damaging that federal law (12 CFR 1026.7(b)(12)) requires every credit card issuer to print a bold “Minimum Payment Warning” on your statement showing exactly how many years and how many dollars the minimum-only path will cost you. Your card company already knows. Now you will too.
Well, Actually…
Here’s the part nobody tells you: credit card minimum payments are not calculated to help you get out of debt. They are calculated to keep you in debt for as long as possible while you pay the maximum amount of interest. That is not an opinion — it is the business model. The minimum payment formula varies by issuer — check your own cardmember agreement — but a common one is roughly 1% of your balance plus that month’s finance charge (often with a small floor, like $25 to $35). The result is that almost all of your payment covers interest. You make a payment, you feel responsible, and yet your balance barely budges.
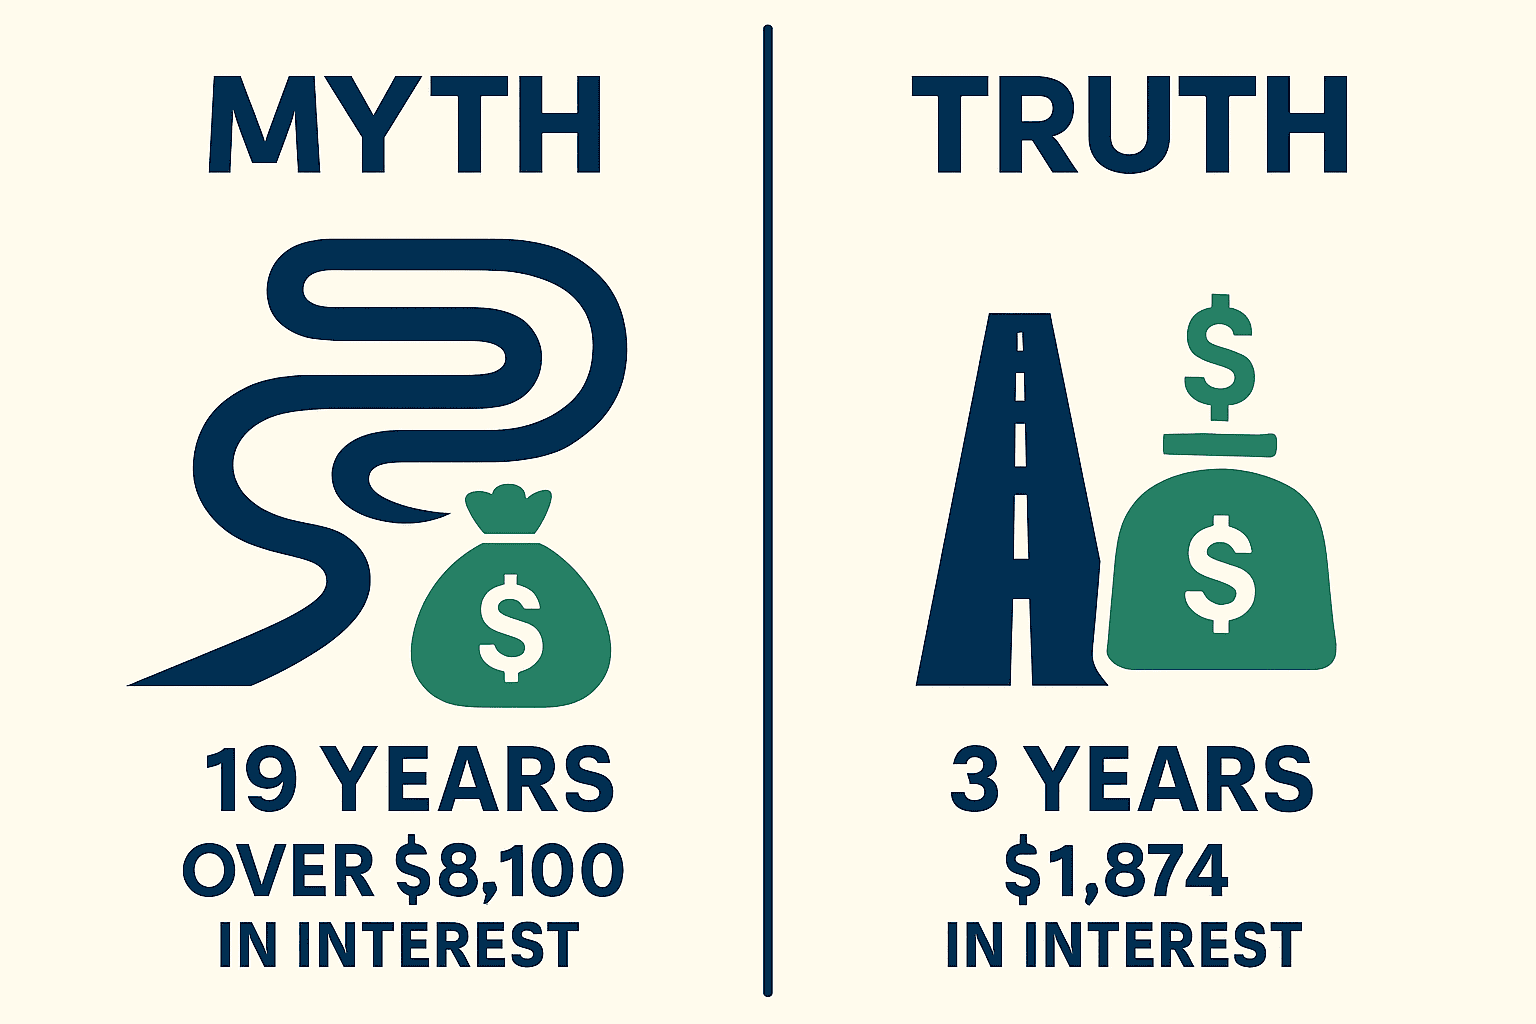
Let me show you what that actually looks like on a real number. Take a $5,000 credit card balance at a 22% annual percentage rate — common today, with many cards running higher. If you make only the minimum payment every single month, it takes roughly 19 years to pay off that $5,000, and you’ll pay approximately $8,100 in interest — more than you originally borrowed. Meanwhile, if you paid a fixed $191 a month (the 36-month payoff amount that federal law requires issuers to calculate and show you), you’d be debt-free in three years and pay only $1,874 in interest. The difference: $6,226 saved. That is not a rounding error. That is a used car, a home repair, six months of groceries.
Congress knew the math was this damaging. The CARD Act of 2009 — officially the Credit Card Accountability Responsibility and Disclosure Act — responded by requiring every credit card issuer to print a mandatory warning box on each periodic statement. Under 12 CFR § 1026.7(b)(12), that box must include, in bold: “Minimum Payment Warning: If you make only the minimum payment each period, you will pay more in interest and it will take you longer to pay off your balance.” It then must show how long it will take to pay off the balance if you make only the minimum payment, the total cost estimate, a side-by-side comparison showing the monthly payment and total cost to pay the balance off in 36 months instead, and a toll-free number where you can get information about credit counseling. Congress essentially required card issuers to put the anti-minimum-payment argument directly on the statement. That should tell you something.
Paying just the minimum payment is a fine, responsible way to manage your credit card.
Minimum payments are calibrated to maximize the card issuer’s interest income, not to help you pay off your balance. On a $5,000 balance at 22% APR, paying the minimum means ~19 years of payments and over $8,100 in interest — more than the original balance itself. The math is so unfavorable that federal law now requires card companies to print a bold warning box on every statement spelling this out, and to show you the 36-month alternative. (12 CFR § 1026.7(b)(12), enacted by the CARD Act of 2009.)
Why You Were Told This
There are two reasons this belief persists, and neither is accidental. First, the word “minimum” sounds like the floor — the least you’re supposed to do. People reasonably read it as “the minimum acceptable payment” the same way “minimum wage” means you’re legally covered. But the minimum payment on a credit card is not the minimum acceptable amount; it is the minimum the issuer is legally required to accept. It was not designed for your benefit.
Second, the math is invisible. You never get a bill saying “You’re on track to pay $8,100 in interest over the next 19 years.” That number only appears in the required warning box, and most people scan right past it. The credit card industry survived for decades on exactly that invisibility — which is why Congress had to mandate the disclosure. Before the CARD Act of 2009, there was no federal requirement to show you how long minimum payments would take. The law changed because the harm was real and documented, and the industry had no incentive to show you the honest math on its own.
I am not saying card companies are evil. They are businesses making rational choices that happen to cost you money. The solution is the same as it always is with debt: understand the math. Once you see it, you can decide what to do with it.
What to Actually Do
- Read the warning box on your next statement. It is already there by law. Look for the bold “Minimum Payment Warning” section. It will show you the years and total cost on your actual balance at your actual rate. That is the real number you’re working with.
- Calculate your gap. The same box must show you the 36-month payoff payment. The difference between that number and your minimum payment is the amount of monthly spending you’d need to redirect to escape the interest trap. Sometimes the gap is smaller than you expect.
- Pay even $25-$50 above the minimum. Because the minimum payment is calculated as a percentage of your balance, any fixed extra amount accelerates payoff dramatically. A flat $50 extra per month on a $5,000 balance at 22% cuts the payoff from 19 years to under 6 years and saves thousands in interest. You do not need to flip your entire budget.
- If the minimum is all you can afford right now, know what that means. It does not mean you are failing. It means the debt is expensive to carry, and you should know the actual cost so you can make a real plan. See all your options — including ones that restructure or eliminate the debt entirely rather than slowly paying interest for two decades.
- If the balance feels unmanageable, run the bankruptcy quiz. The 2-minute quiz will tell you honestly whether the math of your situation favors a fresh start. Federal Reserve research shows bankruptcy filers recover faster financially than people who don’t file. Carrying an unmanageable balance at 22% APR for 19 years is not a recovery plan.
Steve’s Take
I have been watching people pay minimum payments for over 30 years. It is one of the most quietly damaging financial behaviors I’ve ever seen, precisely because it looks like you’re doing the right thing. You’re not missing payments. You’re being “responsible.” And yet the debt never seems to shrink. That’s not a coincidence — it’s math. Debt is math wrapped in emotion, and the emotion of feeling responsible for making a payment can trick you into not looking at what that payment is actually doing to your balance. Look at the warning box. Run the numbers. Then make a decision based on reality, not on what “minimum” sounds like. No sense paying $8,100 for something you already bought for $5,000.
Frequently Asked Questions
What exactly does the minimum payment warning box on my credit card statement say?
By law (12 CFR § 1026.7(b)(12)), your card issuer must include a bolded “Minimum Payment Warning” stating: “If you make only the minimum payment each period, you will pay more in interest and it will take you longer to pay off your balance.” It must then show how long it will take to pay off your balance at the minimum, the total amount you’d pay (principal plus interest), a side-by-side showing the monthly payment and total cost to pay off the balance in 36 months instead, and a toll-free number for credit counseling information.
How is my minimum payment calculated?
Most issuers use a formula of roughly 1% of your statement balance plus that month’s interest charge, with a floor minimum of $25 to $35. The result is that at a high APR, the vast majority of each minimum payment covers interest, and only a tiny fraction reduces the principal. As the balance slowly falls, so does the minimum payment — which actually extends your payoff time even further.
If I can only afford the minimum right now, am I doing something wrong?
No. Circumstances are real. The point is not guilt — it’s awareness. If minimum payments are genuinely all you can manage right now, you’re not failing; you’re surviving a tight spot. What matters is that you understand what the minimum-only path costs over time, so you can prioritize escaping it when your situation changes, or explore whether other options (consolidation, a DMP, or even bankruptcy) might actually get you out faster and cheaper.
Does paying more than the minimum hurt my credit score?
No. Paying more than the minimum is positive for your credit profile — or, at worst, neutral. It reduces your balance, which lowers your credit utilization ratio — one of the largest factors in your score. There is no penalty or negative consequence for paying above the minimum. The only “penalty” is a smaller balance, which is exactly what you want.
What law requires the minimum payment warning box?
The Credit Card Accountability Responsibility and Disclosure Act of 2009 (the CARD Act) created the requirement. It was implemented through the Truth in Lending Act (TILA) and codified in Regulation Z at 12 CFR § 1026.7(b)(12). The CFPB’s Appendix M1 to Part 1026 provides the exact methodology issuers must use to calculate the repayment estimate.
Is paying the minimum ever the right move?
There are a few narrow situations where temporarily paying the minimum makes sense: if you’re in a genuine short-term cash crisis and protecting essentials (housing, food, utilities) has to come first; or if you’re holding a 0% promotional rate balance where the minimum keeps the account current at no interest cost. Outside those situations, the minimum-only path is an expensive default, not a strategy. Your statement’s own warning box tells you so.
How much would I save by paying off a $5,000 balance in 3 years instead of minimum payments?
At a 22% APR, paying the minimum costs roughly $8,100 in interest over about 19 years. Paying a fixed $191 per month pays the balance off in 36 months at a total interest cost of approximately $1,874. That’s a savings of about $6,226 — and you get your life back 16 years sooner. The math was calculated following the methodology Regulation Z requires issuers to use for the comparison disclosure — as illustrated by the sample calculations in CFPB Appendix M2.
What if I want to explore other ways to deal with credit card debt?
The debt options comparison lays out every realistic path side by side — from paying it down yourself to credit counseling, debt settlement, and bankruptcy. Each option has trade-offs on credit impact, speed, and retirement protection. If you want a recommendation based on your actual numbers, the Find Your Path quiz gives a personalized starting point.
This is my perspective based on more than 30 years working with people in debt. It is input, not instruction. Your situation has details I don’t know. Take this information, add it to whatever else you’re learning, and make the decision that’s right for you — not the one that makes someone else comfortable.
The bottom line: Paying only the minimum is not responsible — it’s a 19-year, $8,100 interest payment on a $5,000 purchase, and federal law literally requires your card company to warn you about it on every statement. If someone you care about is convinced the minimum is “fine,” send them this.
Related: what Synchrony’s own SEC filing reveals about credit card fees.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



