

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 21, 2026 • Every claim below links to a primary source.
The verdict: Myth. No company can get your federal student loans forgiven faster, better, or more easily than you can yourself — because every real forgiveness and repayment program is applied for free, directly, at StudentAid.gov. A private company has no special access, no back door, and no faster lane. And when a company charges you an upfront fee to “handle” it, that isn’t just a bad deal — it’s frequently illegal. The Department of Education’s own scam-warning page says it plainly: you can work with your loan servicer “free of charge.”
I have to tell you about this. In April 2026 the Federal Trade Commission moved to shut down an operation it says bilked struggling borrowers out of at least $8.8 million, and the description of the pitch stopped me cold. Here’s how the FTC characterized what these companies did:
“…pretended to be affiliated with the U.S. Department of Education or loan servicers and falsely promised student loan debt relief that did not exist in exchange for illegal upfront fees.” — Federal Trade Commission, April 16, 2026
Upfront fees as high as $1,400 a month, the FTC alleges — taken from people already drowning in student debt, for “help” they could have gotten free. If you’ve ever gotten one of these calls and wondered whether it was real, let me walk you through what’s actually going on.
Well, Actually…
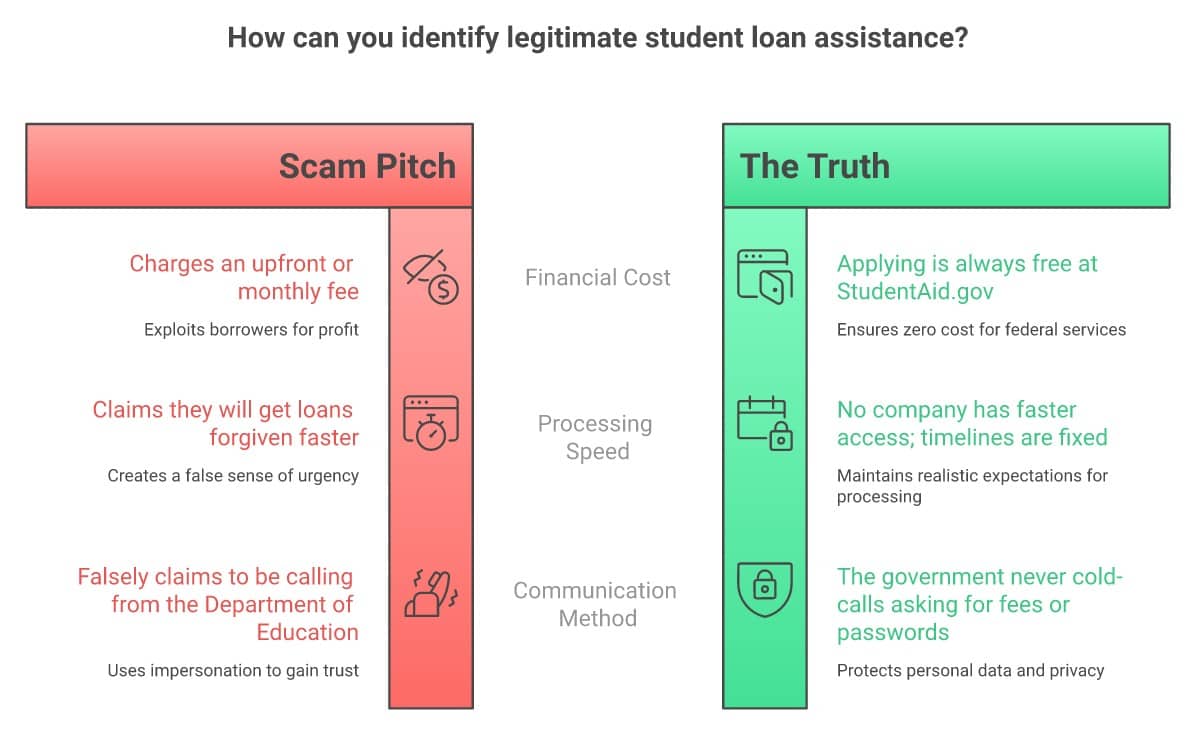
Here’s the part the pitch leaves out: there is nothing a student loan “forgiveness company” can do that you cannot do yourself, for free, in an afternoon. Every legitimate federal program — Public Service Loan Forgiveness, income-driven repayment forgiveness, discharge for disability or a closed school — is applied for on one government website, StudentAid.gov, at no charge. A company can’t make the Department of Education move faster for you. It can’t unlock a program you don’t already qualify for. It has no relationship with your servicer that you don’t have. What it’s really selling is a form you could fill out yourself — and, in the FTC’s cases, it does so while pretending to be the government to make you believe otherwise.
And 2026 is a perfect storm for this scam, which is exactly why I’m writing about it now. The rules genuinely did just change. The old SAVE plan was struck down by a federal court and ended by law, a brand-new Repayment Assistance Plan (RAP) launched July 1, 2026, and millions of borrowers are getting letters telling them to switch plans within 90 days. When the rules are in chaos, scammers thrive — because “everything’s changing, let us handle it for a fee” suddenly sounds reasonable. It isn’t. The confusion is the product they’re selling.
The tell is almost always the same two things: money up front and a promise of speed or a guarantee. The Department of Education warns that companies “will try to take advantage of borrowers by guaranteeing immediate results or requesting money up front for services they can’t provide.” Real forgiveness has eligibility rules and timelines nobody can shortcut — not you, and definitely not a company charging you $1,400 a month to say they can.
“Pay our monthly fee and we’ll get your student loans forgiven faster than you could on your own.”
Every federal forgiveness, discharge, and income-driven repayment program is applied for free, directly, at StudentAid.gov — and you can explore your options with your loan servicer “free of charge.” No private company has faster access or special influence. Paying a fee buys you nothing you didn’t already have for free.
“Just pay the enrollment fee up front and we’ll get started.”
Charging an advance fee for debt-relief services — before anything is actually delivered — violates the FTC’s Telemarketing Sales Rule. In its April 2026 case against NERD Solutions Inc. and ED REF Inc., the FTC alleged the operators pretended to be affiliated with the Department of Education, lured borrowers with false forgiveness promises, and collected “illegal upfront fees” — charging the government’s own name against people already buried in debt. Upfront money isn’t a fee. It’s the red flag.
Federal Trade Commission v. NERD Solutions Inc., et al. — April 16, 2026
Why You Were Told This
Follow the money. There is a whole industry built on standing between you and a free government form, and its entire business model depends on you not knowing the form is free. Some of these operators are sloppy marketers; others, according to the FTC, are outright fraudsters who impersonated the Department of Education and agreed to be permanently banned from the industry to resolve the FTC’s charges (a separate 2025 case). Either way, the confusion is the asset. Every time the rules change — a plan ends, a new one launches, a court ruling makes headlines — their phones light up, because fear and complexity are what they sell against. You were told this because someone profits from you believing you can’t do it yourself. You can.
What to Actually Do
- Start at StudentAid.gov — and nowhere else. Type the address into your browser yourself; never click a link in an unsolicited call, text, or email. Log in, look at your loans, and use the free Loan Simulator to compare repayment and forgiveness options. It’s the same information any company would charge you to look up — including switching to the new Repayment Assistance Plan (RAP), which is also free to apply for directly.
- Call your loan servicer directly. They’ll walk you through your options at no cost. If you don’t know who your servicer is, StudentAid.gov tells you. Contact the Federal Student Aid Information Center for PSLF questions.
- Never pay an upfront fee, and never give out your StudentAid.gov password. The Department of Education says it and its partners “will never ask for your password. That’s a guarantee.” Anyone who does is a scammer.
- Treat “act now” and “guaranteed forgiveness” as stop signs. Real programs have eligibility rules and timelines nobody can rush. Pressure and guarantees are the scam’s fingerprints.
- If you already gave a company money or your login, act to protect yourself. Stop any recurring payments, and if you shared your StudentAid.gov (FSA ID) password, change it immediately and check your account for any unauthorized servicer or consolidation changes. Write down anything the company says it submitted for you so you can confirm it and finish the process yourself. Then report them at ReportFraud.ftc.gov and to your state attorney general — that’s how the FTC builds the cases that get these operators banned and, sometimes, sends refunds to victims.
Steve’s Take
I’ve watched this same scam wear different costumes for over thirty years. The costume changes — debt settlement, credit repair, mortgage rescue, now student loan forgiveness — but the engine underneath never does: take a struggling person, charge them for something that’s free, and use the government’s own name to sell it. What makes the student loan version especially cruel is who it targets — people who did the responsible thing, borrowed to better themselves, and are now anxious about a system that genuinely keeps changing the rules on them. If a company is charging you a monthly fee to “manage” your forgiveness, cancel it today. When someone charges you monthly to speed up federal forgiveness, nothing you’re paying for is real. The one form that matters is free, it’s at StudentAid.gov, and you are perfectly capable of filling it out yourself.
Frequently Asked Questions
Can a company really get my student loans forgiven faster than I can?
No. There is no faster lane. Every federal forgiveness and income-driven repayment program is applied for free at StudentAid.gov, and a private company has no special access to the Department of Education or your servicer. Anyone promising to speed it up for a fee is selling you a free form.
Is it illegal for a company to charge me upfront to get my loans forgiven?
Charging advance fees for debt-relief services — like these telemarketed forgiveness pitches — before delivering any result violates the FTC’s Telemarketing Sales Rule, and the FTC has repeatedly shut such operations down. In its April 2026 case it called the upfront fees “illegal” outright.
How do I apply for student loan forgiveness for free?
Go to StudentAid.gov, log in, and apply directly — or call your loan servicer, who will help you at no charge. That’s the entire process. There is no fee and no company required.
The SAVE plan ended — do I need to pay someone to switch me to a new plan?
No. When the SAVE plan ended, servicers began notifying borrowers to choose a new repayment plan within 90 days. You select the new plan yourself, for free, at StudentAid.gov or through your servicer — and the new Repayment Assistance Plan (RAP), like every federal plan, costs nothing to apply for. Here’s what to do about the SAVE deadline.
A caller said they were from the Department of Education. Was that real?
Be very skeptical. The FTC’s cases repeatedly involve scammers impersonating the Department of Education or your servicer over the phone. The government will never ask for your StudentAid.gov password, and legitimate help never requires an upfront fee. If in doubt, hang up and call your servicer using the number on StudentAid.gov.
I already paid a company. Can I get my money back?
Sometimes. Report it at ReportFraud.ftc.gov and to your state attorney general. When the FTC wins these cases, it has returned money to victims — but the surest protection is to stop any ongoing monthly payments to the company immediately.
Are there any legitimate reasons to pay for student loan help?
For the forgiveness and repayment programs themselves, no — those are always free. The narrow exception is genuine legal trouble, such as a lawsuit over a private student loan, where a licensed attorney’s fee is for actual legal representation, not for “unlocking” a free federal program. A non-lawyer “student loan consultant” charging a monthly fee is not that exception — if the person isn’t a licensed attorney representing you, the fee buys you nothing you couldn’t do free.
This is one informed perspective from someone who has spent three decades watching how these scams work — not personalized financial or legal advice. Only you can decide what’s right for your situation. Take it as input, not instruction.
The bottom line: No company can get your student loans forgiven faster than you can — every real program is free at StudentAid.gov, and charging upfront fees to “handle” it is often flat-out illegal. If someone you know is paying a monthly fee for loan forgiveness “help,” send them this — you might save them thousands.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve research shows bankruptcy filers recover faster than those who don’t file.



