

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 21, 2026 • Every claim below links to a primary source.
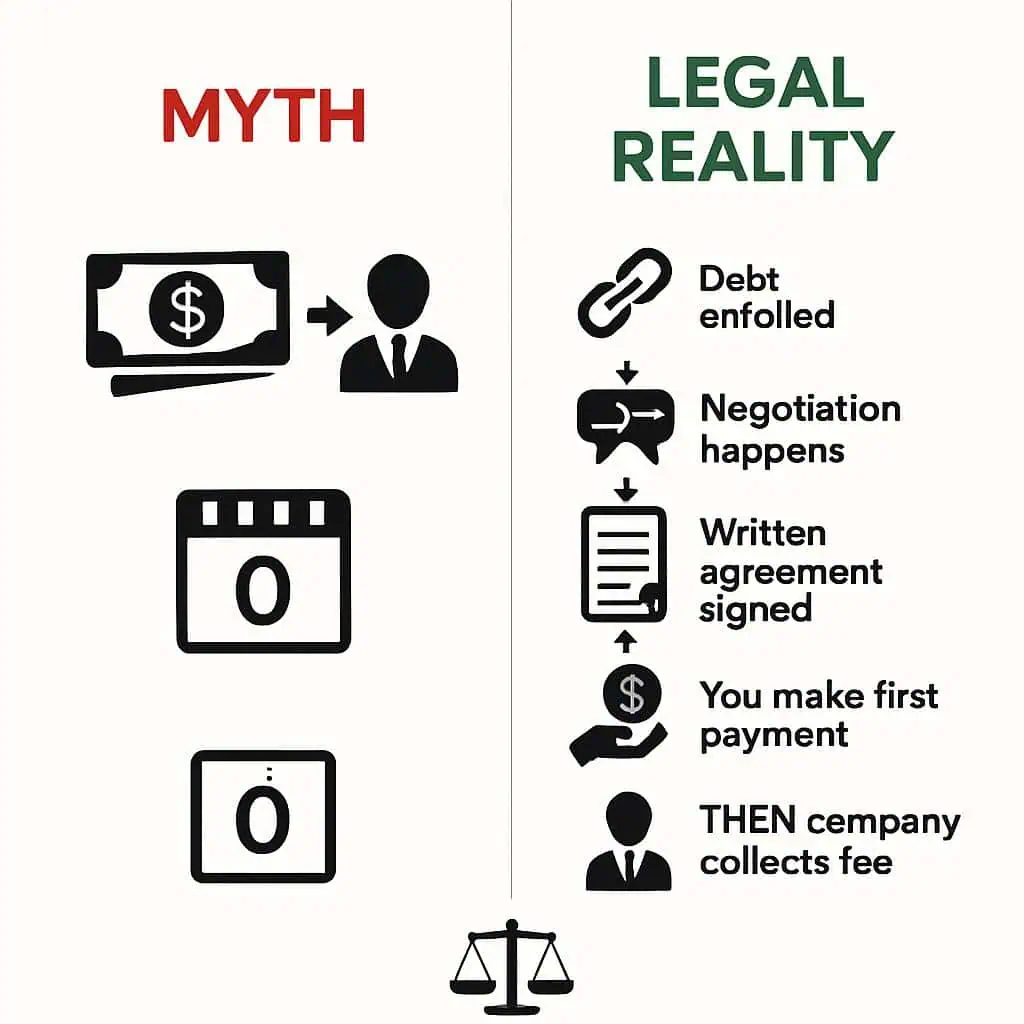
The verdict: Myth. Charging you a fee before settling any of your debts is not “how the industry works” — it is a federal violation. Under the FTC’s Telemarketing Sales Rule, a for-profit debt relief company that sells its services by phone cannot collect a single dollar in fees until it has actually settled at least one of your enrolled debts, you have approved a written agreement, and you have made at least one payment under that deal. If a company asks for money upfront, that is the scam, not the service. 16 CFR §310.4(a)(5)(i) confirms it — effective October 27, 2010.
I have to tell you about this. In July 2025, the FTC shut down a debt-relief operation that was charging consumers upfront fees, impersonating both legitimate businesses and government agencies, and specifically targeting seniors and veterans. The FTC complaint documented a simple pitch: pay a fee up front to get started, and the company will negotiate your debts afterward. The operation collected millions of dollars this way. The FTC called it exactly what it is: illegal.
People keep falling for that pitch because they genuinely believe paying first is normal in the debt settlement world. It is not — it is a federal violation. Let me clear that up once and for all.
Well, Actually…
Here is the part the upfront-fee pitch leaves out: there is a federal law — enacted in 2010 — that makes it illegal for a for-profit debt settlement company to take one dollar of your money before it has actually settled, reduced, or otherwise resolved at least one of the debts you enrolled. The law is 16 CFR §310.4(a)(5)(i), part of the FTC’s Telemarketing Sales Rule. The FTC added this specific provision to the Telemarketing Sales Rule in 2010 because the advance-fee model was generating a flood of consumer complaints and causing real financial harm.
The rule sets three conditions that must all be met before a company can collect any fee: (1) the company has actually renegotiated, settled, reduced, or altered the terms of at least one of your debts under a written agreement you have approved; (2) you have made at least one payment to the creditor under that settlement; and (3) if you have multiple debts enrolled, the fee they charge must be proportional — they cannot charge the full fee upfront and call it “settling the easy debt first.” The FTC puts it plainly on its own consumer site: “Only scammers will try to collect fees from you before they settle any of your debts or enter you into a debt management plan.” (FTC, How to Get Out of Debt.)
There is one important nuance to know. Companies can legally require you to put money — both their eventual fees AND your future creditor payments — into a dedicated savings account while negotiations are underway. But there are strict rules: the account must be at an insured financial institution, you own the money and earn any interest, the account administrator cannot be affiliated with the debt relief company, and you can withdraw your money within seven business days with no penalty. What they cannot do is reach into that account and take their fee until the settlement conditions are satisfied. That distinction matters — having a dedicated account is not the same as collecting a fee. The scam is when the company just takes money at the start with no conditions attached.
One more nuance worth saying directly: this rule covers debt relief companies that sell their services over the phone, which is how the overwhelming majority of for-profit debt settlement companies operate. If you walked into a face-to-face office — vanishingly rare for debt settlement — the telemarketing rule does not technically apply, though other FTC and state consumer-protection rules would. If you were contacted by phone or found a company online and communicated via phone, you are almost certainly covered.
You have to pay the debt settlement company a fee before they start negotiating — that’s just how the industry works.
Under the FTC’s Telemarketing Sales Rule, a for-profit debt settlement company that sells via phone is legally prohibited from collecting any fee until (A) it has actually settled at least one enrolled debt under a written agreement you approved, (B) you have made at least one payment under that settlement, and (C) its fees are proportional across enrolled debts. Charging before results is a federal violation — not standard practice. The FTC says it plainly: only scammers collect fees before they settle your debt.
16 CFR §310.4(a)(5)(i), Telemarketing Sales Rule (effective October 27, 2010)
Putting money into a dedicated account before any settlement is reached is the same thing as paying them a fee upfront.
No — a dedicated account is not a fee. A dedicated savings account is legal under the TSR — but only with strict conditions. The money must be in an insured account you own, the administrator cannot be affiliated with the settlement company, and you can withdraw it without penalty at any time. What makes it a scam is if the company takes its fee from that account before settling a debt. The law draws a clean line: setting aside YOUR money with YOUR control is permitted. Taking THEIR fee before delivering a result is not.
Why You Were Told This
The advance-fee pitch survives for a simple reason: it makes enormous amounts of money for the people running it. A consumer desperate enough to call a debt settlement company is often desperate enough to hand over several hundred dollars — or several thousand — before asking hard questions. The pitch sounds logical because legitimate professionals in other fields (lawyers, accountants, contractors) do require deposits or retainers. The confusion is real and the bad actors exploit it deliberately.
Some companies disguise the illegal fee as an “enrollment fee,” an “administrative fee,” or a “service initiation charge.” The name on the invoice does not matter. If they are collecting it before settling a debt, it violates the rule. The FTC’s July 2025 enforcement action against the operation targeting seniors and veterans illustrates exactly how brazen this can get: the operation impersonated both the government and legitimate companies, specifically to make the upfront fee look normal.
I also want to be honest about something. Even legitimate debt settlement — the kind that follows the law — comes with serious costs and risks: your credit will be damaged during the process, creditors are not obligated to settle, and forgiven debt may be taxable income (creditors are required to file a 1099-C with the IRS when the forgiven amount is $600 or more, but any forgiven amount is potentially includable in your gross income regardless of the reporting threshold; though if you were insolvent when the debt was forgiven, you may be able to exclude some or all of it from income using IRS Form 982 — that insolvency calculation is easy to get wrong, so run it with a tax professional or IRS Publication 4681). The advance-fee ban does not transform debt settlement into a good deal. It just ensures you are not robbed before the deal begins.
Free Tool — 1099-C Tax Calculator: Received a 1099-C for cancelled debt? The free 1099-C Tax Calculator runs the exact IRS insolvency math from Publication 4681 Worksheet 2 — and covers the partial insolvency case most people miss. Run the Calculator →
What to Actually Do
- Ask for the fee structure in writing before you sign anything. A legitimate debt settlement company will tell you exactly what it charges, when it charges it, and confirm that no fee is collected until after a debt is settled and you have made a payment. If they resist that question, that is your answer.
- Verify the dedicated account terms if one is required. You should own the funds, the account should be at an FDIC-insured bank, the administrator should be independent of the settlement company, and you should be able to close the account and withdraw your money at any time. Get these terms in writing, not just verbally.
- Check the company with the FTC, CFPB, and your state attorney general before signing. Search the company name at CFPB’s complaint database and at your state AG’s office. Complaints about fees charged before results are a red flag in any quantity.
- Understand all your options before committing. Debt settlement is one path, with real costs to your credit and real tax risk. Bankruptcy resolves debt faster, protects your retirement, and — according to Federal Reserve Bank of New York research — filers recover faster than those who do not file. A nonprofit credit counselor (legitimate ones do not charge upfront) and a bankruptcy attorney (many offer free consultations) can help you compare.
- Report it if you were charged a fee before results were delivered. File a complaint at ReportFraud.ftc.gov and with the CFPB. Enforcement actions that protect the next person start with individual complaints.
Steve’s Take
I want to separate two things here, because they are genuinely different. The advance-fee ban is a bright, unambiguous legal line — and it has been federal law since October 2010. If a debt settlement company is charging you before it has settled anything, that is illegal, full stop. That is not an opinion. That is what the regulation says.
But the existence of that law does not make debt settlement a smart choice. In my own debt-option analysis — based on more than 30 years of watching these paths play out — settlement scores “meh” on almost everything and “bad” on retirement savings. Your credit takes a hit during the months or years of non-payment. Creditors can sue you during that time. Tax bills on forgiven debt can blindside you. And completion rates are not impressive.
The people most likely to be hit with an illegal advance-fee pitch are also the people who have the fewest resources to absorb the loss. Seniors on fixed incomes. Veterans dealing with medical debt. People who are scared and exhausted. The FTC July 2025 enforcement action was not a coincidence — those are exactly the populations the bad actors target. That is why I keep writing about this. Debt is math wrapped in emotion, and fear makes people easy to exploit. Know the law. Know your options. And if a company asks for money before delivering results, walk away.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Frequently Asked Questions
Is it ever legal for a debt settlement company to charge me anything before settling my debt?
Under the FTC’s Telemarketing Sales Rule (16 CFR §310.4(a)(5)(i)), a company that sells debt settlement via phone cannot collect any fee before settling at least one of your enrolled debts and after you have made at least one payment under that settlement. They can require you to deposit funds — your own money — into a dedicated account, but those funds must remain yours until a settlement is achieved. A fee taken before results are delivered is a federal violation.
Does the advance-fee ban apply to all debt settlement companies?
The ban applies to for-profit companies that sell debt relief services over the phone — which covers the vast majority of the debt settlement industry. If you were contacted by phone or communicated with a company by phone, the Telemarketing Sales Rule almost certainly applies to your transaction. Purely face-to-face transactions are technically outside the TSR, though other federal and state consumer-protection laws may still apply. Nonprofit credit counseling organizations that are legitimately tax-exempt operate under different rules.
What should I do if a debt settlement company already charged me an upfront fee?
First, stop making payments to the company. Then file a complaint with the FTC at ReportFraud.ftc.gov and with the CFPB. Contact your state attorney general as well — many states have their own consumer-protection laws covering debt relief services, and some offer restitution. Document everything: contracts, receipts, communications. If the amount is significant, consult a consumer-protection attorney — some take these cases on contingency.
What is a “dedicated account” and is it allowed?
A dedicated account (sometimes called an escrow or special-purpose savings account) is a bank account that holds money you set aside while the settlement company negotiates with your creditors. The law allows this arrangement under specific conditions: the account must be at an FDIC-insured institution, you must own the funds and receive any interest, the account administrator cannot be affiliated with or pay kickbacks to the settlement company, and you must be able to withdraw all your money at any time without penalty. The company can only take its fee from that account after it has settled a debt and you have made a payment — not before.
What happens if a debt settlement company ignores this law?
The FTC can seek injunctions, civil penalties, and consumer redress. The July 2025 enforcement action against an operation targeting seniors and veterans resulted in the operation being immediately halted. The CFPB also has enforcement authority over debt relief service providers and can order refunds and additional penalties. Individual consumers can also file civil suits under applicable state consumer-protection laws.
Are there legitimate debt settlement companies that follow this rule?
Yes — legitimate companies do exist and do comply with the advance-fee ban. They negotiate with creditors, collect their fee only after a settlement is reached, and are transparent about the risks (credit damage, potential lawsuits during the process, tax implications of forgiven debt). The problem is that the industry also has a significant bad-actor presence, and distinguishing the two requires careful vetting: check the CFPB complaint database, verify state licensing if required in your state, and get the fee structure in writing before signing.
Is debt settlement my best option if I am struggling with credit card debt?
That depends entirely on your situation — and I am not going to pretend otherwise. Debt settlement damages your credit during the process, leaves you exposed to lawsuits from creditors who don’t settle, and may generate a tax bill on forgiven amounts. Bankruptcy resolves debt faster with legal protection, and Federal Reserve Bank of New York research shows filers recover faster than people who grind through years of alternative plans. A nonprofit credit counselor or a bankruptcy attorney can help you compare your actual numbers. The goal is the option that best serves your future — not the option that sounds most familiar.
This post is meant to give you information, not legal advice. Debt relief law and your specific situation are complex, and what I write here is one informed perspective from someone who has spent over 30 years in this space — not a substitute for advice from an attorney or counselor who knows your full circumstances. Take this as input, not instruction, and make the decision that is right for you.
The bottom line: Charging you a fee before settling any of your debts is not “industry standard” in debt settlement — it is a federal violation under the FTC’s Telemarketing Sales Rule, in effect since 2010. No results, no fee. If someone tries to collect before delivering results, that is the scam. If someone you know is about to pay a debt settlement company upfront, send them this.
Related: There’s one payment demand that shows up in almost every impersonation scam — if anyone tells you to pay a debt, bill, or fine with gift cards, it’s always a scam.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research show bankruptcy filers recover faster than those who don’t file.



