

Quick Answer: A bankruptcy discharge wipes out your personal obligation to pay a debt — your “in personam” liability — but it does not, by itself, eliminate a valid lien on property you pledged as collateral. If your personal guarantee was unsecured (just your signature, no collateral pledged), the discharge ends it completely and the creditor cannot touch your assets. But if you pledged collateral — your home, a vehicle, business equipment, or signed a UCC-1 blanket lien — the lien on that specific property can survive the discharge, and the creditor may still be able to foreclose or repossess it. The U.S. Supreme Court confirmed this in Johnson v. Home State Bank, 501 U.S. 78 (1991): “a creditor’s right to foreclose on the mortgage survives or passes through the bankruptcy.” This is why reviewing your actual security documents with a bankruptcy attorney before you file is not optional — it’s essential.
Expert Context: I filed bankruptcy myself in 1990 after my real estate business collapsed — so I know from personal experience how it feels to believe the discharge has resolved everything, only to discover the lien picture is more complicated. Since then I’ve spent more than 30 years helping people understand exactly what a discharge does and doesn’t do. This particular distinction — in personam vs. in rem — is one of the most misunderstood concepts in consumer bankruptcy, and getting it wrong can cost you your home or your car.
This Question Came From Ask Steve: A reader reached out through my Ask Steve chat with exactly this situation — believing the discharge had resolved everything, then discovering the lender was still pursuing the collateral. I’ve shared zero personal details from that conversation, and I never will. Privacy is a promise I keep. If you’re facing something similar, I’d love to help. Ask me your question here.
Part of the Chapter 7 Bankruptcy Hub: This post is one piece of my complete Chapter 7 Bankruptcy Guide — everything you need to know about filing, who qualifies, what gets discharged, and what happens to your credit after.
Part of the Crisis Guide Series: This is one of my emergency triage guides. See all available Crisis Guides — step-by-step action plans for the worst financial moments.
Here’s the thing about bankruptcy that surprises most people: the discharge is more precise than it looks. It doesn’t erase everything — it erases your personal obligation to pay. That’s a crucial distinction when collateral is involved, and it’s one the paperwork at signing rarely makes clear.
If you’re working through a business collapse and personally guaranteed the loan, my companion guide covers the full picture of what to do right now: My Business Failed and I Personally Guaranteed the Loan. This post is the legal deep-cut on one specific issue — what happens to the collateral after your discharge.
Key Terms Defined
In personam liability: Your personal obligation to pay a debt. “In personam” means “against the person.” When a creditor has an in personam claim, they can sue you personally and collect from your wages, bank accounts, or general assets. This is what the bankruptcy discharge eliminates under 11 U.S.C. § 524(a).
In rem liability: A creditor’s right against specific property — not against you personally. “In rem” means “against the thing.” A mortgage, deed of trust, or UCC security interest creates an in rem right. The discharge does not automatically extinguish an in rem right.
Security interest / lien: A creditor’s legal claim against specific property pledged as collateral for a debt. Created by agreement (consensual lien — a mortgage you voluntarily granted) or by court judgment (judicial lien — from a lawsuit).
UCC-1 financing statement: A document filed under Article 9 of the Uniform Commercial Code to publicly perfect a creditor’s security interest in collateral. A “blanket lien” UCC-1 covers essentially all business — and sometimes personal — assets.
Cross-collateralization: A contract provision (common in SBA loans and bank credit agreements) that uses collateral pledged for one loan to also secure other loans with the same lender.
What the Discharge Actually Does — and Doesn’t Do
When you receive a bankruptcy discharge, 11 U.S.C. § 524(a) kicks in and does two things: it voids any judgment that established your personal liability for discharged debts, and it permanently enjoins creditors from trying to collect those debts from you personally. No lawsuits, no wage garnishments, no collection calls demanding personal payment.
But Congress — and the Supreme Court — have been unambiguous about what the discharge does not do: it does not extinguish a valid lien on property.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
In Johnson v. Home State Bank, 501 U.S. 78 (1991), the Supreme Court held that “a bankruptcy discharge extinguishes only one mode of enforcing a claim — namely, an action against the debtor in personam — while leaving intact another — namely, an action against the debtor in rem.” The Court went further: “the Code provides that a creditor’s right to foreclose on the mortgage survives or passes through the bankruptcy.”
The statute’s own required disclosure language reinforces this. The § 524 notice materials that courts must provide to debtors state plainly: “Your bankruptcy discharge does not eliminate any lien on your property.”
The Myth: “I got my discharge and they can’t come after me anymore — my personal guarantee is completely gone.”
The Reality: The discharge killed your personal obligation to pay (in personam liability). If the guarantee was backed by pledged collateral — a deed of trust on your home, a security interest in equipment, a UCC-1 blanket lien — the creditor’s in rem right against that specific property survives. They cannot sue you. But they may still be able to foreclose or repossess the pledged collateral unless you take specific action to address the lien. But there is real good news in the fine print: the pledged collateral is the outer limit of what they can reach. If they foreclose or repossess and the sale falls short of the balance, they cannot pursue you for that shortfall (the deficiency) — that personal obligation is gone for good. (One caveat: this assumes the debt was dischargeable. A few kinds of debt — certain tax obligations, debts based on fraud, and others listed in 11 U.S.C. § 523 — can survive bankruptcy both as a lien and as personal liability. If yours might fall into one of those categories, confirm with an attorney before assuming the deficiency is gone.)
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Unsecured vs. Secured Personal Guarantee: The Distinction That Changes Everything
Not all personal guarantees are created equal. Before you can know what your discharge accomplished, you need to understand which kind you actually signed.
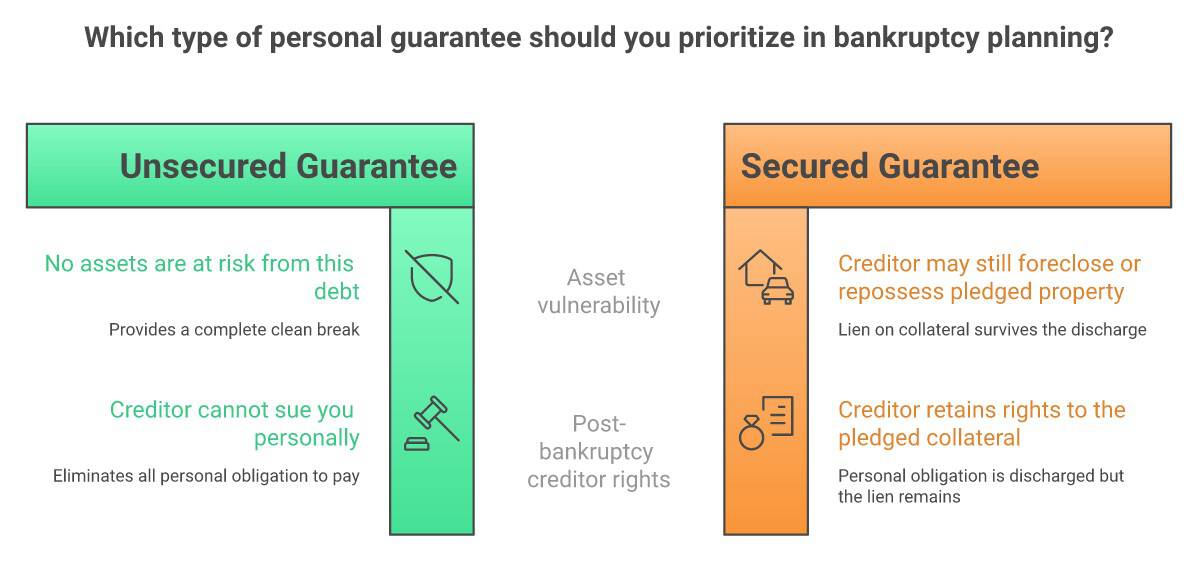
Unsecured Personal Guarantee
- Just your signature promising to pay if the borrower defaults
- No specific collateral pledged
- Creditor’s only remedy: sue you personally
- After discharge: claim is completely extinguished — full stop
- Creditor cannot pursue you or any of your assets
- Common in: simple trade credit, some private business loans, many vendor agreements
Secured Personal Guarantee
- Backed by a pledge of specific collateral
- Creates a lien (in rem right) against the pledged property
- After discharge: personal liability gone, but the lien survives
- Creditor may still foreclose or repossess the pledged collateral
- Common in: SBA loans, bank credit lines, some merchant credit arrangements
- Often missed: UCC-1 blanket lien buried in the security agreement paperwork
The critical question is not just “did I sign a personal guarantee” — it’s “did I also pledge collateral, either directly or through a security agreement accompanying that guarantee?” Many business owners sign both documents at the same closing and don’t register the distinction between them.
The Hidden Trap: UCC Blanket Liens and Cross-Collateralization
Here’s where I see small-business owners get blindsided most often. They believe their personal guarantee was “just a signature” — and they may be right about the guarantee form itself. But buried in the same loan package, in the security agreement that accompanied the guarantee, or in the body of the promissory note itself, is language granting the lender a security interest in collateral. Then a UCC-1 financing statement was filed publicly to perfect that interest.
SBA 7(a) loans are a frequent example. The SBA requires unlimited personal guarantees from all owners holding 20% or more of the business. On larger loans where business assets don’t fully secure the debt, lenders are typically required to take available equity in an owner’s personal residence as additional collateral. If you received an SBA loan and pledged your home as additional collateral, that pledge survives your discharge as an active lien on your home. COVID-era EIDL loans had their own personal guarantee thresholds — another set of documents worth reviewing carefully.
The same pattern appears with bank lines of credit and some merchant cash advance agreements. The guarantee form is obvious; the UCC-1 blanket lien filing and cross-collateralization clause are not. A blanket lien can cover inventory, receivables, equipment, and sometimes personal property all in one document.
If you’re not certain whether your guarantee was secured, you need to retrieve the actual loan documents — the guarantee itself, the security agreement, and any UCC financing statements filed against your name or your business — and have a bankruptcy attorney review them before you assume the discharge resolved everything completely.
Debt is math wrapped in emotion — and secured debt is math wrapped in paperwork. The paperwork you didn’t read closely at closing is often the part that survives the discharge.
What You Can Do About a Surviving Lien
If you discover that a lien survived your discharge, you’re not without options. The right tool depends on the type of lien, the type of property, and which chapter of bankruptcy you’re in or considering. This is precisely where a bankruptcy attorney’s review of your actual security documents is essential — I can explain the tools accurately, but only an attorney who has read your specific paperwork can tell you which ones apply to your situation.
1. Reaffirmation Under 11 U.S.C. § 524(c) (Chapter 7)
A reaffirmation agreement is a new voluntary contract between you and the creditor. You agree to remain personally liable for the debt — waiving the discharge for that specific obligation — in exchange for keeping the collateral and continuing to make payments. The court must review and approve it. Reaffirmation makes sense only if the collateral’s value is reasonable relative to the balance, you can genuinely afford the payments, and keeping the property serves your actual financial future. It is never mandatory, and in many situations I would not recommend it. An attorney can help you evaluate whether this genuinely serves your interests or simply restores exposure you just discharged. One specific warning for homes: you almost never need to reaffirm a mortgage to keep your house. Because the lien survives the discharge, you can simply keep making the payments and stay — the “pay and stay” approach — without signing your discharge away. Reaffirming a mortgage re-exposes you to the personal liability you just eliminated, which is why many courts may decline to approve it, and most lenders accept your continued payments without it. Reaffirmation is mainly a personal-property (car) tool, and even then only when the numbers genuinely work.
2. Redemption Under 11 U.S.C. § 722 (Chapter 7)
Section 722 allows you to redeem certain tangible personal property by paying the creditor the allowed secured claim amount — which courts determine using replacement value (what you’d pay to obtain a comparable item for the same use), not a forced-sale or liquidation price, per Associates Commercial Corp. v. Rash, 520 U.S. 953 (1997) — in a single lump sum. The payment discharges the balance above that value. If you owe $18,000 on a car with a replacement value of $9,000, you pay $9,000 and the lien is extinguished. The remaining $9,000 is discharged. This is a powerful tool when you’re underwater on a personal vehicle.
§ 722 Limitations: Redemption applies only to tangible personal property primarily for personal, family, or household use — your personal car, household goods, and similar items. It does not apply to real property (your home) or to business equipment held primarily for commercial use. Critically, § 722 is limited to liens on dischargeable consumer debt — not business-purpose loans. If your surviving lien comes from an SBA loan, commercial line of credit, or other business financing, § 722 likely does not apply to that collateral. The redemption payment must be made in a single lump sum; some lenders specialize in financing redemptions for exactly this purpose. See also what happens with title loans specifically after bankruptcy. If you’re in an active Chapter 13 and thinking about a brand-new title loan rather than one you already had, here’s what to ask before you pledge that car again.
3. Judicial Lien Avoidance Under 11 U.S.C. § 522(f)
Section 522(f) has two prongs. Under § 522(f)(1)(A), a debtor can avoid judicial liens — liens created by a court judgment — that impair an exemption. Under § 522(f)(1)(B), the statute also covers a narrower class of consensual liens: specifically, nonpossessory, nonpurchase-money security interests in household goods, tools of the trade, and professionally prescribed health aids. The impairment test for both prongs: the sum of the lien, plus all other liens on the property, plus the amount of the applicable exemption must exceed the property’s value as if there were no liens. If that calculation is satisfied, the lien can be avoided to the extent it impairs the exemption.
Critical Limitation: Section 522(f) does not reach purchase-money security interests — the mortgage you took out to buy your home, or a lien on property purchased with the loan funds. It also does not cover possessory liens. If the surviving lien is a traditional mortgage, deed of trust, or purchase-money vehicle lien, § 522(f) cannot remove it. For those, Chapter 13 tools or redemption under § 722 may be the relevant options.
4. Chapter 13 Tools: Lien Strip-Off and Cramdown
Chapter 13 offers additional tools that Chapter 7 does not provide.
Lien strip-off: If a junior lien (a second mortgage, for example) is wholly unsecured — meaning the property is worth less than what is owed on the first, senior lien, leaving zero equity supporting the junior lien — Chapter 13 can strip that junior lien off entirely in most federal circuits, treating it as an unsecured claim discharged at plan completion. Important: a strip-off becomes permanent only when you complete the plan and receive your discharge — if the case is dismissed or converted to Chapter 7 partway through, the junior lien reattaches. This can be significant if you have a second mortgage on an underwater property. (Note: strip-off is unavailable in Chapter 7 following Bank of America v. Caulkett, 575 U.S. 790 (2015); Chapter 13 strip-off remains majority-circuit practice, though the Supreme Court has not directly confirmed it — verify with your attorney.)
Cramdown: Chapter 13 can “cram down” a secured claim on certain types of collateral to the property’s current fair market value. If you owe $30,000 on business equipment worth $12,000, a Chapter 13 plan can bifurcate the claim: $12,000 is treated as secured (paid through the plan), and $18,000 is treated as unsecured and discharged at completion. One important limit: Chapter 13 generally cannot cram down a purchase-money loan on a vehicle you bought for personal use within 910 days (about two and a half years) before filing, or on many other kinds of purchase-money collateral bought within one year (its exact reach can vary by court) — a special rule Congress added in 2005 (the “910-day rule,” part of 11 U.S.C. § 1325(a)). If your car loan is recent, cramdown likely will not be available for it.
Critical Restriction on Primary Residence Mortgages: 11 U.S.C. § 1322(b)(2) contains an “anti-modification” provision: a Chapter 13 plan generally cannot modify a mortgage secured only by a lien on the debtor’s principal residence. The Supreme Court confirmed in Nobelman v. American Savings Bank, 508 U.S. 324 (1993) that this restriction applies even when the home is underwater. The exception: a junior lien that is wholly unsecured (nothing supporting it because the first lien already exceeds the home’s value) can typically be stripped off in Chapter 13 in most circuits — but that is a narrow fact-specific determination.
Key Takeaways
- The bankruptcy discharge kills your personal liability (in personam) but not the creditor’s lien on pledged collateral (in rem) — confirmed by Johnson v. Home State Bank, 501 U.S. 78 (1991)
- An unsecured personal guarantee — signature only, no collateral pledged — is completely extinguished by the discharge
- A secured personal guarantee — backed by a home pledge, UCC-1 blanket lien, cross-collateral clause, or direct security agreement — leaves the lien on that specific collateral intact after discharge
- SBA loans, bank lines of credit, and some merchant arrangements routinely include UCC blanket liens that many borrowers don’t fully register at closing
- Tools available to address a surviving lien: reaffirmation (keep-and-pay), redemption under § 722 (pay replacement-value lump sum; Chapter 7, consumer debts only), judicial lien avoidance under § 522(f) (judicial liens + certain nonpurchase-money consensual liens; does not reach purchase-money security interests like mortgages), and Chapter 13 lien strip-off or cramdown (with type-specific restrictions)
- The right tool for your specific lien requires an attorney who has read your actual security documents
The Bottom Line
If you’re staring at this question because a lender is still pursuing your home or equipment after a discharge you believed resolved everything, you are not wrong for not knowing this distinction — the line between personal liability and property rights is a legal concept nobody explains at loan closing. The discharge is real and powerful: your personal obligation to pay is gone. But a lien is a property right, not a personal obligation, and it requires its own resolution through one of the tools described above. I filed bankruptcy in 1990 and rebuilt everything that came after. The math of secured debt can be addressed — but you need the right map of your specific terrain first, which means an attorney who has actually read your paperwork. Don’t let what you don’t know keep you from getting the help you do deserve.
The same discharge injunction that stops a lender from chasing your personal guarantee also stops any creditor from billing you directly on a discharged debt — see A Creditor Won’t Stop Collecting After My Bankruptcy Discharge. Here’s What to Do Right Now. if that’s happening to you.
Liens surviving a discharge aren’t the only exception to bankruptcy’s fresh start — court-ordered criminal restitution survives too, in every chapter; see what actually protects you if it’s gone to a collection agency.
Frequently Asked Questions
Does my bankruptcy discharge eliminate a personal guarantee entirely?
It depends on whether the guarantee was secured by collateral. If it was an unsecured personal guarantee — just your signature, no property pledged — the discharge extinguishes it completely and the creditor has no remaining claim against you or your assets. If the guarantee was backed by pledged collateral (a home, vehicle, equipment, or assets covered by a UCC-1 blanket lien), the discharge eliminates your personal obligation to pay but the creditor’s lien on the specific collateral survives. The Supreme Court confirmed this in Johnson v. Home State Bank, 501 U.S. 78 (1991): the discharge “extinguishes only one mode of enforcing a claim — namely, an action against the debtor in personam — while leaving intact another — namely, an action against the debtor in rem.”
How do I know if my personal guarantee was secured or unsecured?
You need to review the actual loan documents — the guarantee form itself, any security agreement that accompanied it, and UCC-1 financing statements filed in your state. The guarantee document often cross-references a separate security agreement. UCC-1 filings are public records; your state’s Secretary of State website typically has a free search tool where you can search by debtor name. If you’re uncertain what you signed, a bankruptcy attorney can review the documents and identify exactly what security interests were created. This review is worth doing before you assume your discharge resolved everything.
What is a UCC-1 blanket lien and why does it survive bankruptcy?
A UCC-1 financing statement, filed under Article 9 of the Uniform Commercial Code, is a public notice that a lender holds a security interest in a debtor’s personal property. A “blanket lien” version covers essentially all assets — receivables, inventory, equipment, and sometimes personal property as well. It survives a bankruptcy discharge because it is an in rem right against specific property, not a personal obligation. The discharge under 11 U.S.C. § 524(a) bars personal collection actions; it does not void consensual security interests in collateral unless a specific lien-avoidance tool is used.
Can Chapter 13 get rid of a second mortgage lien on my home?
Potentially yes — but only if the second mortgage is wholly unsecured, meaning the home is worth less than the balance owed on the first mortgage alone, leaving zero equity to support the junior lien. In that narrow situation, most bankruptcy courts allow Chapter 13 to strip the junior lien entirely, treating it as an unsecured claim discharged at plan completion. If there is any equity at all supporting the junior lien, strip-off is not available. You generally cannot use Chapter 13 to cram down (reduce the principal balance of) a first mortgage on your primary residence — that’s the anti-modification rule of 11 U.S.C. § 1322(b)(2), confirmed in Nobelman v. American Savings Bank, 508 U.S. 324 (1993).
Can I keep my car after Chapter 7 if there’s a lien on it?
Yes, with the right approach. Redemption under 11 U.S.C. § 722 lets you extinguish the lien by paying the lender the vehicle’s replacement value (per Rash) in a lump sum — even if you owe more than that. The difference is discharged. Note that § 722 applies only to personal-use consumer property, not vehicles used primarily for business. This applies to personal-use tangible property. Reaffirmation is the keep-and-pay option — you voluntarily re-incur personal liability to keep making payments and keep the car. An attorney can help you evaluate which makes more financial sense for your specific vehicle, balance, and situation.
I’m not an attorney, and what I share here is information, not legal advice for your situation. If you are dealing with a surviving lien after bankruptcy, working with a bankruptcy attorney who can review your actual documents is essential. NACBA (the National Association of Consumer Bankruptcy Attorneys) can help you find qualified counsel. If cost is a concern and you are a senior on a fixed income, HELPS serves that population specifically. For a broader debt-help consultation before you decide on a path, Damon Day offers a free initial conversation.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



