

A Get Out of Debt series · Reading the filings so you don’t have to
What They Told Wall Street
FORM 10-KSOFI TECHNOLOGIES, INC. (SOFI)FILED 02/17/2026FY ENDING 12/31/2025CIK 0001818874
“Private student loans can’t be discharged in bankruptcy” is one of the most repeated beliefs in personal finance — and one of the most profitable for lenders. So here’s what SoFi, one of the largest private student lenders in the country, wrote in its own annual report to investors this year.
This is not new ground for me. I’ve been walking people through how private student loan bankruptcy actually works for years, long before it was a headline — and I’ve written about real borrowers who did it, like the reader whose Earnest private loan was eliminated in bankruptcy. What’s new today is the receipt: the lender itself put the truth in writing, to Wall Street.
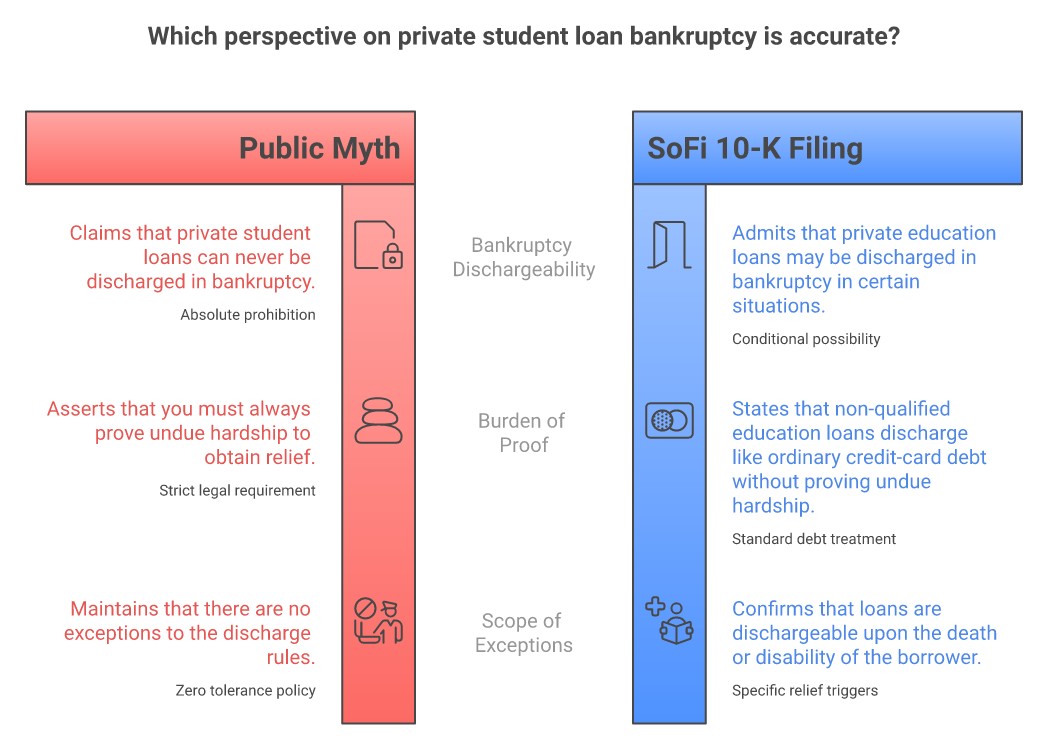
What everyone says
“Private student loans can never be discharged in bankruptcy. You’re stuck with them for life.”
What SoFi told the SEC
Its private education loans “may be discharged in bankruptcy in certain situations” — and it warns investors that number could grow.
For years, borrowers have been told that private student loans are the one debt bankruptcy can’t touch — that unlike credit cards or medical bills, these follow you forever. A lot of good people give up before they start because of it. But a company has to tell its investors the truth, and SoFi’s truth is more hopeful than the myth. A private company can spin a sales pitch to you. It cannot lie to Wall Street.
The disclosure
“Student loans are subject to discharge in certain circumstances. SoFi private education loans may be discharged in bankruptcy in certain situations, such as if a bankruptcy court determines that the loan is either not a qualified education loan … or determines that not discharging the debt would impose an undue hardship on the debtor and the debtor’s dependents. … A private education loan may also be generally dischargeable as a result of the death or disability of the borrower.”
What I think they’re really saying
Read plainly, this is SoFi telling its investors: “A meaningful slice of the private loans we hold can be wiped out in bankruptcy, so don’t assume this portfolio is bulletproof.” They have to warn Wall Street about it because it’s real. The very thing they’d never lead with in a loan pitch, they have to disclose under securities law. That’s my read of why this paragraph exists.
What the law actually says
Federal bankruptcy law does not protect every student loan. Under 11 U.S.C. § 523(a)(8), only three kinds of education debt survive bankruptcy without a special showing: loans made or guaranteed by the government or a nonprofit (most federal loans, which have their own discharge path I wrote about here); an “educational benefit, scholarship, or stipend”; and a “qualified education loan.”
If your loan is none of those three things, it can be discharged in bankruptcy much like an ordinary credit card, with no “undue hardship” showing required at all. It has to miss all three — missing just one isn’t enough. In 2021 a federal appeals court confirmed part of how that works: in Homaidan v. Sallie Mae, the Second Circuit held a private student loan is not an “educational benefit,” no matter how the money was paid out. That closes one of the three doors — the Fifth Circuit (Crocker v. Navient) and Tenth Circuit (McDaniel v. Navient) reached the same result — but it doesn’t open the exit by itself. So the real question for most private loans is the next one: is yours a “qualified education loan”?
One honest caveat about “like a credit card”: it means you don’t have to prove undue hardship, not that no one fights back. A lender that believes your loan is a qualified education loan can still contest which bucket it falls in, and the bankruptcy court would decide.
What the legal words actually mean
Qualified education loan
In plain English
This is the narrow kind of private loan that is hard to discharge. To count as “qualified,” a loan generally has to check all three boxes: it paid only for qualified higher-education expenses (tuition, fees, books, and a standard allowance for room, board, and supplies) up to the school’s certified cost of attendance; it was for an eligible student at a Title-IV school; and it fit the definition Congress wrote into the tax code (§ 221(d)(1)).
Here’s the empowering part: if your private loan fails even one of those tests, it may not be a qualified education loan — and a non-qualified loan can be discharged much like a credit card. The loans most likely to fail are the ones lenders pushed hardest:
- Loans your school never certified — “direct-to-consumer” loans a lender handed you without checking the amount against your school’s cost of attendance;
- Loans that covered more than the cost of attendance;
- Loans for coding bootcamps, bar-exam prep, or non-degree programs at schools that aren’t Title-IV eligible.
One caution so you don’t get your hopes up wrongly: the test is not “did the money land in my bank account.” Plenty of legitimate, school-certified loans get refunded to a checking account and are still fully protected. What matters is school certification against cost of attendance. And Title-IV eligibility can change over time, so confirm it for the moment you enrolled rather than assume it.
Undue hardship
In plain English
Even a qualified loan can be wiped out if repaying it would cause “undue hardship.” You ask the court for that finding in a step called an adversary proceeding, and the judge weighs your income, expenses, and whether things are likely to improve.
Be realistic, though. In most of the country the standard is still demanding — most courts use the strict three-part Brunner test, and how forgiving it is depends on your federal circuit. The good news is the process has grown less hostile: discharges are granted more often than they used to be. (In 2022 the Justice Department told its own attorneys to stop fighting these cases so hard — but that guidance governs cases where the federal government is the lender, not a private company like SoFi, which can still fight hard.) Ask an attorney what the standard looks like in your district before you pin your hopes on it.
Death or disability discharge — a separate door, not bankruptcy
In plain English
SoFi also discloses that a private loan can be discharged if the borrower dies or becomes permanently disabled. Understand this one correctly: it is not a bankruptcy remedy. You don’t file a case or an adversary proceeding — it’s a policy written into the loan agreement, and you request it directly from the lender. It also varies by lender, so read your own loan agreement or ask the servicer. Many families never find out and keep paying a loan that could have been forgiven.
What this means for you
If a private student loan is crushing you, do not accept “it can never be discharged” as the end of the conversation. The lender’s own SEC filing says otherwise. (If you’re drowning in private student loan debt, that piece walks through the wider picture.) Whether your loan can be discharged depends on the fine print of how it was made — a question for a professional, not a collections agent hoping you won’t ask.
What I’d do — Dig out your original loan documents: did your school certify the amount against its cost of attendance, or did the lender hand it straight to you? If the paperwork shows it was never certified, that single fact is often the strongest argument for discharge without proving undue hardship. Then talk to a consumer bankruptcy attorney — the National Association of Consumer Bankruptcy Attorneys is where I’d start (if a retainer’s out of reach, ask about a law-school bankruptcy clinic or legal aid) — and ask: “Is this a qualified education loan, and if not, can it be discharged?” Two cautions before you file: if someone co-signed, discharging your liability doesn’t protect them; and if a collector is suing you, ask whether the debt is past your state’s statute of limitations — a time-barred private loan may be beatable without bankruptcy at all.
Steve’s bottom line
The myth that private student loans are permanent isn’t an accident — it keeps people paying loans they might be able to shed, and keeps them from ever asking a lawyer the question. But the company holding the loan has to tell Wall Street the truth, and the truth is that a real share of these loans are dischargeable.
I’m not telling you your loan qualifies — I can’t know that without reading your paperwork. I’m telling you the door isn’t locked the way you’ve been told, and it costs nothing to find out if it’s open for you. Read what SoFi filed. Pull your documents. Ask the question.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
Frequently asked questions
Can a private student loan be discharged in bankruptcy?
Sometimes. If a private loan is not a “qualified education loan” and doesn’t fall into the other two protected categories, it can be discharged like ordinary credit-card debt, with no undue-hardship showing required. Even a qualified loan can be discharged on undue-hardship grounds. SoFi’s own SEC filing confirms its private loans “may be discharged in bankruptcy in certain situations.”
What is a “qualified education loan”?
It’s a narrow legal category, defined in Section 221(d)(1) of the Internal Revenue Code, for a loan that paid only qualified higher-education expenses up to the school’s certified cost of attendance, for an eligible student at a Title-IV school. If a private loan fails that definition, it is generally dischargeable in bankruptcy.
How do I find out if my private student loan qualifies?
Dig out your original loan documents. The key questions: Did your school certify the amount against its cost of attendance? Was it for a degree program at a Title-IV school? Did the loan exceed the cost of attendance? A consumer bankruptcy attorney can tell you whether it counts as a qualified education loan and, if not, whether it can be discharged.
Does the 2022 Justice Department guidance help with a private loan?
No. That guidance directs government lawyers to stop fighting discharge so hard in cases where the federal government is the lender. It does not bind a private lender like SoFi, though it reflects a broader softening in how these cases are treated.
Can a private student loan be discharged if the borrower dies or becomes disabled?
Often yes, but through the lender’s own policy, not through bankruptcy. You request a death-or-disability discharge directly from the lender, and the terms vary by lender, so read your own loan agreement or ask the servicer.
Is it true that private student loans can never be discharged in bankruptcy?
No, that’s a myth. SoFi’s own Form 10-K tells investors its private loans “may be discharged in bankruptcy in certain situations.” Whether yours can be discharged depends on how the loan was made and on current law.
Read it yourself — the primary source
SoFi Technologies, Inc. — Form 10-K, fiscal year ended Dec. 31, 2025 (SEC.gov) →
Filed with the SEC on February 17, 2026; the discharge language is in Item 1A, Risk Factors. (One heads-up if you read it yourself: the filing cites the tax-code definition as “225(d)(4),” which is a typo — the correct citation is 26 U.S.C. § 221(d)(1).) To find any company’s filings yourself, search the company name at sec.gov/edgar/search.
How to read this
Two different things appear above, kept separate on purpose. The quote in the gray box is fact — SoFi’s own words, from its own SEC filing, public record filed under penalty of law, quoted verbatim and linked. The plain-English explanations and the amber note are my interpretation, offered to help you understand the legal terms — not SoFi’s position, and not a statement about your specific loan.
Nothing here says SoFi has done anything wrong — I’m using its filing as evidence of the legal reality that runs across the whole private-student-loan industry, not as a criticism of SoFi. Whether any particular loan can be discharged depends on its facts and on current law, which changes. This is general information and my opinion after more than 30 years helping people with debt, not legal advice. Discharging a student loan requires a bankruptcy case and, usually, an adversary proceeding; talk to a licensed consumer bankruptcy attorney about your own situation before acting.
Know someone with a private student loan they think they’re stuck with? Please forward this to them. The whole reason this myth survives is that no one tells people the door might be open.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
“What They Told Wall Street” reads the SEC filings of the companies that handle your money and translates what they admitted — one filing at a time. Sourced entirely from public SEC records. · See the whole series →



