

Written by Steve Rhode, consumer debt expert since 1994 • Last updated July 22, 2026
Quick Answer: You received a state notice demanding repayment of unemployment insurance benefits — sometimes thousands of dollars. This is called a UI overpayment, and it carries real teeth: your tax refund can be intercepted, your future benefits reduced, and in some states your wages garnished. But you almost certainly have rights. Most states give you between 10 and 30 days to appeal — some as short as 10 to 14 days, so read your notice for the exact date. If the overpayment was not your fault, you may qualify for a complete waiver — meaning you owe nothing. Don’t ignore this notice. Act this week.
What Just Happened
Your state workforce agency — EDD in California, TWC in Texas, DES in North Carolina, DEO in Florida — determined that you were paid unemployment benefits you were not entitled to receive. The notice formally establishes an “overpayment” and starts the clock on your legal rights.
Overpayments happen for many reasons that have nothing to do with dishonesty: the agency made a calculation error, an employer reported wages on a different timeline, a pandemic-era eligibility rule was later reversed, or you received a lump-sum that the state counted differently than you did. In the pandemic years, states sent out billions in benefits under emergency rules and then spent years clawing back payments they later decided were wrong. The U.S. Department of Labor’s Office of Inspector General estimated tens of billions of dollars in established pandemic UI overpayments across all states. If you got a notice during or after 2020, you are not alone.
The Mistake You’re About to Make: Throwing the notice in a drawer because you can’t pay it. The appeal deadline — sometimes as short as 14 days in Texas — will expire while you’re stressed and ignoring it. Once it passes, you lose your right to challenge the state’s determination entirely. After that, the state can intercept your federal tax refund through the Treasury Offset Program, reduce your future benefits to recoup the balance (a larger share for fraud), and in some states pursue wage garnishment. Even if you can’t pay, filing an appeal this week preserves all your rights.
Your Options Right Now
What to Do in the Next 48 Hours
- Read the notice and find your deadline. Look for words like “appeal by” or “protest deadline.” In Texas you have 14 calendar days. In California and North Carolina you have 30 days. Your notice should state the exact date. If you have already missed it, file anyway — some states grant “good cause” extensions for late appeals.
- Determine: fraud flag or non-fraud? The notice will either say “non-fraud” (mistake or agency error) or “fraud” (the state believes you intentionally misrepresented something). This is the most important distinction in your case. Fraud overpayments carry a mandatory 15% federal penalty that cannot be waived, and the underlying fraud debt is generally non-waivable too. If you believe the fraud label is wrong, that finding itself is what you’re appealing.
- File your appeal in writing before the deadline. Most states have an official form (California: DE 1000M via EDD; Texas: online portal at TWC). A written letter to your state agency also works. State the facts: why the determination is wrong, what you actually reported, and any evidence you have. Keep a copy and get proof of submission. A timely appeal pauses aggressive collection (like tax-refund intercepts) in most states while the case is pending — but ask your agency in writing for a “stay of collection,” because some states still reduce your ongoing benefits during the appeal.
- If the overpayment was not your fault, request a waiver separately. A waiver is different from an appeal. An appeal contests whether you owe; a waiver asks the state to forgive the debt because repayment would cause hardship. Federal guidance from the DOL’s UIPL 20-21, Change 1 strongly encourages states to waive repayment when (1) the overpayment was not your fault AND (2) repayment would be “contrary to equity and good conscience” — which includes financial hardship but also other equitable factors, like relying on the benefits in good faith. (Federal law lets states waive non-fraud overpayments; it does not force them, so ask.) Ask your state workforce agency for a waiver request form.
- Get free legal help. UI appeals are legal proceedings. Find free legal aid through LSC.gov. For harder situations — fraud accusations, large balances, or identity theft — talk to Damon Day for free or find a consumer attorney through NACA.
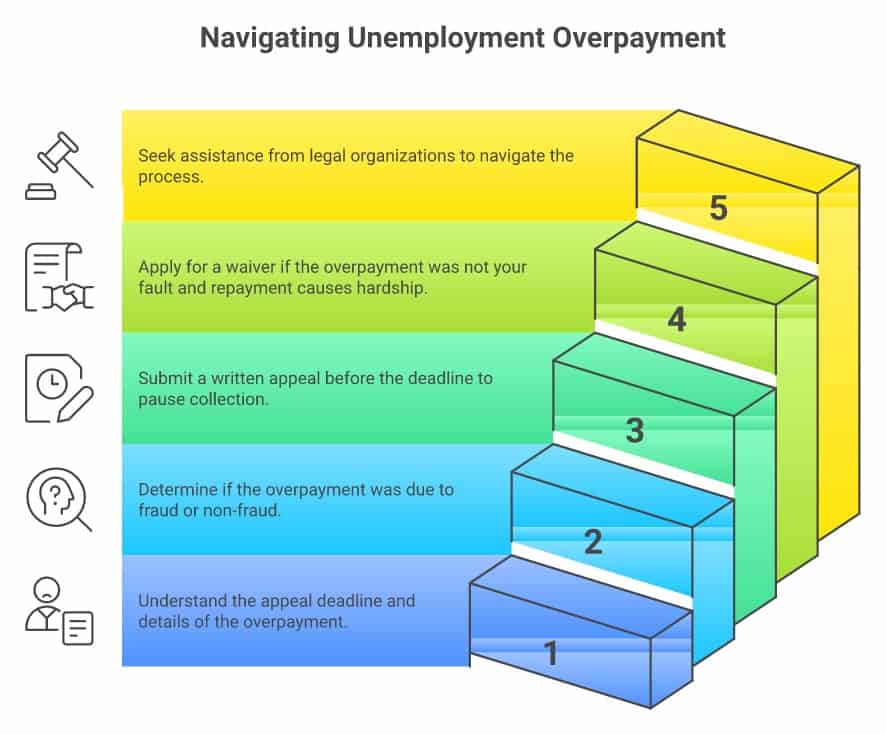
How to Actually Stop It — Your 4 Paths
- Appeal the determination (fastest path to zero). If the state made a factual error — wrong earnings calculation, wrong dates, a pandemic-era rule you relied on that was later reversed — an appeal is your first line of defense. You are challenging whether you actually owe the money at all. If you win, the overpayment is cancelled. Filing a timely appeal usually pauses aggressive collection while the case is pending — but request a stay of collection in writing, because some states keep offsetting your future benefits. Most people skip this because they don’t know they have it.
- Request a waiver (if you owe it but can’t repay it). If an appeal doesn’t resolve the matter, request a waiver. States are authorized — and, for pandemic-era benefits, were strongly encouraged — to offer waivers for non-fraud overpayments under the two-condition federal test in the DOL UIPL 20-21 guidance (PDF). For pandemic-era benefits (PUA, FPUC, PEUC), federal blanket waiver categories may also apply — ask your state agency specifically. Note: Texas state UI law provides no waiver mechanism for regular state benefits, so Texas claimants must focus on the appeal.
- Negotiate a repayment plan. Most states will accept structured repayment. Ask before they send you to offset. Get the plan in writing before paying anything. Being on a current repayment plan will, in many states, keep your debt out of the tax-refund intercept — but confirm that in writing with your agency.
- What won’t work: ignoring it. The state does not need a court judgment to seize your federal tax refund. Under 26 U.S.C. § 6402(f) and 31 C.F.R. § 285.8, once submitted to the Treasury Offset Program, your refund disappears automatically. Silence accelerates collection. It does not stop it.
What You Need to Know About the Legal Rules
10–30
days to appeal — varies by state, some as short as 10–14 (Texas 14; CA & NC 30). Check your notice for the exact date.
15%
mandatory federal penalty on fraud overpayments — on top of the full balance
60 days
minimum notice required before tax refund can be intercepted via Treasury Offset Program
$0
you could owe after a successful waiver if the overpayment was not your fault
State UI programs must comply with federal requirements under 42 U.S.C. § 503 of the Social Security Act, which governs state overpayment recovery practices. The 15% fraud penalty is mandated by federal law under 42 U.S.C. § 503(a)(11). Tax refund intercepts are authorized under 26 U.S.C. § 6402(f) and governed by 31 C.F.R. § 285.8, which sets the 60-day notice requirement and $25 minimum debt threshold before states can submit debts to the Treasury Offset Program. The waiver framework — the two-condition federal test and pandemic blanket waiver authority — lives in DOL UIPL 20-21, Change 1.
| State | Appeal Window | Waiver Available? | Notes |
|---|---|---|---|
| Texas (TWC) | 14 calendar days | No (state benefits); pandemic only | Shortest window found; no state waiver for regular UI; TWC overpayments page |
| California (EDD) | 30 days from mailing | Yes — income-based hardship test | Late appeals for “good cause”; EDD overpayments page |
| North Carolina (DES) | 30 days | Yes — federal two-condition test | Reduces ongoing benefits to recover (a larger share for fraud); DES overpayment FAQs |
| Florida (DEO) | 20 calendar days | Yes (federal programs) | Dedicated waiver portal at raoverpayments.floridajobs.org |
| Federal baseline | Varies by state (no federal minimum) | Yes — non-fraud | 60-day TOP notice required; DOL UIPL 20-21 governs waivers |
If you are an identity theft victim flagged as “fraud”: states sometimes classify an account as fraud when someone else used your identity to claim benefits. This is not your fault. File a report with the FTC at IdentityTheft.gov, notify your state workforce agency in writing immediately, and appeal the fraud classification. Documentation is critical and legal aid can help — find it through LSC.gov.
If your state workforce agency is violating federal notice requirements or improperly intercepting your funds, file a complaint with the U.S. Department of Labor’s Employment and Training Administration or the DOL Office of Inspector General, and your state attorney general. If you need legal help and can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990. I know what it feels like to have a government agency demanding money you don’t have. Here’s what I’ve watched happen to thousands of people in exactly this situation: the ones who opened the notice, filed the appeal on time — even if they didn’t know exactly what to say — and asked for a waiver did dramatically better than the ones who froze. The people who ignored it lost tax refunds they needed, had future benefits zeroed out, and sometimes faced wage garnishment. The notice is designed to look final. It isn’t. You still have choices — but they expire fast. File the appeal in writing today and worry about being perfect later. You can strengthen an argument. You cannot un-miss a deadline.
Free Tool — Wage Garnishment Calculator: Worried about your paycheck being seized? The free Wage Garnishment Calculator shows exactly how much creditors can legally take in your state — and some states prohibit garnishment entirely. Calculate My Risk →
Frequently Asked Questions
I got a notice saying I was overpaid unemployment — do I actually have to pay it back?
Maybe — but not necessarily, and not necessarily the full amount. You have two separate options: appeal (challenge whether you owe it) and waiver (ask the state to forgive repayment because it wasn’t your fault and would cause hardship). Most states must consider both. The notice is not the final word until your appeal deadline has expired.
What is the difference between a fraud and non-fraud unemployment overpayment?
A non-fraud overpayment means you were paid benefits you weren’t entitled to, but there was no intentional misrepresentation — it could be an agency error, a timing issue with reported earnings, or a reversed eligibility rule. A fraud overpayment means the state believes you intentionally provided false information. This matters enormously: non-fraud overpayments can be waived; fraud overpayments carry a mandatory 15% federal penalty under 42 U.S.C. § 503(a)(11) that cannot be waived, and the fraud debt itself is generally non-waivable. If you believe a fraud classification is wrong, that determination itself is what you appeal.
Can the state take my tax refund without going to court?
Yes. Under 26 U.S.C. § 6402(f), states can submit UI overpayment debts to the federal Treasury Offset Program (TOP), which intercepts your federal tax refund automatically — no court order required. Under 31 C.F.R. § 285.8, the state must give you at least 60 days’ written notice and an opportunity to dispute before submitting. If you are current on a repayment plan, many states will hold off on the TOP submission — confirm this in writing with your agency.
What is a UI overpayment waiver and how do I get one?
A waiver is the state’s decision to forgive the entire debt. Federal guidance from the DOL UIPL 20-21 strongly encouraged states to offer waivers when two conditions are met: (1) the overpayment was not your fault, and (2) repayment would be contrary to equity and good conscience — which includes financial hardship but also other equitable factors, such as having relied on the benefits in good faith. Federal law lets states waive non-fraud overpayments; it does not compel them. Ask your state workforce agency for a waiver request form. If the overpayment is from a pandemic-era program (PUA, FPUC, or PEUC), ask specifically whether a federal blanket waiver category covers your situation.
Can they garnish my wages for an unemployment overpayment?
Yes, though the path varies by state. Some states can file civil actions and obtain court judgments allowing wage garnishment. California can obtain a court judgment; Texas generally cannot garnish wages for this kind of debt and instead recovers through benefit offset, the Treasury Offset Program, or a civil lawsuit. This typically takes longer than tax refund offset, which is why acting before the debt reaches the judgment stage matters. If garnishment is already happening, read the wage garnishment crisis guide for your immediate options.
I received pandemic benefits (PUA, FPUC, or PEUC) and now they want the money back — is there a special waiver for that?
Possibly — and it may be your strongest path. The DOL UIPL 20-21 and its Change 1 specifically authorized states to grant blanket waivers for categories of pandemic-era overpayments where claimants were not at fault. States were “strongly encouraged” to use this authority. Contact your state workforce agency and ask explicitly whether a blanket waiver applies to your program and date range.
My appeal deadline already passed — is it too late?
Not necessarily. Many states accept late appeals if you had a valid reason for missing the deadline — illness, an old address, never receiving the notice. File your appeal anyway and explain the circumstances in writing; request a good-cause exception. A consumer attorney through NACA or free legal aid through LSC.gov can help you make the strongest case for a late filing.
I filed for bankruptcy — does that wipe out an unemployment overpayment debt?
It depends on the type. Non-fraud UI overpayments are generally dischargeable as general unsecured debts in bankruptcy. Fraud-based overpayments may be non-dischargeable under 11 U.S.C. § 523(a)(2) — but only if the state files a separate lawsuit (an “adversary proceeding”) in your bankruptcy and proves fraud; many agencies never do, so even a fraud-labeled overpayment is often discharged. Regardless, the automatic stay under 11 U.S.C. § 362 takes effect the moment you file, immediately pausing wage garnishment and most collection action. NACBA can connect you with a bankruptcy attorney.
One more thing — everything I share here is based on over 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A UI overpayment notice is serious but rarely final. File your appeal before the deadline — even if you’re unsure you’ll win — because missing it locks in the debt permanently. If the overpayment wasn’t your fault, request a waiver separately. Use this tool to see all your debt relief options. Get free legal aid or talk to a consumer attorney this week. The longer you wait, the fewer options you have.
The Bottom Line
Getting a UI overpayment notice doesn’t mean you did anything wrong — states make errors, pandemic rules changed overnight, and millions of people are in exactly this situation. The system built in appeal and waiver protections specifically because it knew mistakes would happen. The people who act quickly — who open the letter, file the appeal, and ask for the waiver even when they’re terrified — do dramatically better than those who freeze. If someone you know just got one of these notices, send them this page — the deadline is measured in days, not weeks, and most people have no idea they have rights here at all. See the Find Your Path quiz for a broader look at your debt options.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 9): The paycheck advance app said it wasn’t a loan. Connecticut just made it give every fee back.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



