

A Get Out of Debt series · Reading the filings so you don’t have to
What They Told Wall Street
FORM 8-K (EX-99.1)SYNCHRONY FINANCIAL (SYF)FILED 07/21/2026Q2 ENDING 06/30/2026CIK 0001601712
The credit card company behind tens of millions of American store cards — the CareCredit health card, the Lowe’s Advantage Card, the Dick’s Sporting Goods card, and hundreds more — filed its second-quarter earnings with the SEC on July 21, 2026. Buried in the forward-looking statements was a sentence about the consumer protection that was supposed to cap your late fee at $8.
I’ve been writing about the real cost of carrying a credit card balance for over 30 years. I know the math rarely favors the cardholder. What a company files with the SEC, though, is different from a marketing brochure. It has to be true. And companies often admit things to Wall Street that they would never say in a commercial.
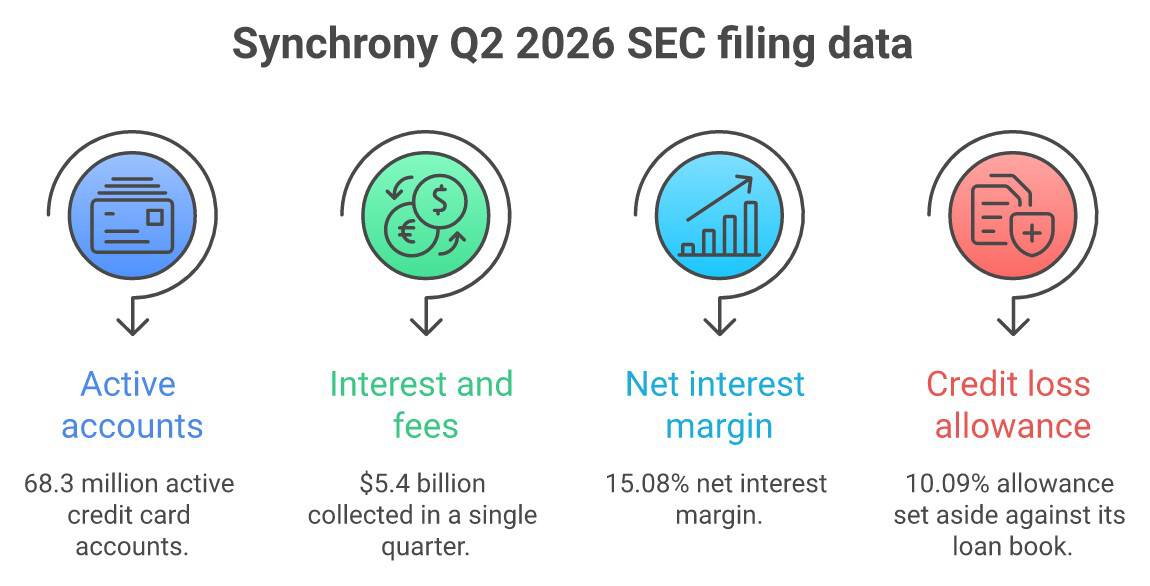
Synchrony Financial is one of the largest private-label credit card issuers in the United States. You probably carry one of its cards without even knowing Synchrony is behind it — Lowe’s, Amazon, CareCredit, Dick’s Sporting Goods, Venmo, and hundreds more store and healthcare cards are all Synchrony products. As of June 30, 2026, Synchrony held $102.2 billion in credit card receivables across 68.3 million active accounts. On July 21, 2026, it filed its second-quarter earnings with the SEC. Here is what it told Wall Street.
Q2 2026
June 30, 2026
Q2 2026 alone
Source: Synchrony Financial Q2 2026 Earnings Release, Exhibit 99.1 to Form 8-K filed July 21, 2026 with the U.S. Securities and Exchange Commission.
Disclosure 1 — the $8 late fee rule that was supposed to help you
“product, pricing, and policy changes related to the Consumer Financial Protection Bureau’s (the “CFPB”) final rule on credit card late fees, which was vacated in April 2025“
What I think they’re really saying
The CFPB spent years building a rule that would have capped credit card late fees at $8. Synchrony, like the rest of the card industry, had every reason to oppose it — the industry charges roughly $30 to $41 (the pre-rule federal safe-harbor range) on a typical late payment today, and the trade groups that represent big issuers fought the rule in court. When a court vacated the rule in April 2025, the fee protection consumers were promised disappeared. Synchrony is now telling investors: the whole area of how much we can charge you when you’re late — and what we did or didn’t do in response to that rule — is a material factor in how we run this business. They have to disclose it because it’s real. That’s my read of why this sentence is in the document.
CFPB credit card late fee rule
In plain English
In March 2024, the Consumer Financial Protection Bureau finalized a rule that would have capped credit card late fees at $8 for large card issuers (those with more than a million accounts — which includes Synchrony). The credit card industry challenged it in federal court. A judge blocked it, and as Synchrony’s own filing confirms, the rule was vacated in April 2025.
What that means for you: the fee ceiling you were promised never went into effect. If you pay a late fee on a Synchrony card today, it is almost certainly in the range of $30 to $41, not $8. The CFPB’s own rule announcement estimated the change would have saved the average cardholder who is charged a late fee roughly $220 a year.
What this means for you — Disclosure 1
The consumer protection that would have capped your late fee is gone. That’s not a reason to panic — it’s a reason to know your exact exposure. Log into your Synchrony account and find your Schumer Box or “Summary of Credit Card Terms.” Know your actual late fee, your actual APR, and your actual minimum payment. You cannot manage what you don’t know.
What I’d do — If you’ve been charged fees you believe were not clearly disclosed, file a complaint at consumerfinance.gov/complaint. The CFPB still takes complaints even without the late-fee rule. If credit card debt has become unmanageable, understand all your options now before interest and fees compound the problem further.
Disclosure 2 — how they describe consumer pricing limits to investors
“the impact of changes made or influenced by the U.S. presidential administration and Congress on fiscal, monetary and regulatory policy, including with respect to constraints on the pricing of our credit products“
What I think they’re really saying
This is the plainest possible statement: any regulation that limits how much Synchrony can charge you — for late fees, interest rates, or any other product pricing — is a business risk they must disclose to investors. It’s a perfect mirror. What protects you costs them, and the SEC filing is where they have to say it out loud. They’re not announcing what they plan to charge. They’re telling investors what they’re watching. That’s my read. Read the document yourself.
Disclosure 3 — the interest and fee math, one quarter at a time
“Interest and fees on loans increased $52 million, or 1% to $5.4 billion” … “Net interest margin increased 30 basis points to 15.08%” … “average active accounts were flat at 68.3 million“
What I think they’re really saying
$5.4 billion in interest and fees from 68.3 million active accounts in one quarter. That averages to roughly $79 per active account for the three months ending June 30 — or about $316 a year, just in interest and fees, on average. That average is diluted by the millions of accounts paid in full each month (which pay $0 interest); accounts that carry a balance pay far more. The 15.08% net interest margin means that for every dollar of cardholder debt Synchrony holds, it earns 15 cents more per year than it pays to borrow the money. That gap is the business model. It comes from cardholders who carry balances, and it is working exactly as designed.
Net interest margin
In plain English
Net interest margin is the gap between what Synchrony earns in interest from cardholders and what it pays to borrow the money it lends out. Synchrony’s 15.08% margin is high — for comparison, a typical bank’s net interest margin runs 2 to 4 percent. Private-label credit card companies run higher because their cards carry elevated interest rates and serve customers who often carry balances month to month. For a cardholder, the practical meaning is simple: every month you do not pay your balance in full, that 15-percent-plus gap is working for Synchrony and against you.
Disclosure 4 — the delinquency picture behind the earnings headline
“Loans 30+ days past due as a percentage of total period-end loan receivables were 4.16%” … “Loans 90+ days past due as a percentage of total period-end loan receivables were 2.01%” … “Net charge-offs as a percentage of total average loan receivables were 5.43%” … “The allowance for credit losses as a percentage of total period-end loan receivables was 10.09%“
What I think they’re really saying
That 4.16% is measured against total loan receivables — dollars, not accounts — so it works out to roughly $4.25 billion in balances at least 30 days past due, with about $2 billion 90 or more days behind. (Because it’s a share of dollars, not people, there’s no clean way to say how many households that is.) And Synchrony booked an allowance for credit losses of 10.09 cents on every dollar of receivables — an accounting reserve of roughly $10 billion (an expected-loss provision against the loan book, not a pile of cash) — because it expects that share of loans not to come back. Synchrony’s own earnings materials framed these credit metrics in positive terms. From the cardholder side, these are the people the math has won against. I’m not saying Synchrony caused it. I’m saying that at this scale, billions of dollars are past due, and behind those balances are a lot of struggling households. And if you are in that group, you have more options than you may realize.
Allowance for credit losses
In plain English
Under accounting rules, lenders must set aside reserves for loans they expect to lose. When Synchrony reports a 10.09% allowance for credit losses, it is saying: for every $100 in outstanding credit card balances, I expect roughly $10 to go uncollected. This is not a surprise to the company — it is a planned cost built into their business model. They priced that into your interest rate before you ever applied for the card. It also tells you something about who carries their cards: this is a customer base with meaningful financial stress, and Synchrony knows that.
What this means for you — all four disclosures together
If you carry a balance on a Synchrony card, you are paying a premium to do it. The fee protection that would have limited what you pay when you’re late is gone. The company earned $5.4 billion in fees and interest from people like you in a single quarter. And one in ten dollars they’re owed right now is expected to go uncollected — meaning millions of cardholders are already in trouble.
None of that means you are stuck. I have written for over 30 years about how people get into credit card debt and how they get out. The range of options is wider than card companies would like you to know. Before you make any major decision about this debt, take the 2-minute bankruptcy quiz and see what the same series found when I read SoFi’s filing — companies tell Wall Street things they would never say in a sales pitch.
What I’d do — Pull your Synchrony cardholder agreement right now. Write down your APR, your late fee, and your minimum payment. Then run the minimum-payment math: most statements include a disclosure showing how long it takes to pay off the balance at the minimum. The number is almost always shocking. From there, decide what to do with that information — but do it with the real numbers in front of you, not the ones Synchrony would prefer you focus on.
Steve’s bottom line
Synchrony Financial filed its quarterly earnings with the SEC this week and confirmed that the CFPB rule meant to cap your late fee at $8 was vacated. It told investors that any regulatory limits on how it prices credit products are a business risk. It collected $5.4 billion in interest and fees from 68.3 million cardholders in three months. And it set aside 10 cents of every dollar in outstanding loans because it expects them not to be repaid.
None of that makes Synchrony villainous. It is a public company doing what public companies do: making money within the rules it operates under. But you are not a line item. You are a person who may not have all the information Synchrony’s investors just received. Now you do.
Debt is math wrapped in emotion. The math is in the filing. The filing is public. I read it so you don’t have to — but the link is below if you want to verify every word yourself.
Frequently asked questions
What is Synchrony Financial?
Synchrony Financial (NYSE: SYF) is one of the largest private-label credit card issuers in the United States. It issues credit cards under the brands of hundreds of retailers and healthcare providers, including Lowe’s, Amazon, CareCredit (health and veterinary financing), Dick’s Sporting Goods, Venmo, and many more. As of mid-2026, it holds $102.2 billion in credit card receivables across 68.3 million active accounts.
Was the CFPB credit card late fee cap vacated?
Yes. Synchrony’s Q2 2026 earnings filing — furnished to the SEC on July 21, 2026 — states that the CFPB’s final rule on credit card late fees “was vacated in April 2025.” The rule would have capped late fees at $8 for large card issuers. It was challenged in federal court by the banking industry and was blocked before it ever took effect.
What late fees can Synchrony charge now?
Without the vacated $8 cap, Synchrony and other large card issuers can charge fees in the $25–$41 range, which is the standard that existed before the CFPB rule was proposed. Your exact fee is stated in your cardholder agreement — look for the Schumer Box or the “Fees” section of your terms.
What does a 15% net interest margin mean for me?
It means that for every dollar you carry as a balance, Synchrony earns about 15 cents more per year than it pays to fund that dollar. But NIM is Synchrony’s net spread after its own funding costs — not the APR on your card. Your card’s APR is likely much higher (often 25–30%+): on a $5,000 balance that’s roughly $1,250–$1,500 a year in interest, and the ~15% margin is what Synchrony keeps after paying to fund the money. Every month you carry a balance, it compounds.
What should I do if I am struggling to pay a Synchrony card?
Start by knowing your real numbers: your APR, your late fee, and how long minimum payments will take to clear your balance (your statement should show this). Then look at all your options, not just the ones Synchrony would suggest. Those include balance-transfer cards, nonprofit credit counseling, debt management plans, and bankruptcy — for which Federal Reserve Bank of New York research shows filers recover faster than those who don’t file. Take the 2-minute bankruptcy quiz before you rule any path out.
Where can I file a complaint about a Synchrony credit card fee?
The Consumer Financial Protection Bureau takes complaints at consumerfinance.gov/complaint, even without the late-fee rule in effect. You can also file with your state attorney general’s consumer protection office. Synchrony’s complaint history is searchable in the CFPB’s public complaint database.
Read it yourself — the primary source
Synchrony Financial — Q2 2026 Earnings Release (Exhibit 99.1 to Form 8-K, July 21, 2026, SEC.gov) →
Filed with the U.S. Securities and Exchange Commission on July 21, 2026. The late-fee language is in the “Factors that could cause actual results to differ materially” section of the forward-looking statements. The interest, fee, margin, and credit quality metrics are in the Key Operating and Financial Metrics and Credit Quality sections. Verify the filing index at:
Filing index — Form 8-K, Accession No. 0001601712-26-000030 →
To find any company’s SEC filings yourself: sec.gov/edgar/search → type the company name.
How to read this
Two different things appear above, kept separate on purpose. The quotes in the document blocks are fact — Synchrony Financial’s own words from its own SEC filing, public record furnished to the U.S. Securities and Exchange Commission, quoted verbatim and linked above so you can verify them yourself. The plain-English explanations and the amber notes are my interpretation — offered to help you understand financial terms, not Synchrony’s position, and not a statement about your specific account or situation.
Nothing here says Synchrony has done anything wrong. Synchrony is a public company operating within the legal framework that governs credit card lending in the United States. I am using its public disclosure to explain the financial environment cardholders are navigating, not to make a claim about Synchrony’s conduct. This is general information and my opinion after more than 30 years helping people with debt, not legal or financial advice. If you are struggling with credit card debt, talk to a licensed consumer bankruptcy attorney or a nonprofit credit counselor about your specific situation before taking any action.
Know someone carrying a Synchrony card balance they don’t know how to handle? Forward this to them. This information is public record — most people just don’t know where to look.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
“What They Told Wall Street” reads the SEC filings of the companies that handle your money and translates what they admitted — one filing at a time. Sourced entirely from public SEC records. · See the whole series →



