

Written by Steve Rhode, consumer debt expert since 1994 • Last updated July 23, 2026
Quick Answer: A merchant cash advance (MCA) company can freeze your bank account three ways: they got a court judgment — often through a confession of judgment you signed at closing — and served your bank a restraining notice; they hold contractual control over your account through a Deposit Account Control Agreement (DACA); or a court granted a prejudgment attachment. Call your bank today and demand the actual paperwork behind the freeze. A motion to vacate can unfreeze funds within days if grounds exist, and filing bankruptcy stops it instantly. Don’t ignore this — it gets worse, not better.
What Just Happened to Your Bank Account
An MCA company isn’t legally a “lender” — it calls the advance a purchase of your future receivables, which is exactly why it can move faster than a bank and why federal consumer-lending protections don’t apply. The FTC’s ban on confessions of judgment (16 CFR § 444.2) only covers consumer credit. The contract you signed for your business is “commercial,” so that protection doesn’t reach it. (For the fuller research on how factor rates, brokers, and the “purchase not a loan” structure actually work, see my deep-dive on merchant cash advance data.)
A freeze usually comes from one of three places. A confession of judgment (COJ) plus a restraining notice — you signed away your right to a hearing when you took the advance, and after a default, the funder can walk that signed confession into a courthouse, get a judgment entered without ever notifying you, and serve your bank a restraining notice. In New York a funder can enter a confession of judgment under CPLR § 3218 and then serve your bank a restraining notice under CPLR § 5222 — a process that can move in a matter of days. A Deposit Account Control Agreement (DACA) — some newer MCA contracts skip the courthouse entirely by giving the funder direct contractual control of your account through the bank itself, so the bank blocks or sweeps funds the moment you default, no judge involved. A prejudgment attachment — in some states a court can freeze assets before any final judgment if the funder convinces a judge you’re likely to move money to avoid paying.
One thing a freeze is not: a UCC-1 filing by itself. That’s the “lien” notice most MCA agreements mention — a public record of a claim on your future receivables (UCC § 9-406). It does not, on its own, let anyone touch your bank account. If your account is frozen, something more than a UCC filing happened — find out what.
The Mistake You’re About to Make: Signing whatever “settlement,” “forbearance,” or “restructuring” agreement the funder faxes over within 24 hours, just to get the freeze lifted. These emergency offers routinely bury a new confession of judgment or an even more aggressive DACA inside the fine print — so you trade today’s freeze for a faster, bigger one the next time you’re late. Get the actual court order or DACA paperwork first, and find out whether the freeze itself is even valid, before you agree to anything.
Your Options Right Now
What to Do in the Next 48 Hours
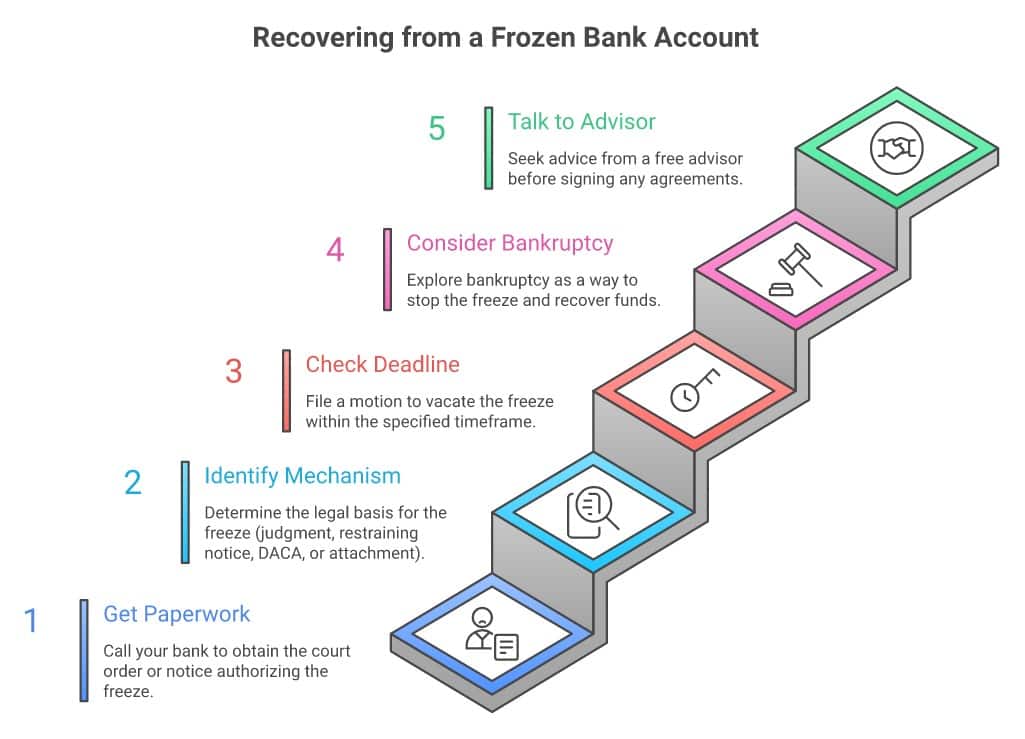
- Get the actual paperwork today. Call your bank’s legal or levy department and demand a copy of the restraining notice, court order, or DACA that authorized the freeze. Banks are required to be able to tell you what triggered it — a freeze with nothing behind it is worth challenging on that basis alone.
- Identify which of the three mechanisms hit you. A judgment and restraining notice, a DACA, or a prejudgment attachment — each has a different path forward, so this determines everything you do next.
- Check the deadline and your grounds to fight it. If it’s a judgment, courts expect you to move fast — file within days, not weeks. Grounds include lack of personal jurisdiction (a New York COJ signed by an out-of-state business after August 2019 is void under CPLR § 3218), improper service, usury, or fraud (CPLR § 5015).
- Consider bankruptcy — it can stop the freeze the instant you file. The automatic stay under 11 U.S.C. § 362 halts a restraining notice, a DACA sweep, or any collection action the moment your case is filed — and it can sometimes recover funds already frozen through a turnover motion. NACBA can connect you with a bankruptcy attorney who handles business cases, and my bankruptcy quiz can help you think through whether it fits your situation.
- Talk to Damon Day for free before you sign anything with the funder. Talk to Damon Day for free.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
How to Actually Stop It — Your 4 Paths
- Bankruptcy. The fastest full stop available. The automatic stay takes effect the moment you file — not weeks later — and can force a turnover of funds a funder already swept. Federal Reserve Bank of New York research shows filers recover faster than those who keep fighting collection alone.
- An emergency motion to vacate the judgment. If the freeze traces back to a confession of judgment, a motion to vacate can unfreeze the account within days when real grounds exist — wrong jurisdiction, no proper service, or fraud in how the judgment was obtained. This is a specific court filing, not a phone call to the funder.
- A negotiated workout — with your own lawyer reading it first. Funders will deal once they know you’re prepared to fight. Get any agreement in writing, confirm exactly what happens to the freeze and when, and never sign a second confession of judgment blind just to make today’s problem go away. That same judgment can also be recorded as a lien against any real estate you own — it doesn’t force a sale, but it will need to be cleared before you can sell or refinance.
- What won’t work: hoping it resolves itself, letting scheduled MCA debits keep hitting a frozen account (they’ll bounce and add NSF fees on top of everything else), and taking out another advance to cover the gap. Many businesses that take an MCA end up straining under the daily or weekly debits within months — stacking a second one on a frozen account rarely ends well. See what happens if you default on an MCA for the full picture of what comes after a freeze if it isn’t resolved.
What You Need to Know About the Rules
How fast a New York confession of judgment can become a bank restraining notice
Typical effective APR range on a merchant cash advance
Small-business debt New York’s Attorney General forced one MCA funder to cancel
Years New York and California, respectively, restricted or banned confessions of judgment
There is no federal law that specifically regulates confessions of judgment in commercial contracts, and merchant cash advances sit in a regulatory gap that most other financing doesn’t — they’re structured as a purchase of future receivables rather than a loan, which is exactly how they sidestep the rules that cover ordinary business lending.
| Jurisdiction | Confession of Judgment Rule | Notes |
|---|---|---|
| Federal baseline | Banned only in consumer credit (16 CFR § 444.2) | Your MCA contract is “commercial,” so this rule doesn’t reach it |
| New York | Banned against out-of-state residents since Aug. 2019 (CPLR § 3218) | Still enforceable against New York residents; restraining notices governed by CPLR § 5222 |
| California | Banned entirely for judgments entered on or after Jan. 1, 2023 (CCP § 1132) | Confessions signed and entered before that date can still be enforced |
| Pennsylvania | Still allowed in commercial contracts (Pa.R.C.P. 2950–2974) | One of the most funder-friendly states in the country |
| Ohio | Still allowed under Ohio Rev. Code § 2323.13 | Requires specific statutory warning language in the contract |
If your business is in California, or your MCA contract’s confession of judgment was entered on or after January 1, 2023 — it’s unenforceable outright, which may be grounds to vacate any resulting judgment. If you’re outside New York and a funder filed a COJ against you in a New York court after August 2019, jurisdiction is likely a strong argument. See the complete guide to confessions of judgment for the mechanics.
If your bank won’t produce the paperwork behind the freeze, or a funder used a DACA you don’t remember agreeing to, file a complaint with your state attorney general (the fastest route for a business account) and the CFPB. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov — many legal aid clinics represent small business owners in confession-of-judgment vacatur motions.
Steve’s Take
I filed bankruptcy in 1990, and I’ve spent over 30 years since talking to people at the exact moment the paperwork lands. I never ran an MCA business, but I’ve heard from hundreds of small business owners who took one while desperate for fast cash — and the freeze is always the moment reality shows up. The paperwork is legal. That doesn’t make it right, and it doesn’t mean you’re out of options. No sense wasting a perfectly good mistake — find out exactly what happened, get real advice, and decide with clear eyes instead of panic.
Frequently Asked Questions
A merchant cash advance company froze my bank account — is that even legal?
It can be, but only if they have a valid court judgment and restraining notice, or contractual control over the account through a Deposit Account Control Agreement. Ask your bank for the specific paperwork. If they can’t produce a judgment, a court order, or a DACA you signed, the freeze itself may be improper — that’s worth challenging.
I never got sued — how can there already be a judgment against me?
Most likely you signed a confession of judgment when you took the advance — a clause where you agreed in advance to let the funder enter a judgment against you without a lawsuit or a hearing. In states that still allow it, like Pennsylvania and Ohio, the funder can go straight to a court clerk with your signed confession and get a judgment entered.
Can I get my money back if the freeze was wrongful?
Yes, potentially. If a court vacates the judgment behind the freeze, or if you file bankruptcy, funds a funder already swept from your account can sometimes be recovered through a turnover motion. This is exactly the kind of specific legal action worth talking to an attorney about right away.
How fast does filing bankruptcy stop an MCA bank freeze?
The automatic stay under 11 U.S.C. § 362 takes effect the moment your case is filed — not weeks later. It halts a restraining notice, a DACA sweep, and any other collection action against you immediately.
Is a UCC lien the same thing as my bank account being frozen?
No. A UCC-1 filing is a public notice of a claim on your business’s future receivables under UCC § 9-406. By itself, it does not give a funder the power to freeze your bank account — that takes a court order or a DACA.
What if I live outside New York but my MCA contract says New York law applies?
If a confession of judgment was signed by an out-of-state resident and filed in New York after August 2019, it’s unenforceable under CPLR § 3218. That’s often a strong basis for a motion to vacate the judgment behind your freeze.
Can the MCA company freeze my personal bank account too?
Yes, if you signed a personal guarantee — and most MCA agreements require one. See what to do if your business failed and you personally guaranteed the loan for how personal exposure works.
Will negotiating directly with the funder get the freeze lifted faster?
Sometimes, but be careful. Get the freeze mechanism identified first, and never sign anything — especially a new settlement or forbearance agreement — without your own attorney reviewing it. Emergency “workout” offers routinely bury another confession of judgment inside the fine print.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A frozen account is serious but rarely permanent. Find out which of the three mechanisms hit you, check the deadline to fight it, and talk to an attorney this week — the bankruptcy quiz can help you think through whether the automatic stay is your fastest path. The longer you wait, the fewer options stay open.
The Bottom Line
Taking a merchant cash advance to keep your business alive doesn’t make you reckless — it makes you a business owner who was trying everything. The system that let a funder freeze your account this fast is also the same system that gives you specific, enforceable rights to fight back, and the business owners who moved quickly and got real advice did better than the ones who waited and hoped. If you know another business owner dealing with a frozen account right now, send them this page — the 48-hour window matters more than they may realize. For a fuller picture of how MCAs work and what default really costs, see the complete crisis guide library and the Find Your Path quiz.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



