

Written by Steve Rhode, consumer debt expert since 1994 • Last updated July 24, 2026
Quick Answer: Once your bankruptcy court grants your discharge, it becomes a permanent federal court order — an injunction under 11 U.S.C. § 524 — that legally bars every creditor and debt collector, forever, from trying to collect that specific debt again, in any state. If one is still calling, billing you, reporting it to a credit bureau as owed, or suing you on it, they are violating a federal court order, not just being annoying. Document every contact, then go back to the same bankruptcy court that granted your discharge and ask it to hold them in contempt. You do not need to file a new case. Don’t ignore it — it doesn’t stop on its own. (One caveat: this assumes the debt was actually part of your bankruptcy and legally discharged — if you’re not certain a specific debt was included and wiped out, check your discharge paperwork or ask your attorney before treating a collection attempt as a violation.)
What Just Happened After Your Discharge
When your bankruptcy case closed, the court sent every creditor on your case an official Notice of Bankruptcy Discharge. That notice announced the discharge injunction — the permanent legal wall that means you no longer owe the debt and no one can try to collect it, according to the U.S. Courts’ own explanation of a discharge in bankruptcy.
But paperwork gets missed. A creditor’s collections software may never get updated. Or the account was sold to a debt buyer or new collector after your case closed, and instead of checking the bankruptcy court’s public record, they just started billing you as if nothing happened. None of that makes it your job to quietly sort out. It makes it a federal court order violation — and the same court that erased the debt has the power to make them stop.
The Mistake You’re About to Make: Paying it, or arguing with the collector on the phone to make it go away. A payment doesn’t legally revive a debt the court already erased, but it hands a paper trail to a collector who is already ignoring a federal court order — and in some states it can restart a separate statute-of-limitations clock on state-law claims. Arguing by phone leaves no proof for the judge who decides whether to hold them in contempt. Get everything in writing instead, and let your discharge order — not your patience — do the talking.
Your Options Right Now
What to Do in the Next 48 Hours
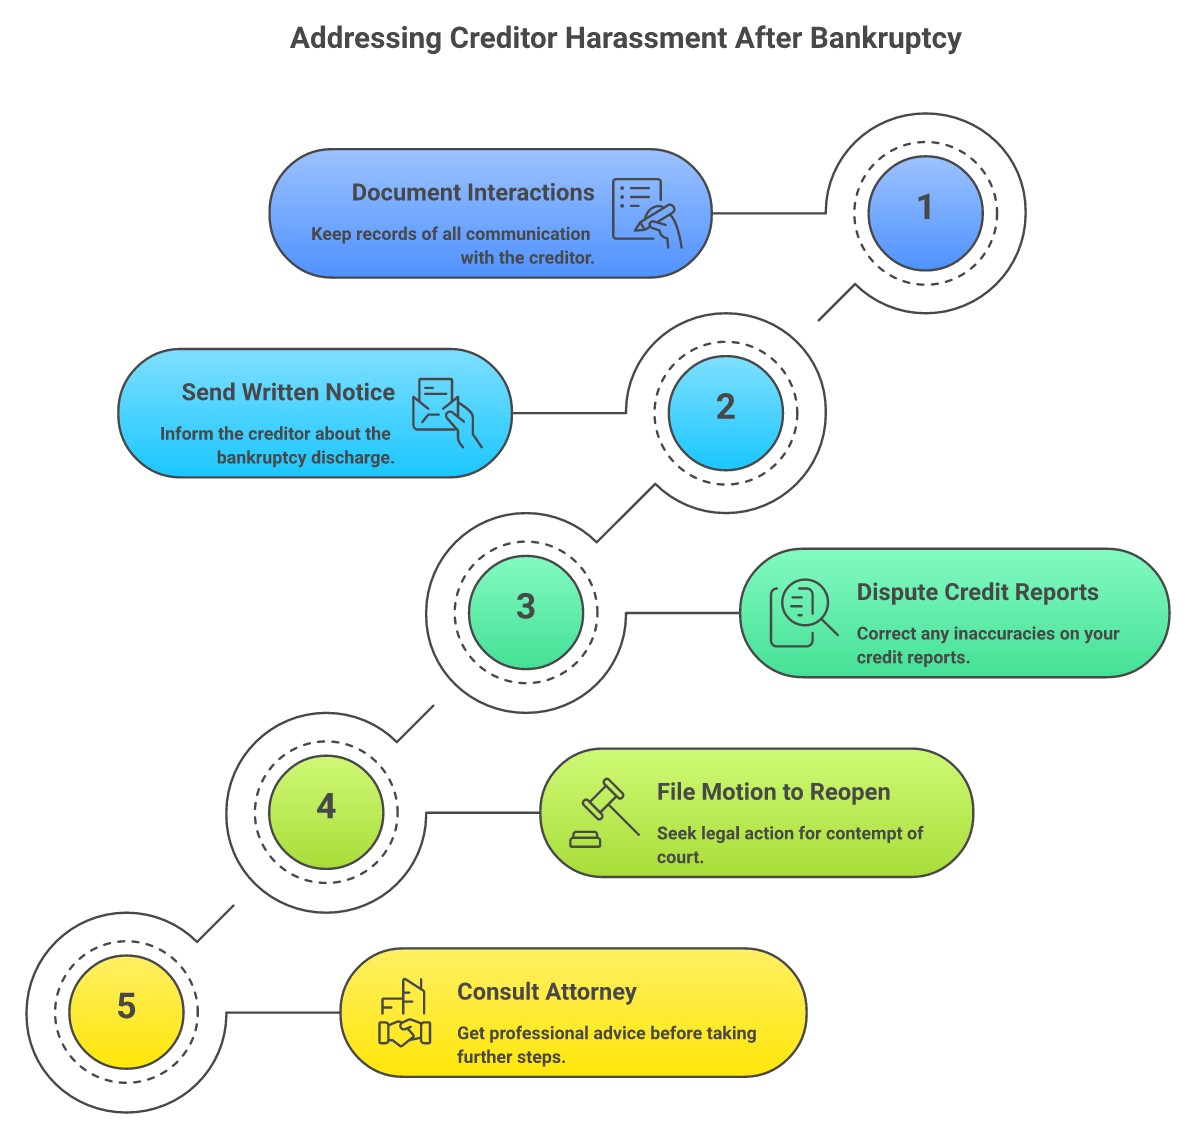
- Stop talking on the phone. Start documenting. Every call, letter, lawsuit filing, or credit-report entry needs a written record: the date, the amount claimed, the account number, and exactly what they did.
- Send written notice within the next few days. Pull your bankruptcy case number and discharge order (your Official Form B18 Notice of Discharge, or ask your local bankruptcy clerk’s office or check PACER if you can’t find it) and send the creditor a short letter citing 11 U.S.C. § 524 and your case number, demanding they stop immediately. Keep a copy of everything you send.
- Pull your credit reports and dispute any balance still shown as owed. A furnisher is required to report accurate, up-to-date information — a discharged debt reported as currently owed and collectible is inaccurate. Dispute it directly with each credit bureau.
- File a Motion to Reopen your original bankruptcy case and ask for contempt. This is not a new bankruptcy filing — you go back into the same case number you already have. No filing fee applies when the motion specifically enforces the §524 discharge injunction — it’s the one type of reopening motion the U.S. Courts’ own fee schedule waives. NACBA can connect you with a bankruptcy attorney who handles these motions, often on contingency once contempt and damages are proven. Not sure if bankruptcy fits your bigger picture? Take the Find Your Path quiz.
- Talk to Damon Day for free. DamonDay.com — get a second opinion on your specific situation before you do anything else.
How to Actually Stop It — Your 4 Paths
- Reopen the case and move for contempt. This is the fastest path with real teeth. Reopening a closed case to enforce the discharge injunction costs nothing — compare that to the normal $245 Chapter 7 or $235 Chapter 13 reopening fee, which the U.S. Courts’ fee schedule specifically waives for this exact motion. The Supreme Court set the enforcement standard in Taggart v. Lorenzen (2019): a court can hold a creditor in civil contempt if there was “no fair ground of doubt” that continuing to collect violated your discharge. Courts have discretion to award actual damages, attorney’s fees, and in some circuits punitive damages once contempt is found.
- Send a written §524 demand letter first. Many larger creditors’ legal departments will stand down the moment they see a case number and statute citation in writing — it’s often faster and cheaper than going straight to court, and it builds the paper trail you’ll need if they don’t.
- File complaints with the CFPB and FTC. The CFPB has specifically flagged post-discharge collection as a supervisory violation, including in Bulletin 2023-01 on unfair billing after student loan discharges. A complaint doesn’t stop the collector by itself, but it creates a regulatory record and often gets a company’s legal department involved fast.
- What WON’T work: Paying to “make it stop” (it doesn’t legally revive the debt and may not end the calls), ignoring it and hoping it goes away (a creditor already willing to ignore a federal court order often escalates to a lawsuit if nobody objects), or disputing only by phone (no record for the judge who decides your contempt motion).
What You Need to Know About Your Legal Protections
Your discharge order and the automatic stay you had earlier in your case are two different legal shields, and mixing them up is the single most common confusion in this situation.
| Protection | Automatic Stay — 11 U.S.C. § 362 | Discharge Injunction — 11 U.S.C. § 524 |
|---|---|---|
| When it starts | The instant you file your case | The instant the court enters your discharge |
| How long it lasts | Until your case closes, is dismissed, or you’re discharged | Permanently, for every debt the court discharged |
| What it stops | All collection activity on all debts while your case is open | Collection only on the specific debts that were discharged |
| How you enforce it | Motion for sanctions in your still-open case | Motion to reopen your closed case, then motion for contempt |
If you live in California, the Rosenthal Fair Debt Collection Practices Act is one of the few state laws that applies FDCPA-style rules to original creditors collecting their own debt, not just outside collection agencies. That matters here because the federal FDCPA usually doesn’t reach an original creditor who never sold your account — the §524 discharge injunction still stops them regardless of what state you’re in, but Rosenthal can give California residents an added state-law claim and fee-shifting on top of a federal contempt motion.
If a creditor or collector is still billing, calling, reporting, or suing you on a discharged debt, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990. When I later ran a 70-employee credit counseling nonprofit, one of the calls I heard most wasn’t from someone drowning in new debt — it was someone who thought they were done. Discharge in hand, fresh start underway, and then the phone rang about a debt that was supposed to be gone. That’s not a sign you did something wrong. It’s a sign somebody’s computer system didn’t get updated, or your account got sold to a buyer who never bothered checking the bankruptcy court’s own record. Debt is math wrapped in emotion, and this particular flavor of it is almost pure emotion — the fear that your fresh start wasn’t real. It was real. The law is entirely on your side. The people I’ve seen do best documented everything and went back to their bankruptcy court. The ones who just kept answering the phone and hoping it would stop didn’t.
Frequently Asked Questions
A collector is still calling me about a debt I know was discharged — can I make them stop?
Yes. Under 11 U.S.C. § 524, your discharge is a permanent federal court injunction against collecting that debt. Document every call, send written notice of your case number citing §524, and if it continues, file a motion in your original bankruptcy case asking the court to hold them in contempt.
I filed bankruptcy — how fast does this protection kick in?
Two different clocks apply. The automatic stay under 11 U.S.C. § 362 takes effect the moment you file your case — not weeks later — and stops all collection while your case is open. The discharge injunction under §524 takes over the moment the court actually enters your discharge, which for most Chapter 7 cases is about four months after filing, per U.S. Courts. From that point forward, the bar on that debt is permanent.
Do I have to hire a lawyer or file a whole new bankruptcy case to get this stopped?
No. You reopen your existing case under the same case number — a new bankruptcy filing isn’t required. You can file the motion yourself, though an attorney experienced in discharge-violation motions (find one through NACBA) often works on contingency once damages are shown, since courts can award attorney’s fees as part of the contempt remedy.
What if the debt was sold to a new collector who says they never knew about my bankruptcy?
“We didn’t know” is a common defense, but it isn’t automatic protection. Under the standard the Supreme Court set in Taggart v. Lorenzen, the question is whether there was an objectively reasonable basis to believe collecting was lawful. A buyer of a discharged debt who never checked the public bankruptcy record before dialing may not clear that bar.
Can I actually get money out of this, or just get them to stop?
Courts have discretion to award more than just an order to stop. Once a §524 contempt violation is proven, remedies can include actual damages, attorney’s fees, and, in some circuits, punitive damages for bad-faith conduct. It varies by court and by the facts of your case, which is why talking to an attorney before you file matters.
I live in California — do I have extra protections?
Yes. California’s Rosenthal Fair Debt Collection Practices Act applies FDCPA-style rules even to original creditors collecting their own accounts, which the federal FDCPA typically doesn’t reach. It can give you an added state-law claim on top of your federal contempt motion.
The discharged debt still shows up on my credit report as “owed” — what do I do?
Dispute it directly with each credit bureau. Furnishers are required to report accurate, updated information, and a discharged debt listed as currently owed and collectible is not accurate. Reference your discharge order and case number in the dispute.
I already made a payment because I panicked — did I just re-agree to owe the debt?
No. Under 11 U.S.C. § 524(c), the only way a discharged debt can become legally enforceable again is through a formal reaffirmation agreement — filed with the court, before your discharge, meeting specific disclosure requirements. A payment you made out of fear isn’t a reaffirmation. The debt is still not owed. Document the payment; it can factor into your damages.
This isn’t the only debt-collector crisis I’ve mapped out in detail. If a collector is calling about a debt that’s just old (not discharged), see A Collector Is Calling About a Debt That’s Years Old. If you’re already judgment-proof and they still won’t stop, see I’m Judgment-Proof but Collectors Won’t Stop. And if bankruptcy erased a personal guarantee but a lender is still coming after collateral, see Bankruptcy Erased My Personal Guarantee. General collector harassment, not tied to bankruptcy at all? Start with Debt Collectors Are Calling Me.
One more thing — everything I share here is based on 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A bankruptcy discharge is a permanent federal court order, and a creditor who keeps collecting after it is violating that order — not just being difficult. Document everything, send written notice, and if it doesn’t stop, reopen your case at no cost and ask the court for contempt. See how bankruptcy compares to your other options with the Get Out of Debt Calculator. Talk to an attorney this week. The longer a violation goes undocumented, the harder it is to prove.
The Bottom Line
You didn’t do anything wrong, and you’re not imagining that this shouldn’t be happening — it shouldn’t. The bankruptcy system built this protection specifically so a fresh start would actually be a fresh start, and the people who documented the violation and went back to court got it stopped, often with money for the trouble. If someone you know got a discharge and is still getting calls or bills on debt that was supposed to be gone, send them this page — most people don’t know reopening a case for exactly this reason costs nothing. See the research on how bankruptcy filers recover and take the Find Your Path quiz if you’re still weighing your options. Restitution is one of the rare debts that survives bankruptcy entirely — if that’s what a collector is chasing you for, see your real rights when restitution goes to a collection agency.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 4): You can stop an IRS interview cold — even after you’ve started answering
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



