

A Get Out of Debt series · Reading the filings so you don’t have to
What They Told Wall Street
FORM 10-QENOVA INTERNATIONAL, INC. (ENVA)FILED 07/23/2026Q2 ENDING 06/30/2026CIK 0001529864
In January 2026, a payday-style online lender agreed to forgive $87 million in old debt and pay $3.4 million more — to settle a state’s case accusing it of charging Virginia borrowers interest rates as high as 155%. The company didn’t put out a press release about it. It told the SEC, in the small print of a quarterly report, because the law requires it to.
I’ve reviewed whether NetCredit is legit and whether CashNetUSA is legit before — both are brands owned by the same company, Enova International. I’ve also watched Minnesota go after a different cash-advance app this year. States are still fighting these fights. The company itself has now confirmed, in legal documents filed with the SEC under penalty of law, how one of those fights ended — a January 2026 settlement it first disclosed to the SEC months earlier and repeated in its latest quarterly report.
Enova International is a Chicago-based online lender that operates under several consumer brand names — CashNetUSA, NetCredit, OnDeck, and Headway Capital — making high-cost installment and short-term loans across the United States. It’s a large, publicly traded company, and on July 23, 2026, it filed its second-quarter report with the SEC. Buried in Note 7, “Commitments and Contingencies,” is the final chapter of an eight-year legal fight in Virginia. It’s the same pattern this series has found reading what SoFi told the SEC about private student loans and what Synchrony told the SEC about your credit card: companies say things to Wall Street they’d never put in a commercial.
Q2 2026
Q2 2026
the Virginia consent decree
Source: Enova International, Inc. Form 10-Q for the quarter ended June 30, 2026, filed with the U.S. Securities and Exchange Commission on July 23, 2026 (Overview and Note 7).
The disclosure — what Enova told the SEC
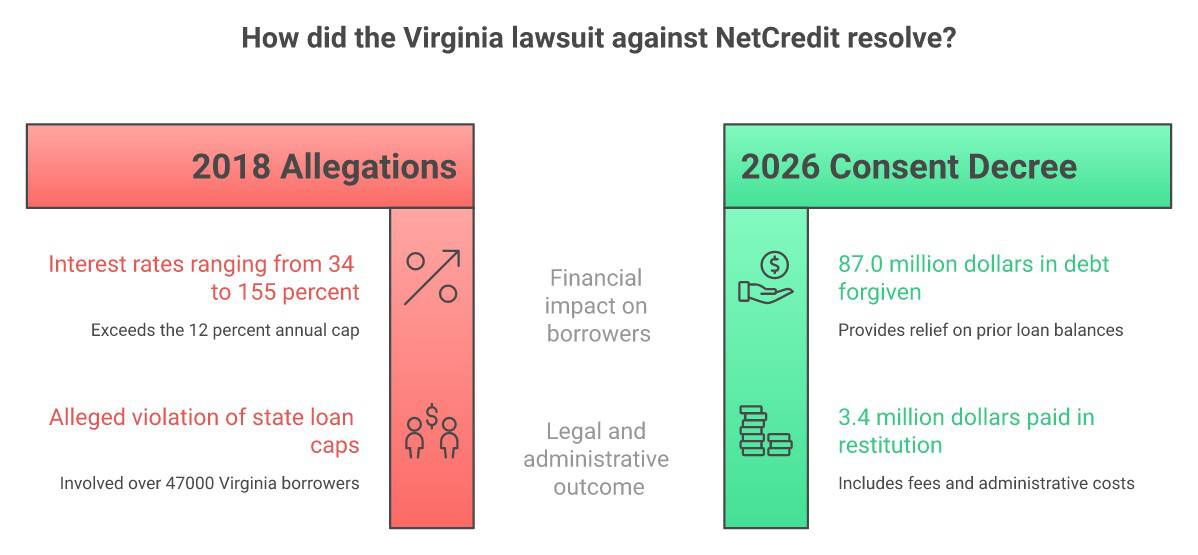
“On April 23, 2018, the Commonwealth of Virginia, through Attorney General Mark R. Herring, filed a lawsuit … against NC Financial Solutions of Utah, LLC (‘NC Utah’), a subsidiary of the Company. The lawsuit alleged violations of the Virginia Consumer Protection Act relating to NC Utah’s communications with customers, collections of certain payments, its loan agreements, and the rates it charged to Virginia borrowers. … In January 2026, the parties entered into a Consent Decree to resolve the matter. Under the Consent Decree, NC Utah denied the allegations contained in the complaint and agreed to a payment of $3.4 million, comprised of $3.1 million in customer restitution, $0.2 million in fees and costs and $0.1 million in administration expenses. Additionally, NC Utah agreed to modify certain outstanding loans at reduced interest rates and forgive approximately $87.0 million of previously charged-off receivables.”
What I think they’re really saying
Read that last part again: $87 million in old, already-charged-off debt forgiven — on top of a $3.4 million payment. Companies don’t give away $87 million because a case is trivial. They also note it had “no material impact” on this quarter’s earnings, because the debt was already written off in prior years as uncollectible — meaning the accounting cost to Enova was mostly already absorbed, even though the value to real borrowers, whose collections and credit reports this touches, is real. NC Utah denied wrongdoing, which is standard in a settlement and is not proof of anything either way. But the size of what changed hands tells you this case wasn’t nothing. That’s my read of why this paragraph exists.
Consent decree
In plain English
A consent decree is a court-approved settlement. The defendant agrees to specific terms — here, a payment and debt forgiveness — without admitting the allegations are true, and the case ends without a trial or a verdict. It’s legally binding once the court signs off, but it is not a finding that the company did anything wrong. Both things can be true at once: NC Utah denies the allegations, and NC Utah is legally required to forgive $87 million and pay $3.4 million. Read the terms, not the denial, if you want to know what actually happened.
What the lawsuit actually alleged
Enova’s filing summarizes the case in a sentence. The original 2018 complaint, described in Virginia Attorney General Mark Herring’s own announcement at the time, was far more specific — and it’s a second primary source, separate from the SEC filing, worth reading in full.
“[Herring’s] Predatory Lending Unit has filed a lawsuit against Net Credit … The lawsuit alleges that … Net Credit issued loans of $1,000 to $10,000 to more than 47,000 Virginia borrowers between 2012 and 2018 with interest rates from 34% to 155%. … Unless a lender qualifies for an exception, Virginia law caps the interest rate on loans at 12% per year. … The Complaint also alleges that Net Credit tried to illegally collect money from borrowers who had filed for bankruptcy and were entitled to protection from collections activities … in the form of automatic withdrawals from consumers’ bank accounts and collections emails while court-ordered bankruptcy stays were in effect.”
What I think they’re really saying
Two separate allegations are packed into that paragraph, and they hit different people. The interest-rate allegation is about the price of the loan — up to 155% against a state cap of 12%, allegedly worked around by claiming a Utah charter. The bankruptcy allegation is about what happened after some of those borrowers tried to get relief — continuing to pull money from their bank accounts and send collection emails while a bankruptcy court’s automatic stay was supposed to have stopped exactly that. If true, that second piece isn’t a pricing dispute. It’s collecting on debt during the one period federal law says a collector legally cannot. NC Utah denies all of it. But this is the allegation that made the case, and it’s why I think this filing belongs on this site and not just in a financial newsletter.
The automatic stay
In plain English
The moment you file for bankruptcy, federal law (11 U.S.C. § 362) creates an “automatic stay” — an immediate, court-ordered freeze on collection activity against you. No more calls, no more letters, no more automatic withdrawals from your bank account, no lawsuits. It happens the instant your case is filed, before a judge even reviews anything. A creditor who knowingly keeps collecting after that isn’t just being rude — it can be held in contempt of court, and courts have ordered creditors to pay borrowers damages for violating it.
If you are ever in an active bankruptcy case and a lender keeps calling, emailing, or pulling money from your account, that is the single fastest thing to tell your bankruptcy attorney about. This is exactly the kind of conduct Virginia’s complaint alleged against NC Utah, and it’s a protection real enough that a state attorney general built part of a lawsuit around it.
One more piece of the record worth knowing: NC Utah didn’t settle quickly. It first tried to force each affected borrower into individual arbitration instead of letting the state pursue the case — the Supreme Court of Virginia rejected that argument in 2021, and the U.S. Supreme Court declined to take up the company’s appeal that December. The case then ran nearly five more years before the January 2026 consent decree Enova just disclosed to the SEC.
What this means for you
If you have ever had a loan from NetCredit, CashNetUSA, or another Enova brand — especially one taken out in Virginia between 2012 and 2018 — the consent decree may already cover you. Restitution and loan modifications under a consent decree are typically distributed by the state or a settlement administrator, not something you have to sue for separately. If you’re not in Virginia, the same math still applies to you: a payday or installment loan cycle is the same trap regardless of which state’s cap the lender is or isn’t respecting.
What I’d do — Pull your original loan agreement and calculate your actual APR; compare it to your state’s rate cap (most states publish this on the attorney general’s consumer protection site). If you were ever in an active bankruptcy case and this lender (or any lender) kept contacting you or withdrawing payments, tell your bankruptcy attorney immediately — that’s a stay violation, not a normal collections dispute. And if you’re currently drowning in a high-rate installment or payday loan and don’t know where to turn, look at all your options before you assume you’re stuck with the rate you were quoted.
Steve’s bottom line
Enova’s own quarterly report to Wall Street confirms a state attorney general spent nearly eight years pursuing one of its lending subsidiaries over rates as high as 155% and alleged bankruptcy-stay violations — and that it ended with $87 million in forgiven debt and a $3.4 million payment, without an admission of guilt.
Nothing here proves the original allegations were true. NC Utah denied them, and a consent decree isn’t a verdict. But $87 million doesn’t move for nothing, and the underlying protections — state rate caps, and the bankruptcy automatic stay above all — are real, enforceable rights whether or not any particular company ever gets sued over them. You don’t need a lawsuit filed in your name to use them.
Frequently asked questions
What did Enova disclose about the Virginia lawsuit?
In its Form 10-Q filed with the SEC on July 23, 2026, Enova International disclosed that its subsidiary NC Financial Solutions of Utah, LLC (which operates the NetCredit brand) entered a consent decree in January 2026 to resolve a 2018 lawsuit brought by the Virginia Attorney General. Under the decree, NC Utah paid $3.4 million and agreed to forgive approximately $87.0 million in previously charged-off receivables, while denying the allegations.
What did the original 2018 lawsuit allege?
According to the Virginia Attorney General’s May 2018 announcement, the lawsuit alleged that NetCredit issued loans of $1,000 to $10,000 to more than 47,000 Virginia borrowers between 2012 and 2018 at interest rates from 34% to 155%, exceeding Virginia’s 12% annual rate cap. It also alleged NetCredit tried to collect from some borrowers who had filed for bankruptcy, in violation of the automatic stay.
Does a consent decree mean the company admitted wrongdoing?
No. In a consent decree, the defendant agrees to specific terms — here, a payment and debt forgiveness — without admitting the underlying allegations. NC Utah explicitly denied the allegations in the Virginia complaint even as it agreed to the settlement terms.
Are NetCredit and CashNetUSA the same company?
They’re both consumer lending brands owned by the same parent company, Enova International, Inc. (NYSE: ENVA). Enova also operates OnDeck (small business loans) and Headway Capital. NC Financial Solutions of Utah, LLC, the subsidiary named in the Virginia lawsuit, operates the NetCredit brand.
What is the bankruptcy “automatic stay,” and why does it matter here?
The automatic stay is a federal legal protection (11 U.S.C. § 362) that immediately stops most creditor collection activity the moment someone files for bankruptcy. The Virginia complaint alleged NetCredit continued automatic bank withdrawals and collection emails against some borrowers during active bankruptcy stays. If a lender does this to you during your own bankruptcy case, it’s a stay violation you should report to your attorney right away — it can result in the creditor being held in contempt of court.
What should I do if I had a high-interest NetCredit or CashNetUSA loan?
Pull your loan documents and calculate the actual APR you were charged, then compare it to your state’s interest rate cap. If you were in Virginia between 2012 and 2018, you may already be covered by the consent decree’s restitution or loan modifications. Regardless of the lender or state, if a high-cost loan has become unmanageable, review all your debt relief options before assuming you’re stuck with the terms you signed.
Read it yourself — the primary sources
Enova International, Inc. — Form 10-Q, quarter ended June 30, 2026 (SEC.gov) →
Filed with the SEC on July 23, 2026. The litigation disclosure is in Note 7, “Commitments and Contingencies.”
Filing index — Form 10-Q, Accession No. 0001193125-26-314590 →
Office of the Virginia Attorney General — press release, May 4, 2018 →
To find any company’s SEC filings yourself: sec.gov/edgar/search → type the company name.
How to read this
Two different things appear above, kept separate on purpose. The quotes in the document blocks are fact — Enova’s own words from its SEC filing, and the Virginia Attorney General’s own words from an official press release, both public record, quoted verbatim and linked above so you can verify them yourself. The plain-English explanations and the amber notes are my interpretation — offered to help you understand what these documents mean, not a statement of fact about Enova’s or NC Utah’s conduct.
NC Utah denied the allegations in the Virginia complaint, and nothing here says Enova or NC Utah did anything wrong. A consent decree resolves a case; it is not a verdict. I’m using this filing and the underlying public complaint to explain rate caps and bankruptcy protections that apply broadly, not to make a claim about this company’s conduct beyond what these documents themselves say. This is general information and my opinion after more than 30 years helping people with debt, not legal advice. If you believe a creditor violated the bankruptcy automatic stay in your own case, talk to a licensed bankruptcy attorney right away.
Know someone who’s ever had a high-rate payday or installment loan? Please forward this to them. Most people never find out a settlement like this exists unless someone tells them where to look.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
“What They Told Wall Street” reads the SEC filings of the companies that handle your money and translates what they admitted — one filing at a time. Sourced entirely from public SEC records. · See the whole series →



