

Written by Steve Rhode, consumer debt expert since 1994 • Last updated July 27, 2026
Quick Answer: A judgment lien means a creditor who won a lawsuit against you recorded that judgment against your house — it does not mean an immediate forced sale. The lien attaches to your equity and generally gets paid when you sell or refinance, not before. Your state’s homestead exemption may protect some or all of your equity, and if it doesn’t, 11 U.S.C. § 522(f) can let bankruptcy strip the lien to the extent it impairs your homestead exemption. Don’t panic-sell or panic-pay before you check both.
What Just Happened to Your House
A creditor sued you, won a money judgment, and instead of (or in addition to) garnishing your wages or levying your bank account, they took the judgment to the county recorder’s office and filed it against real estate you own. Once that’s recorded — usually as an “abstract of judgment” — it creates a lien: a legal claim against your equity in the property. It doesn’t transfer ownership and it doesn’t, by itself, put your house up for sale.
Most judgment liens exist for one purpose: to get paid the next time money changes hands on the property — when you sell it or refinance it. Title companies won’t close a sale or a refinance with an unresolved lien on record, so the lien becomes a debt that has to be cleared at that moment, out of your proceeds or equity, before you ever have to think about a forced sale.
This is different from a creditor freezing your bank account or garnishing your paycheck — those hit your cash flow immediately. A property lien is slower and attaches to an asset instead, which is actually good news: it buys you time to check your options before any money moves. And if you never knew about the lawsuit that led to this judgment in the first place, start with our guide on default judgments — you may be able to get the underlying judgment (and the lien with it) thrown out.
The Mistake You’re About to Make: Either paying the lien in full immediately out of fear, or rushing to sell or refinance before checking whether the lien even reaches your equity. Depending on your state’s homestead exemption, a chunk (or all) of your home equity may already be legally out of this creditor’s reach — and if it isn’t, bankruptcy may be able to strip a lien that impairs that exemption. Paying first and asking questions later can cost you thousands you never had to spend.
Your Options Right Now
What to Do in the Next 48 Hours
- Pull the actual recorded lien. Go to (or search online) your county recorder or clerk’s office where your property sits, and get a copy of the recorded abstract of judgment. Confirm the amount, the date it was recorded, and that it’s actually attached to your specific parcel — liens are sometimes recorded against the wrong person or property.
- Don’t panic-sell or panic-refinance. A recorded lien does not mean the sheriff is coming. In most states the creditor must go to court again — file a separate motion, prove your home has enough non-exempt equity to justify a forced sale, and get a judge’s order — before your house can be sold to satisfy the debt.
- Check your state’s homestead exemption. Every state protects some amount of home equity from a money judgment. It ranges from very little in a handful of states to unlimited in states like Texas and Florida. If your equity is under the exemption, the lien may not be able to touch it at all.
- Consider whether bankruptcy can strip the lien. If the lien impairs a homestead exemption you’re entitled to, 11 U.S.C. § 522(f) lets you ask the bankruptcy court to avoid — legally erase — the lien. Filing bankruptcy also triggers the automatic stay immediately, which stops any pending motion to force a sale the moment you file — not weeks later. See NACBA to find a bankruptcy attorney and the Find Your Path quiz to see how bankruptcy compares to your other options.
- Talk to Damon Day for free. Before you pay a dime, get an honest read on whether this lien is worth negotiating down, challenging, or letting a bankruptcy filing handle. Talk to Damon Day for free about your specific numbers.
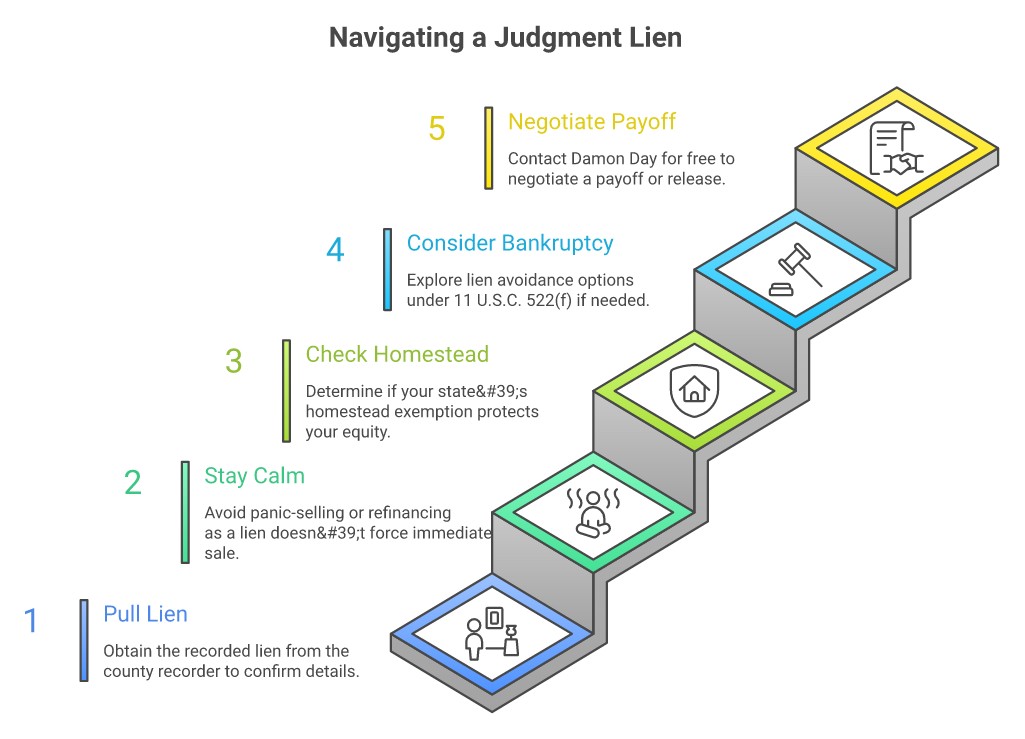
How to Actually Stop It — Your 4 Paths
- Strip it in bankruptcy (usually the fastest real fix). If the lien impairs an exemption you’re entitled to, § 522(f) lets your bankruptcy attorney file a motion to avoid the lien — the lien is avoided to the extent it impairs that exemption. If your equity is fully covered by the exemption, the lien comes off entirely; if you have non-exempt equity, part of the lien can survive against that equity — but even then, your personal liability for the underlying debt is typically wiped out by the bankruptcy discharge, so a surviving lien is only ever paid out of that non-exempt equity when you sell or refinance, never out of your pocket afterward. This lien-avoidance power applies only to judgment liens from a lawsuit, not to tax liens, HOA liens, or mechanic’s liens, which follow different rules. If a private investor bought a tax lien on your home instead of a judgment lien, see what to do when a property tax lien is sold — the deadlines and options are different. Federal Reserve Bank of New York research shows people who file recover financially faster than those who spend years trying to pay creditors down instead.
- Rely on your homestead exemption without filing anything. If your equity is already fully covered by your state’s exemption, the lien may simply have nothing to attach to — but that determination is usually made when you sell, refinance, or file, not automatically. Get it confirmed in writing rather than assuming.
- Negotiate a payoff or release directly. Judgment creditors often accept less than the full amount, especially once they realize a bankruptcy filing could wipe the lien out for nothing, or once you’re mid-sale and they’d rather get partial payment now than wait. Any agreement must be in writing, and the creditor must record a “satisfaction of judgment” or lien release once you pay — don’t hand over money without that promise in the deal.
- What won’t work: ignoring it or “waiting it out” informally. Judgment liens don’t quietly disappear — most states let creditors renew them for another 10 years before they expire, so an ignored lien can outlast a decade of your life. And debt settlement or consolidation loans don’t remove a lien that’s already recorded; only payment, a court order, or a successful legal challenge does.
What You Need to Know About Homestead Protection
Homestead protection is the single biggest factor in how much danger this lien actually poses to you. Federal bankruptcy law protects $31,575 of home equity per person under 11 U.S.C. § 522(d)(1) (as adjusted April 2025) if you use the federal exemptions in a Chapter 7 or Chapter 13 case. One important catch: many states — including California and Florida — have “opted out” of the federal system, so their residents must use the state homestead exemption in bankruptcy, not the federal $31,575. Every state also sets its own exemption for judgments outside bankruptcy — and the range is enormous.
| Jurisdiction | Homestead Protection | Notes |
|---|---|---|
| Federal bankruptcy exemption | $31,575 per person ($63,150 married, filing jointly) | Only available if you file bankruptcy and use the federal exemption system — 11 U.S.C. § 522(d)(1) |
| California | Greater of $371,547 or your county’s median home price, capped at $743,681, adjusted yearly | Applies automatically outside bankruptcy too — CCP § 704.730 |
| Texas | Unlimited value | Up to 10 acres in a city, 100–200 acres rural. A judgment lien generally does not even attach to a Texas homestead (though you may still need to record an affidavit to clear it from the title before you sell) — Tex. Const. art. XVI, § 50 |
| Florida | Unlimited value | Up to ½ acre in a municipality, 160 acres elsewhere; protection is automatic, no filing required — Fla. Const. art. X, § 4 |
If your state’s homestead exemption is small or the lien exceeds it — that’s exactly the situation § 522(f) lien avoidance in bankruptcy was written for. An attorney can calculate, using your specific numbers, whether the lien “impairs” your exemption and by how much.
If a debt collector or collection law firm is threatening to seize your house immediately, contacting you at work, or misrepresenting what a lien actually allows them to do, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov. Georgia’s Attorney General, for example, publishes a consumer guide to liens against your home that walks through your options and defenses — check whether your own state AG’s office has something similar.
Steve’s Take
I filed bankruptcy in 1990, and I remember exactly what it felt like to think the roof over my head was suddenly not safe. It wasn’t — not the way panic made it feel. A lien on your house is math, not an eviction notice: it’s a number waiting to get paid at the next closing table, and how much of that number is actually yours to protect depends entirely on your state’s exemption and whether bankruptcy can wipe it out. I’ve watched thousands of people spend money they didn’t have paying off a lien they could have legally erased, simply because nobody told them to check first. Check first. You are not your debt, and you’re not about to lose your house over a piece of paper at the recorder’s office — not without a lot more happening first.
Frequently Asked Questions
A judgment lien was just filed against my house — can they force me to sell it?
Not immediately, and in most cases not at all without the creditor going back to court, filing a separate motion, and getting a judge to sign off on a forced sale after proving your equity exceeds your homestead exemption. Read the notice you receive carefully — in states like California, you’re entitled to a hearing on your right to a homestead exemption before any sale can happen (see the California courts self-help guide to property liens).
How long does a judgment lien stay on my house?
It varies by state, but 10 years with an option for the creditor to renew it for another 10 is common — confirmed for California liens at CCP § 697.310. If the creditor lets the renewal deadline pass, the lien expires and you can request it be removed from title.
Can I sell my house with a lien on it?
Yes, but the title company will require the lien to be paid off (or otherwise resolved) out of your sale proceeds at closing before the sale can go through. If your equity is fully covered by your homestead exemption, that changes what the creditor is legally entitled to take from that closing — talk to a real estate attorney or your closing agent before you sign anything.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Can I refinance my house with a judgment lien on it?
Usually not without addressing it first. Lenders generally require liens to be paid off, subordinated, or released before they’ll refinance, since a judgment lien can have priority over a new mortgage depending on when it was recorded.
Does my state’s homestead exemption protect me from a judgment lien?
It might protect some or all of it, depending on where you live and how much equity you have. Some states protect only a small amount, while Texas and Florida protect the full value of a primary home with only acreage limits. Look up your specific state’s exemption — this is one of the most consequential numbers in your situation.
I filed bankruptcy — how fast does it stop a judgment lien?
The automatic stay takes effect the moment you file, not weeks later, and it immediately halts any pending motion to force a sale. Actually removing the lien from title (lien avoidance) requires your attorney to file a separate motion under 11 U.S.C. § 522(f), which typically happens within your case, not instantly — but the threat of a forced sale stops right away.
Can I get an improper or expired lien removed?
Yes. If the underlying judgment was entered against you improperly — you were never properly served, for example — you may be able to get the judgment itself vacated, which removes the lien with it (see our guide on default judgments). If the lien has simply expired because the creditor never renewed it, you can typically request the court or recorder issue a release, and if they won’t, an attorney can petition to have it cleared from title.
Free Tool — I'm Being Sued for Debt Guide: Being sued by a creditor or debt collector? The free I'm Being Sued Guide gives you a personalized action plan — deadlines, defenses, and options based on your state. Most states require a response within 20–30 days. Get My Action Plan →
Will a judgment lien show up on my credit report?
The lien filing itself is a public record but civil judgments and liens are not part of the standard credit report data the major bureaus pull anymore. The underlying debt and any related collection account, however, likely already is or will be.
One more thing — everything I share here is based on over 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A judgment lien on your house is serious, but it is not an eviction notice and it does not force an immediate sale. Check your state’s homestead exemption, see how bankruptcy compares with the Find Your Path quiz, and talk to an attorney this week. The longer an unresolved lien sits, the more it can complicate a future sale or refinance you didn’t see coming.
The Bottom Line
Having a lien filed against your house doesn’t mean you failed — it means a creditor used a legal tool that’s more common than most people realize, and most people have never been told how it actually works. The law built homestead exemptions and bankruptcy’s lien-avoidance power specifically so a money judgment can’t automatically cost you your home. The people I’ve watched come out of this best are the ones who checked their exemption and their options before writing a check. If someone you know just found out there’s a lien on their house, send them this page — the panic is almost always worse than the reality, and knowing the difference saves real money.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 10): Your phone company is supposed to know who’s handing it those scam calls. Some of them don’t bother.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



