

Quick Answer: A new life-course brain study links years of lingering financial hardship to measurable cognitive decline and brain atrophy decades later — but the association shows up early, by midlife, which is exactly why financial problems should not be left to sit. Researchers tracked 2,759 people from the same 1946 British birth cohort and found that persistent low income and repeated money hardships between ages 26 and 53 were associated with lower memory and slower thinking speed at 53, and — in a separate, one-time brain scan of participants then in their late sixties and seventies — greater ventricular volume, a brain-atrophy marker, measured at ages 69 to 71 (Liu et al., Innovation in Aging, 2026). This is an observational study, so it shows a link, not proof of cause — but the association is strong enough that unresolved financial hardship deserves attention, not panic.
Part of the Debt & Mental Health Hub: This post is one piece of my complete guide to Debt and Mental Health — the research on debt and depression, the psychology of debt shame, free screening tools, and what actually helps when debt is affecting more than your finances.
Expert Context: I’ve been helping people with debt since 1994, and I filed my own bankruptcy in 1990 after my real estate business collapsed — so I know what the emotional reality of money trouble feels like, not just the math. I’ve watched people freeze for years, too scared or ashamed to act, while the problem quietly compounded. This study puts a number on something I’ve seen up close: waiting may carry a hidden cognitive toll, on top of the financial one.
For more than thirty years I’ve said that debt is math wrapped in emotion — and that the emotion is usually the thing that keeps people stuck. Now a group of researchers in the United Kingdom has followed thousands of people across almost their entire adult lives, and their findings give me a harder, more urgent way to say what I’ve always believed: the longer you let financial adversity linger, the more it appears to take from you — and not just from your wallet.
A quick note on what was actually measured: this study tracked household income and self-reported financial hardship — closely related to debt, but not the same thing. The point isn’t that delaying a decision damages your brain by itself; it’s that letting the underlying financial strain continue, year after year, is what the researchers found linked to worse outcomes.
The study, “Persistent Financial Adversity and Cognitive Aging: A Life Course Investigation,” was published on July 23, 2026 in the journal Innovation in Aging. It’s open access, so you can read the whole thing yourself. The team drew on the MRC National Survey of Health and Development — the famous 1946 British birth cohort, one of the longest-running studies of human aging in the world — plus a neuroimaging sub-study called Insight 46 that actually scanned participants’ brains in their late sixties and early seventies.
All figures above are from Liu et al., Innovation in Aging, 2026. The effect sizes (β) are standardized associations, not proof of cause.
Key Terms Defined
Processing speed: How quickly your brain takes in information and reacts to it. In this study it was measured at age 53 and was lower with more low-income exposure (β = −0.07) or repeated financial hardships (β = −0.05).
Verbal memory: Your ability to learn and recall words and information — the kind of memory that fades early in Alzheimer’s disease. It showed the largest hit in this study: β = −0.16 for more low-income exposure and −0.10 for financial hardships at age 53.
Ventricular volume / brain atrophy: The ventricles are fluid-filled spaces inside the brain. As brain tissue shrinks with age or disease, those spaces get bigger — so a larger ventricular volume is a recognized marker of brain atrophy. In a smaller neuroimaging subsample (Insight 46), persistent low income was linked to a 4.67 ml larger ventricular volume, measured once at ages 69–71 in participants who had lived through the earlier hardship years — a between-group snapshot, not a scan of the same brain repeated over time.
APOE-ε4: A common gene variant that is the strongest genetic risk factor for late-onset Alzheimer’s disease. In this study, people who carried it showed a stronger link between financial adversity and brain atrophy — the money strain and the genetic risk appeared to compound each other.
Cumulative disadvantage: The idea that hardship that persists over years does more damage than a brief, one-time setback. This study found exactly that — sustained adversity mattered more than intermittent episodes.
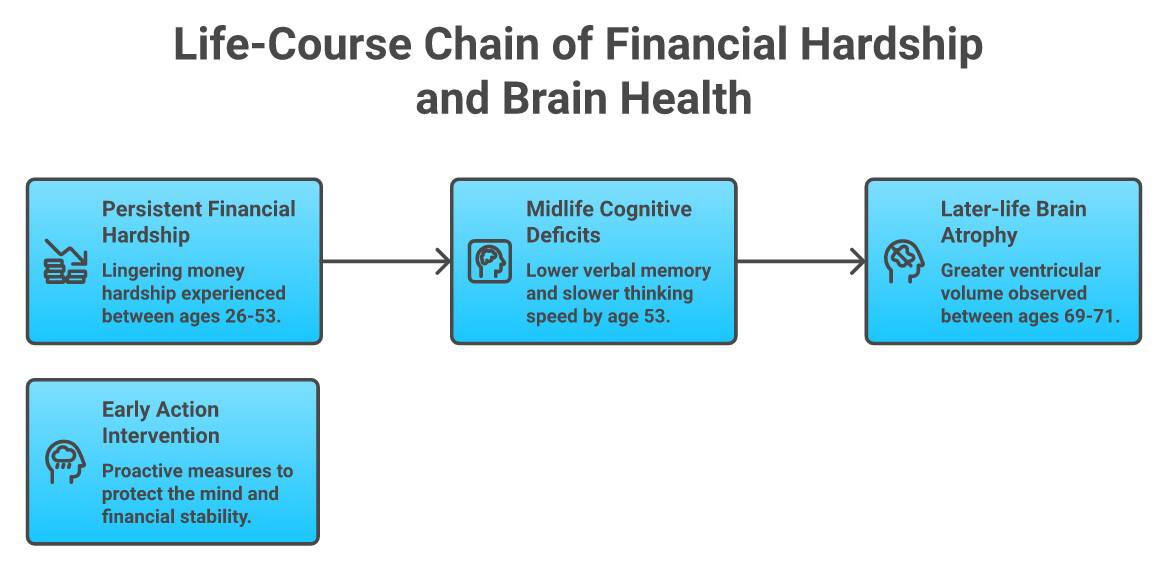
What the researchers actually found about money and the aging brain
Here’s the part that grabbed me. The researchers didn’t just ask people whether they were broke once. They measured two different things over decades: an objective measure (low household income) and a subjective one (whether people reported financial hardships — the felt experience of struggling to make ends meet). And they looked at how those exposures between ages 26 and 53 tracked with brain and thinking measures years and even decades later.
Three findings stand out:
- Lower thinking speed and memory by midlife. By age 53, people who had faced persistent low income or repeated hardships had measurably lower processing speed and verbal memory. Verbal memory took the biggest hit.
- Greater ventricular volume in a smaller neuroimaging subsample. In the Insight 46 neuroimaging subsample (roughly 356–468 of the full cohort), persistent low income was associated with greater ventricular volume — a brain-atrophy marker — measured once at ages 69–71 in participants who had lived through the earlier hardship years. That’s a single-timepoint, between-group snapshot: one brain scan per person, comparing groups at that age — not repeated scans following the same brains shrinking over time.
- Persistence showed the strongest association in the cognitive measures at age 53. Sustained hardship mattered more than occasional rough patches on processing speed and verbal memory. This is cumulative disadvantage in action — but that dose-response pattern lives in the cognitive data, not in the single-timepoint brain scan above.
The links were stronger for men, for people who grew up in tougher childhood circumstances, and for APOE-ε4 carriers — the folks already carrying the greatest genetic risk for dementia. In other words, financial strain didn’t hit everyone equally; it hit hardest where other vulnerabilities were already stacked up. Worth flagging: these stronger-for-some patterns come from exploratory subgroup analyses, which test many comparisons at once — so they’re suggestive leads that need replication, not settled conclusions about any one group.
One more caveat on scope: this comes from a single British cohort born in 1946 — a specific era, with limited ethnic diversity — and the brain-scan subsample (Insight 46) skewed healthier and more socioeconomically advantaged than the full cohort. That means these findings may not fully generalize to younger generations, more diverse populations, or people in the U.S. today. In my experience reading research like this, that kind of healthy-volunteer skew usually pulls effect sizes toward zero rather than away from it — though I can’t confirm that’s what happened here.
The Daily Money Brief — Free, at 10 AM
Money you may be owed, scams to dodge, and the fine print decoded — the consumer money news that affects your wallet, every weekday.
“Persistent financial adversity impacts cognitive performance by midlife and later-life brain atrophy, with larger effects for men, those from disadvantaged childhoods, and individuals with greater genetic risk. Supporting financially vulnerable working-age adults could help prevent dementia in an aging population.”
— Liu, Wels, James, Keuss, Maddock, Parker, Stafford, Schott, Richards & Patalay, Persistent Financial Adversity and Cognitive Aging (2026)
Read that last sentence again, because it’s the authors’ own conclusion, not mine: supporting financially vulnerable working-age adults could help prevent dementia. The intervention point isn’t in old age, once brain-atrophy markers already show up on a scan. It’s now — in the years when the hardship is still happening and still fixable.
The honest caveat: this is a link, not a lightning bolt
I promised you all the information, so here is the part a lot of headlines will skip. This is an observational cohort study. It shows that financial adversity and later cognitive decline travel together; it does not prove that one causes the other. Poorer health, less access to care, more stress, worse sleep, and a dozen other things travel alongside low income too. The researchers controlled for a lot, but no single study like this can hand you a clean cause-and-effect arrow.
One more thing I want to be direct about: this is a population-level pattern, not a diagnostic tool. It can’t tell you whether your own forgetfulness is from money stress, normal aging, poor sleep, a medication side effect, or something else entirely — please don’t use it to self-diagnose. If memory or thinking changes are worrying you, that deserves a conversation with a doctor, not a debt post.
And if the weight of all this has ever pushed you toward thoughts of harming yourself, please reach out right now — call or text 988, the Suicide & Crisis Lifeline, any time of day or night. You are not a burden, and you are not alone.
There’s one more finding I refuse to spin, because a fact-checker should never catch me cherry-picking. The adversity group actually showed slower verbal-memory decline over the follow-up years. That sounds like good news until you understand why: they started from a lower baseline. They were already worse off by midlife, so they had less left to lose. It’s a floor effect, not protection. The cognitive differences linked to adversity were already measurable by middle age, instead of showing up as a steep drop later. If anything, that makes the case for acting sooner stronger, not weaker.
The Claim: “I’ll deal with the debt once I’m less stressed — when things calm down and I can think straight.”
The Reality: Letting the underlying hardship continue is what this study links to worse cognitive outcomes. The strain of unresolved, persistent financial hardship is itself linked to the cognitive fog and decline you’re hoping will lift on its own. “When things calm down” almost never arrives by accident — and every year the problem lingers is another year of cumulative disadvantage. The calm comes after you take action, not before.
Why this changes how I talk about waiting
I have watched the freeze up close for more than thirty years. Someone opens the mail, sees the balance, feels the shame rise, and closes the drawer. Next month, same drawer. The debt is math, but the paralysis is emotion — fear and shame doing exactly what they do, which is convince you that not-looking is safer than looking.
This isn’t new to researchers either. The link between money trouble and mental suffering is well documented.
Debt has long been tied to depression and psychological distress — with research pointing to genuine causal links, worsened by the social stigma of owing money.
— drawing on John Gathergood, Debt and Depression: Causal Links and Social Norm Effects, The Economic Journal (2012)
What the Liu study adds is a longer lens. It suggests that the toll of financial adversity doesn’t stop at anxiety and low mood in the moment — that, for at least some people, it may still be detectable in the physical brain decades later. That’s a sobering thought. But I don’t share it to scare you into the corner. I share it to pull you out of one. Because the flip side of “waiting has a cost” is the most hopeful sentence in this whole story: acting early may help protect your mind, not just your money.
You are not your debt. A number on a statement is not a verdict on your worth, your character, or your intelligence. It’s a problem — and problems have solutions. The tragedy this study points to isn’t debt itself; it’s debt left untouched, year after year, because fear told you to wait.
Key Takeaways
- A 2026 life-course study of 2,759 adults found persistent financial hardship between ages 26 and 53 linked to lower memory and thinking speed by midlife; in a smaller neuroimaging subsample (Insight 46), it was also linked to greater brain atrophy in later life.
- It’s an association, not proof of cause — but the authors themselves conclude that supporting financially struggling working-age adults could help prevent dementia.
- Persistence is what mattered most. Sustained hardship was associated with larger cognitive differences than brief setbacks — the essence of cumulative disadvantage.
- The “slower decline” in the adversity group is a floor effect from a worse starting point, not protection. The association appears by midlife.
- The intervention window is working age — now — not old age. Acting on a money problem early may help protect your cognition, not just your finances.
The Bottom Line
If you’re reading this with a stack of unopened envelopes in the next room, I want you to hear me clearly: the exhaustion and the fog you feel are not proof that you’re failing — they’re the predictable weight of carrying a problem alone for too long, and this research suggests that weight is real enough to show up in a brain scan. But a link is not a life sentence. The same study that measures the cost of waiting also points to where to act, and it’s beautifully simple: act while the problem is still in front of you. I filed bankruptcy in 1990 and rebuilt everything that mattered — my finances, my work, my peace of mind — and I’ve watched thousands of people do the same once they stopped protecting the past and started protecting themselves. Deal with it and look to the future rather than spend five years repairing a past that’s already done. Protect the person first, and the numbers will follow. In my experience, the most important step you can take for your financial and mental well-being is to stop waiting — take the Find Your Path quiz and let it show you, based on your actual numbers, the calmest way out.
Free Tool — Cost of Inaction Calculator: Thinking about waiting to deal with your debt? The free Cost of Inaction Calculator shows exactly how much more you'll owe — in interest and lost retirement savings — for every month you delay. Calculate the Cost →
Frequently Asked Questions
Can financial stress cause memory loss?
Not in the direct, proven sense — this 2026 study is observational, so it shows financial stress and later cognitive decline are linked, not that one causes the other. But the association is real and measurable: people with persistent low income or repeated financial hardships between ages 26 and 53 had lower verbal memory and processing speed by age 53 (full cohort, N=2,759), and — in a smaller neuroimaging subsample (Insight 46) — greater brain atrophy by their late sixties. The safest reading is that lingering financial strain is a risk factor worth taking seriously, not a guaranteed cause you’re powerless against.
Does debt affect brain health?
This study looked at income and financial hardship rather than debt specifically, and in a smaller neuroimaging subsample (Insight 46) it found persistent hardship was associated with greater brain atrophy in later life. Separately, decades of research link problem debt to anxiety, depression, and psychological distress. So while no single study proves debt shrinks your brain, the overall picture is that sustained financial trouble is bad for both your mental and — potentially — your physical brain health. That’s a strong argument for resolving it rather than living with it indefinitely.
Is it too late if I’ve already struggled financially for years?
No. The whole thrust of this research is that persistence is the problem — so stopping the persistence is the goal, and it’s never too late to start. The authors specifically point to supporting working-age adults as a way to help prevent later decline. Ending years of strain now removes the very thing the study links to harm. I’ve seen people turn a corner in their fifties and sixties and rebuild real stability and calm. Your past struggle is a reason to act today, not a reason to give up.
What is APOE-ε4 and why did it matter in this study?
APOE-ε4 is a common gene variant and the strongest genetic risk factor for late-onset Alzheimer’s disease. In this study, carriers showed a stronger link between financial adversity and brain atrophy — meaning money strain and genetic risk appeared to compound. Worth noting: that finding comes from an exploratory subgroup comparison, so it’s a suggestive signal that needs replication, not a settled conclusion about carriers specifically. Still, if you know Alzheimer’s runs in your family, that’s not a reason to panic; it’s one more reason to remove the stressors you can control, and unresolved financial hardship is one of them.
What should I actually do if money worry is wearing me down?
Start by naming the problem instead of avoiding it, because avoidance is the exact pattern this research suggests is costly. Get the real numbers on paper, understand every option available to you — including the ones nobody’s profiting from telling you about — and pick a path. The Find Your Path quiz gives you a recommendation based on your actual situation, and the all your debt relief options page lays out how each choice compares. The single most important step is the first one: acting instead of waiting.
A note from me, not an instruction: Everything here is meant as input to help you think, not a directive about what you must do. Your situation is yours, and you’re the one who gets to decide. If this helped even a little, please share it with someone you love who’s been carrying a money worry in silence — it might be the nudge that gets them to open the drawer. And if you want to talk it through, my door is always open.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research — including the CFPB’s own 2019 report on bankruptcy and financial health — show that consumers’ credit scores tend to recover in the years after a bankruptcy filing.



