

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 29, 2026 • Every material factual claim below links to a primary source.
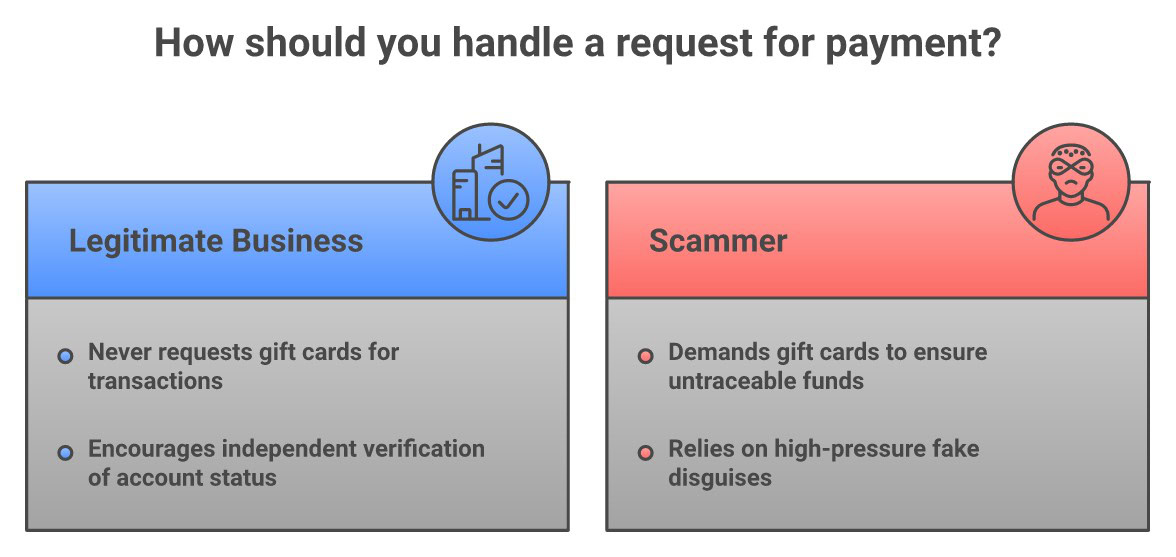
The verdict: Myth. No legitimate business, government agency, debt collector, or court will ever tell you to buy a gift card and read off the numbers to pay a debt, fine, or bill — not the IRS, not Social Security, not your utility company, not the collector calling about your account. The FTC says it flatly: “No real business or government agency will ever tell you to buy a gift card to pay them.” The one legitimate exception runs the other direction — you voluntarily applying a store’s own gift card to that store’s own balance, in person, on your own initiative. A caller telling you to go buy one and read them the numbers is never that. If you hear it, hang up — once you read the numbers off the back of that card to anyone, the money is gone for good.
4 signs it’s a gift-card scam — if any one is true, stop:
- Someone contacted you first — by phone, text, email, or social media — demanding payment.
- They say something terrible will happen (arrest, shutoff, lawsuit, deportation) if you don’t pay right now.
- They tell you exactly which gift card to buy and which store to buy it at.
- They ask you to read the card number and PIN off the back over the phone, or send a photo of it.
Any one of those means it’s a scam. You don’t need to read another word before hanging up — but here’s exactly why.
I have to tell you about this. I went looking at how the FTC itself documents this scam, because I wanted the exact language they use to warn people — and their Avoiding and Reporting Gift Card Scams guide lays it out in one line that should end the argument every time someone hears this pitch:
“Only scammers will tell you to buy a gift card, like a Google Play or Apple Card, and give them the numbers off the back of the card. No matter what they say, that’s a scam. No real business or government agency will ever tell you to buy a gift card to pay them.” — Federal Trade Commission
I couldn’t let that sit without walking through why gift cards specifically are the scammer’s payment method of choice, and why the request itself — regardless of who’s supposedly asking — is the tell that ends the whole conversation.
Well, Actually…
Here’s the mechanical reason gift cards took over as the scammer’s payment method of choice: a gift card is functionally the same as cash, except it’s untraceable the moment you read off the numbers. There’s no bank to call and no chargeback to file — once you’ve read the numbers off the card, there’s no way to reverse it. The instant the scammer has the card number and PIN, they can redeem or resell that value from anywhere in the world, and it’s gone. The FTC’s own reporting shows this isn’t a fringe tactic — the FTC’s data analysis confirms gift cards “continue to be the most common form of payment when consumers report losing money to most scammers,” precisely because of that one-way-door quality.
That’s also why the who’s asking part of the pitch is almost irrelevant. Scammers rotate the costume — the IRS, the Social Security Administration, your power company, a debt collector, tech support, a “relative” in trouble — but the payment instruction never changes, because the mechanics of the fraud never change. The FTC lists the common scripts by name: fake government agents demanding a fine, fake tech support demanding a repair fee, a fake utility company threatening a shutoff, a fake prize demanding you “pay fees or other charges” first, even a supposed friend or family member with a sudden “emergency.” Different story, same demand. That repetition is the pattern to memorize — not the specific disguise.
This is the IRS (or Social Security Administration) calling. You owe back taxes or a fine, and you must pay immediately with gift cards or you’ll be arrested.
The IRS states it plainly: it “never asks for or accepts gift cards as payment for a tax bill.” And it spells out the scam itself — fraudsters “pressure the taxpayer to buy gift cards, then ask the taxpayer to provide the gift card number and PIN.” The IRS generally mails a bill first, by U.S. mail, before ever discussing payment. The FTC’s own scam catalog names this exact script — a caller claiming to be the IRS, SSA, or even the FTC, demanding an immediate gift-card payment — as one of the most common gift card scams reported.
IRS Tax Tip 2021-178: “Gift cards are never used to make tax payments” • IRS: “How taxpayers can protect themselves from gift card scams” • FTC: Avoiding and Reporting Gift Card Scams
A debt collector called about my account and said I could settle it today — but only if I bought gift cards right now and read the codes over the phone.
A real debt — owed to a real creditor or a legitimate collection agency — is never settled by buying a gift card and reading a caller the numbers. Legitimate collectors take a check, a money order, ACH, or a card payment they can document and apply to your account balance, because they need a verifiable payment trail for their own records and for any dispute you might raise later. A gift card leaves no such trail on either end, which is precisely why no real collector uses it and why the FTC’s guidance draws no exception for “a company you owe money to” — the rule is universal: no legitimate business or agency will ever tell you to buy a gift card and read off the numbers to pay what you owe.
My utility company said my power will be shut off within the hour unless I load a gift card immediately.
The FTC names this exact scam directly: “Scammers say they’re from your utility company. They threaten to cut off your service if you don’t pay immediately. But utility companies don’t work that way.” Real utilities send written shutoff notices with an account-specific balance and a real appeals process well before any disconnection, and they accept normal account payments — not gift cards purchased under a same-hour threat.
Why You Were Told This
This works because it’s engineered to short-circuit the moment where you’d normally stop and think. The FTC’s breakdown of how these calls run is almost identical every time: the caller creates urgency (“pay right now or something terrible happens”), isolates you (“don’t tell anyone, don’t hang up, stay on the phone while you drive to the store”), and then narrows your options to one specific, untraceable payment method. None of that is an accident. Wire transfers are typically irreversible — once sent, the money is generally gone, unlike a credit card charge, which can be disputed. A gift card, once the numbers are read aloud, cannot be clawed back by anyone — not your bank, not the store, not the gift card issuer in most cases. That’s the entire reason scammers converged on gift cards and wire transfers as their preferred tools: they’re the payment methods with the least built-in consumer protection of any common ones in circulation.
The other reason this myth persists is that gift cards are, in every other context, a completely normal and harmless thing — which is exactly what makes the ask feel less alarming than “wire me money” or “send me cash.” Scammers lean on that familiarity on purpose. If someone reframes a request for a Google Play, Apple, Target, or Amazon gift card as a way to “settle up” a debt, a fine, or a bill, the unusual part of the request — that a business or government agency is accepting payment this way at all — gets lost behind a payment method you already understand.
What to Actually Do
- Stop the moment anyone tells you to buy a gift card and read them the numbers to pay a debt, fine, or bill. That instruction alone is the entire scam — no other verification is needed. Hang up, close the message, or walk away from the register.
- Never read a gift card number or PIN — by phone, text, or photo — to anyone who contacted you demanding payment for a debt, fine, or bill. Once someone has both numbers, the balance can be drained from anywhere, instantly, with no way for you or the store to reverse it.
- Verify the debt independently before paying anyone anything. Hang up and call the agency, utility, or creditor back using a number you look up yourself — on your bill, on the official government website, or on the back of your own account card — never a number the caller gave you.
- If a caller claims to be a debt collector, ask for written validation first. Real collectors are required to identify the creditor and the amount owed and, on request, verify the debt in writing. My free Debt Validation Letter Generator can help you demand that proof before you send anyone a dime.
- If you already read someone the numbers, act immediately. Call the issuer’s fraud line right now — some companies can still freeze an unspent balance if you report fast enough:
- Amazon: 1 (888) 280-4331
- Apple, iTunes, App Store: 1 (800) 275-2273 — say “gift card”
- Google Play: no phone line — report it here
- Target: 1 (800) 544-2943
- Visa gift card: 1 (800) 847-2911
- Vanilla (the most common Visa/Mastercard prepaid card): 1 (833) 322-6760
These numbers come straight from the FTC’s own issuer contact list, which covers more brands than I can fit here. After that, report it at ReportFraud.ftc.gov. If it was framed as a tax payment, also report it to the Treasury Inspector General for Tax Administration.
- Run any caller claiming to be a debt relief company or collector through a complaint check first. My Scam-O-Meter checks a company’s complaint history before you ever consider paying them anything.
Steve’s Take
In over 30 years of doing this work, I’ve watched the costume change constantly and the ask never change at all. It used to be wire transfers and Western Union. Then it was prepaid debit cards. Now it’s gift cards, and I suspect crypto QR codes will be the next iteration of the exact same idea — find a payment rail with no dispute process and no way to trace it, then invent whatever story gets someone scared enough to use it fast. What gets me every time is how often the victims are people who did everything else right — they answered a call about a real debt they genuinely owed, or a bill that sounded plausible, and the panic did the rest. If you’ve ever bought a gift card because someone on the phone told you to, that’s not a lapse in judgment on your part. That’s a manufactured crisis, built by someone whose entire job is making you feel like you don’t have time to check. You always have time to check. Real debts don’t evaporate in the next ten minutes.
Free Tool — Debt Validation Letter Generator: Being contacted by a debt collector? The free Debt Validation Letter Generator creates a personalized FDCPA validation letter in seconds — forcing the collector to prove the debt is real before they can continue. Generate My Letter →
Frequently Asked Questions
Is it ever legitimate for a debt collector to ask for gift card payment?
No. Legitimate collectors and creditors accept traceable, documentable payments — checks, ACH, money orders, or card payments — because they need a verifiable record for your account. A gift card demand from anyone claiming to collect a debt is always a scam, regardless of how much account detail they seem to know.
Why do scammers specifically ask for gift cards instead of cash or a bank transfer?
Because gift cards are among the least reversible common payment methods available. Once the numbers on the back of the card are shared, the value can typically be redeemed or resold instantly from anywhere, with no bank, card network, or store able to claw it back — unlike a credit-card charge, which can be disputed. A wire transfer is also generally irreversible once sent, which is exactly why scammers favor both gift cards and wire transfers over payment methods with real dispute protections.
What if the caller already knew my name, address, or account number — doesn’t that make it real?
No. Scammers routinely buy or scrape personal information, or reference details from a real bill or public record, specifically to sound credible. Accurate personal details do not change the rule: a gift-card payment demand is a scam regardless of how much the caller already seems to know about you.
I already read someone the gift card numbers. Can I get my money back?
Sometimes, if you act fast. Contact the gift card issuer’s fraud department immediately and ask them to freeze any unspent balance — some companies can do this within a short window. Then report the scam at ReportFraud.ftc.gov. The longer you wait, the less likely any of the balance is recoverable.
Does the IRS ever accept gift cards under any circumstance?
No, never. The IRS states plainly that it “won’t ask for or accept gift cards as payment for a tax bill” under any circumstance, and it will first mail a written bill before ever discussing payment with a taxpayer who owes.
What about being asked to pay with cryptocurrency or a wire transfer instead — is that different?
It depends on the situation, not the payment method by itself. Wire transfers and cryptocurrency are routine, legitimate ways to pay for real things — a mortgage payoff, a home closing, a legal settlement, a court fee. The scam isn’t the payment method; it’s someone who contacted you out of nowhere, demanding you send it immediately, under threat, to resolve a debt, fine, or prize. For anyone claiming to be with the government, the FTC is flat about it: “Don’t wire money or use gift cards, cryptocurrency, or a payment app to pay someone who says they’re with the government” — no exceptions. For a business, the same red flag applies whenever the request is unsolicited and urgent; the safe move is to hang up and call the company back using a number you look up yourself, never one the caller gave you. A real wire transfer for a real transaction comes with paperwork you requested in advance, through a channel you already verified — not a surprise phone demand to read off numbers or send funds in the next ten minutes.
Is this the same scam as the fake IRS jail-threat or Social Security suspension calls?
Yes — it’s the same government-impersonation playbook, just described by the payment method instead of the threat. I’ve also written about the fake IRS jail-threat version and the fake Social Security suspension version of this same con, both of which frequently end in exactly this gift-card demand.
This is one informed perspective based on my own experience and the primary sources linked above. Your situation may have details I can’t see from here — take this as input, not instruction, and verify anything urgent by calling an agency or company back using a number you look up yourself, never one you were given.
The bottom line: If anyone — government agency, debt collector, utility company, or business — tells you to buy a gift card and read off the numbers, it’s not a modern convenience, it’s the one payment demand almost every impersonation scam shares. If someone you know is on the phone with one of these callers right now, send them this before they walk into a store.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.



