

Written by Steve Rhode, consumer debt expert since 1994 • Last updated July 29, 2026
Quick Answer: If this was a ground ambulance — the kind that drives, not flies — I have to give you the hard truth first: the federal No Surprises Act does not cover ground ambulance rides. It protects you from a surprise bill from an out-of-network ER doctor and even from an out-of-network air ambulance, but Congress carved ground ambulances out of the law entirely. That means the bill may be legal. But you still have real options: check whether your state has its own ground-ambulance protection (a live Commonwealth Fund tracker puts the count at 22 states as of February 2026 — check it for your own state), find out first whether you’re a Medicare, Medicaid, or municipal-EMS patient — that alone can change what you actually owe, audit the bill for errors, negotiate hard, and know that bankruptcy discharges this debt completely if it comes to that. Don’t ignore it — but don’t assume it’s illegal, either.
What Just Happened
You called 911, or someone called for you, and a ground ambulance showed up. Weeks later, a bill arrives for hundreds or thousands of dollars — sometimes far more than your insurance paid, or anything close to it. Here’s the part almost nobody expects: unlike the emergency room doctor who treated you, and unlike an air ambulance if one had been used, the ground ambulance company is very likely allowed to bill you for the difference. That gap between what your insurer paid and what the ambulance company charged is called balance billing, and for ground ambulances, it is still legal under federal law in most situations.
This happens because as many as 8 in 10 emergency ground ambulance rides are out-of-network with the patient’s insurance — 79%, per a Health Affairs claims-data study — not because you did anything wrong, but because 911 dispatches whichever ambulance service covers your location, and you have zero say in who responds or what network they’re in.
The Mistake You’re About to Make: If you’ve read anything about surprise medical billing, you may assume the No Surprises Act protects you here the way it protects people from surprise ER or air ambulance bills. It doesn’t — ground ambulance was left out of that law on purpose, pending further study. Assuming this bill is automatically illegal and refusing to engage with it can let it go to collections or hit your credit report while you wait for a protection that, federally, does not exist yet. The right move is to find out whether YOUR state has closed this gap, and if not, to negotiate and dispute errors instead of just hoping the law will bail you out.
Before You Negotiate — Check This First
Before you assume you owe the full balance, rule out the possibility that this bill shouldn’t exist at all: Medicare Part B covers emergency ground ambulance transport (you’d owe your normal 20% coinsurance after the Part B deductible, not a balance bill — see Medicare.gov); Medicaid treats emergency ambulance transport as a mandatory benefit, and Medicaid eligibility can currently be applied retroactively for up to three months before you applied — but for applications filed on or after January 1, 2027, that window shrinks to just one month for people eligible through the ACA Medicaid expansion group and two months for everyone else, under Section 71112 of the 2025 federal budget law (the “One Big Beautiful Bill Act,” Pub. L. No. 119-21; see KFF’s summary of the law’s health provisions) — so if you might qualify for Medicaid, apply now, even after the fact, while the longer window still applies (see Medicaid.gov); and if this was a city or county (municipal) EMS agency, many states require municipal ambulance services to write off or discount bills for low-income patients under state indigent-care or charity-care rules — ask the billing office directly for that policy before you negotiate anything. None of this is guaranteed in your state, but it’s worth 15 minutes to check before you assume you owe every dollar.
Your Options Right Now
What to Do in the Next 48 Hours
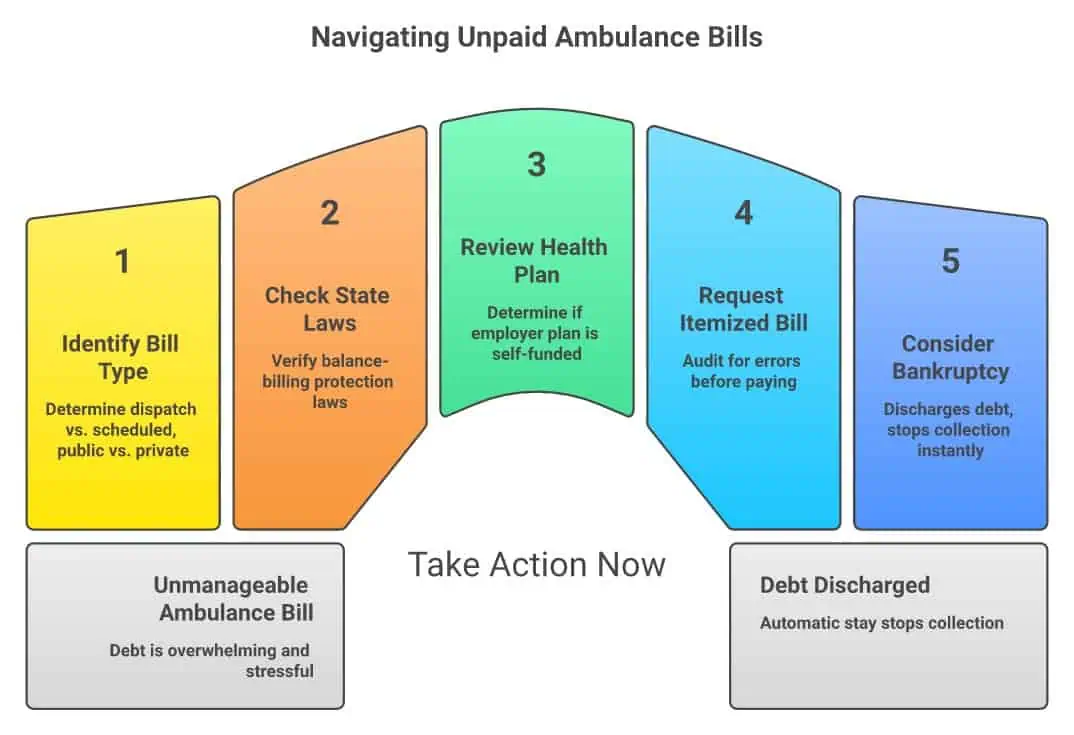
- Figure out who actually billed you and whether it was a 911 emergency transport. Was the ambulance dispatched through 911, or was this a scheduled, non-emergency transport (like a hospital-to-hospital transfer)? Was the provider a municipal/fire-department ambulance or a private company? This changes both your legal protections and your negotiating leverage — a city-run ambulance service is often far more willing to negotiate or offer a hardship discount than a private national provider.
- Check your state’s ground-ambulance balance-billing law before you pay anything. A Commonwealth Fund count published February 2026 puts the total at 22 states with some ground-ambulance balance-billing protection, with North Dakota, Utah, New Hampshire, and Oregon enacting brand-new protections in 2025 (New Hampshire’s and Oregon’s laws take effect January 1, 2026; Illinois updated an existing law that same year). Because this list changes every legislative session, use the live tracker linked above to check your specific state rather than relying on a static number, or call your state attorney general’s office or state insurance department directly.
- If you have employer health coverage, find out if your plan is “self-funded.” This is the trap almost nobody knows about: even if your state has a ground-ambulance protection law, it likely does not apply if your employer’s health plan is self-funded (federally regulated under ERISA instead of state law). About 67% of workers with employer coverage are in self-funded plans, according to KFF’s 2025 Employer Health Benefits Survey. Ask your HR department point-blank: “is our health plan self-funded or fully insured?” It changes everything about whether your state’s law protects you.
- Request an itemized bill and your insurer’s Explanation of Benefits, then audit them line by line. Billing errors are common on ambulance bills — duplicate mileage charges, wrong service codes, oxygen or supplies billed that weren’t used. My full guide on why your hospital bill is probably wrong walks through exactly how to find these errors, and the same approach works on ambulance bills.
- Before you pay or acknowledge an old bill, check your state’s statute of limitations. Medical debt is usually treated like any other written-contract debt, with a state-specific deadline (often 3 to 6 years) after which a collector can no longer sue you over it. A partial payment or a written acknowledgment on a debt that’s already past that deadline can restart the clock — so if an ambulance bill is old, find out whether it’s time-barred before you pay anything or put anything in writing.
- If the total debt picture becomes unmanageable, bankruptcy discharges medical debt completely, ground ambulance included, federal protection gap or not. The automatic stay stops collection calls and lawsuits the moment you file. Find a bankruptcy attorney through NACBA, and talk to Damon Day for free before you decide anything.
Free Tool — Statute of Limitations Checker: Dealing with old debt? The free Statute of Limitations Checker tells you if the collection clock has expired in your state — including the zombie debt and clock-restarting traps collectors use. Check My Status →
How to Actually Stop It — Your Paths
- Bankruptcy wipes it out completely, no exceptions for ambulance debt. Medical debt of every kind — including ground ambulance bills that fall outside every other protection — is dischargeable in Chapter 7 or Chapter 13. The automatic stay stops any collection activity the day you file, and peer-reviewed research and Federal Reserve working papers show that people who get bankruptcy protection recover financially faster than people who try to grind through unmanageable medical debt on their own. If the ambulance bill is one piece of a bigger debt problem, this is usually the fastest real fix — not the last resort people assume it is.
- Check for a state-level protection before you assume you owe the full balance. If your state is one of the 22 (per the Commonwealth Fund’s tracker) with a ground-ambulance balance-billing law, and your coverage isn’t a self-funded ERISA plan that opted out, the ambulance company may legally only be able to bill you your normal in-network cost-sharing — not the full balance. Contact your state insurance department to confirm your specific rights before paying.
- Negotiate directly — ground ambulance bills have real, unpublicized flexibility. Ask for an uninsured/self-pay discount even if you have insurance and the claim denied, ask about financial hardship programs (many municipal EMS departments have them and don’t advertise them), and ask the billing office to itemize every line so you can challenge anything questionable. One strong anchor for that negotiation: look up the Medicare Ambulance Fee Schedule rate for your service — billed ambulance charges routinely run several times the Medicare rate, and citing that gap in writing is one of the most effective things you can do in a dispute letter. Get any agreement in writing before you pay a dollar.
- What WON’T work: assuming the No Surprises Act protects you, or ignoring the bill and hoping it disappears. Ground ambulance is the one carve-out even people who’ve researched surprise billing often miss. Ignoring the bill risks it moving to collections and hitting your credit report. Work the process instead.
What You Need to Know About Your Rights
The No Surprises Act, at 42 U.S.C. § 300gg-111, bans balance billing for emergency room care and for out-of-network providers at in-network facilities. A companion section, 42 U.S.C. § 300gg-112 (“Ending surprise air ambulance bills”), extends that same protection to air ambulances. There is no equivalent section for ground ambulances — Congress left that gap open on purpose. Instead, Section 117 of the No Surprises Act created the federal Ground Ambulance and Patient Billing (GAPB) Advisory Committee to study the problem. That committee met from May to November 2023 and submitted its final report to federal regulators on March 29, 2024. Its adopted recommendation (Recommendation 8) was to cap patient cost-sharing for ground ambulance emergency services at the lesser of $100 (adjusted annually by the CPI-U) or 10% of the “reasonable payment” rate the Committee recommended plans be required to pay ground ambulance providers, and to prohibit balance billing outright — but as of 2026, Congress has not enacted any of those recommendations. They remain recommendations, not law. That is the single most important fact in this guide: nothing has changed federally since the committee reported, and no bill closing this gap has passed.
| Situation | Protected from balance billing? | Notes |
|---|---|---|
| Federal baseline (No Surprises Act) | NOT protected. Ground ambulance is excluded. | 42 U.S.C. § 300gg-111/112 cover ER doctors and air ambulances only |
| Air ambulance (for comparison) | Protected federally. | See my air ambulance bill guide if that’s your situation instead |
| Washington State | Protected for emergency and non-emergency ground transport | SSB 5986 (Chapter 218, Laws of 2024) expanded the Balance Billing Protection Act to ground ambulance, effective January 1, 2025; self-funded ERISA plans must opt in separately |
| Oregon | Protected starting January 1, 2026 | HB 3243 (2025) bars balance billing by ground ambulance service organizations |
| New Hampshire | Protected starting January 1, 2026 | Senate Bill 245 (2025) ends ground-ambulance balance billing statewide |
| Other states | Check the tracker — varies | Roughly 22 states have some protection as of Feb. 2026 per the Commonwealth Fund tracker; where there’s no law, balance billing for ground ambulance remains fully legal — confirm with your state insurance department |
| Any state, if your plan is self-funded/ERISA | May not be protected even in a “protected” state | State insurance law generally can’t regulate self-funded employer plans unless the plan voluntarily opts in |
If your state doesn’t yet protect you, that doesn’t mean you’re out of options — it means negotiation, error-auditing, and (if the debt is unmanageable) bankruptcy carry more of the weight than the law does. See the complete guide to fighting and eliminating medical debt for the full playbook on hardship programs, payment plans, and negotiation scripts.
If the bill is instead from a doctor or hospital, not the ambulance itself — say, the ER physician who treated you after the ride — that’s a completely different, much more protected situation. See my guide on what to do if you got a bill from an out-of-network doctor for how the No Surprises Act actually does cover that.
If you believe you were billed incorrectly or a company is engaging in abusive collection tactics over an ambulance bill, file a complaint with the CFPB and your state attorney general. If you need legal help but can’t afford an attorney, find free legal aid through LSC.gov.
Steve’s Take
I filed bankruptcy in 1990, and I’ve spent more than 30 years since then watching people get sideswiped by bills nobody warned them about. The ambulance bill is one of the cruelest, because you had zero choice in the matter — you didn’t pick that ambulance company any more than you picked to be sick or hurt. Congress protected you from the ER doctor’s bill and the helicopter’s bill, and then just… didn’t finish the job on the ground ambulance. That’s not your failure, and it’s not a reason to panic-pay it on a credit card. Do the math, work the process, and if it’s part of a bigger pile that’s crushing you, know that a fresh start through bankruptcy erases this completely — ambulance company or not.
This one comes down to YOUR situation. Whether you have any real protection depends on your state, whether your employer plan is self-funded, and whether this was an emergency or scheduled transport. That’s exactly the kind of question I built the free Ask Steve chat for — tell me what’s actually going on and I’ll give you my honest read. It’s free and anonymous, and I sell nothing. Everyone else in debt wants to sell you a solution; I just want you to make the right call for you.
If the ambulance bill has already gone to collections, the rules change — there are deadlines running and a written-validation step that buys you a pause. I cover that in A Medical Bill Went to Collections and Nobody Warned Me. Here’s What to Do Right Now.
Frequently Asked Questions
I got an ambulance bill for hundreds of dollars I never agreed to — do I have to pay it?
Possibly, yes — unlike a surprise bill from an out-of-network ER doctor or air ambulance, ground ambulance balance billing is not banned by the federal No Surprises Act. Whether you owe the full balance depends on whether your state has its own protection law (a Commonwealth Fund tracker puts the count at 22 states as of February 2026 — check it for yours) and whether your health coverage is a self-funded employer plan that isn’t reached by state law. Check with your state insurance department before assuming either way.
Why does the No Surprises Act protect me from an air ambulance bill but not a ground ambulance bill?
Congress specifically excluded ground ambulance services when it wrote the No Surprises Act, creating a federal advisory committee (GAPB) to study the issue instead of legislating it immediately. That committee delivered its recommendations — including capping patient cost-sharing at the lesser of $100 or 10% of its recommended reasonable-payment rate — to federal regulators on March 29, 2024. Congress has not acted on those recommendations as of 2026, so the gap remains open.
My state has a ground-ambulance protection law — am I automatically covered?
Not necessarily. State balance-billing laws generally only apply to state-regulated insurance plans. If your employer’s health plan is self-funded (common at larger employers — about 67% of covered workers are in self-funded plans, per KFF’s 2025 survey), it’s regulated federally under ERISA instead, and your state’s law may not reach it unless the employer voluntarily opted in. Ask your HR department whether your plan is self-funded or fully insured.
I filed bankruptcy — how fast does it stop ambulance debt collection?
The automatic stay takes effect the moment you file, not weeks later. It immediately stops collection calls, letters, and any lawsuit over the ambulance bill, and the debt itself is dischargeable in Chapter 7 or Chapter 13 regardless of whether federal or state law protected you from balance billing in the first place. Peer-reviewed research and Federal Reserve working papers show filers recover financially faster than people who try to manage unmanageable medical debt without it.
Can an unpaid ambulance bill hurt my credit?
It can, but recent protections limit the damage. The three major credit bureaus voluntarily agreed to remove paid medical collections regardless of amount, remove unpaid medical collections under $500 entirely, and wait a full year before reporting any medical collection at all. The CFPB rule that would have banned medical debt from credit reports entirely was vacated by a federal court on July 11, 2025 (Cornerstone Credit Union League v. CFPB, E.D. Tex.), so larger unpaid medical debt, including ambulance bills, can still be reported. Disputing the bill promptly is your best protection while it’s under review.
What if the ambulance was a private, for-profit company instead of my city’s fire department?
It changes your negotiating leverage but not your basic rights. Private ambulance companies are typically less willing to negotiate than a municipal EMS department, but they still often have undisclosed hardship or prompt-pay discount programs — ask directly and in writing. Request an itemized bill and audit it the same way you would any medical bill; see my guide to fighting billing errors for the exact process.
Is it worth disputing an ambulance bill even if my state has no protection law?
Yes. Even where no state balance-billing law exists, you can still dispute billing errors (miscoded mileage, duplicate charges, services not rendered), request an itemized statement, and negotiate a reduced payment or hardship write-off. Ambulance companies, public and private, routinely settle for less than the billed amount when a patient pushes back in writing.
Should I put an ambulance bill on a credit card to make the calls stop?
No. I know the impulse — the calls are stressful and paying feels like it ends the problem. But medical debt, ambulance bills included, has real legal limits, is fully dischargeable in bankruptcy, and follows very different collection rules than consumer debt. Putting it on a credit card at 20–25% interest strips away those protections and turns manageable medical debt into much more dangerous credit card debt. Use the debt relief options calculator to see your real paths before you swipe a card.
One more thing — everything I share here is based on more than 30 years of helping people through exactly this. But my advice is input for your decision, not the decision itself. Only you know your full situation. Talk to an attorney, look at your numbers, and make the choice that serves your future.
Important: This guide is for informational purposes only and is not legal advice. Laws vary by state, and your situation may have details that change what options are available to you. For legal advice specific to your case, consult an attorney licensed in your state. NACBA can help you find a bankruptcy attorney, NACA can connect you with a consumer attorney, or talk to Damon Day for free about your situation.
Key Takeaway: A ground ambulance bill is one of the last true gaps in America’s surprise-billing protections — but that gap is closing state by state, and it’s not the end of your options even where it hasn’t closed yet. Check your state’s law, audit the bill, negotiate hard, and know that bankruptcy erases this debt completely if it’s part of a bigger problem. Use the Find Your Path quiz to see all your options side by side.
The Bottom Line
You didn’t choose which ambulance company responded to your 911 call, and you shouldn’t have to absorb Congress’s unfinished work on ground ambulance billing because of it. Twenty-two states have stepped in where the federal government hasn’t — find out if yours is one of them, and if it isn’t, negotiate the bill down instead of assuming you owe every dollar. If you know someone who just got hit with a huge ambulance bill, send them this page — the ERISA self-funded plan trap alone catches most people by surprise. Start with the complete guide to fighting and eliminating medical debt, and take the Find Your Path quiz if the bigger financial picture feels overwhelming.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research show bankruptcy filers recover faster than those who don’t file.
Right now you are dealing with the thing in front of you, and that is exactly where your attention belongs. When it is handled — and it will be — there is a next stage, and it is the one I most enjoy writing about.
In the latest issue (Sep 9): The paycheck advance app said it wasn’t a loan. Connecticut just made it give every fee back.
I write Your Money Actually most weekdays — what I am watching in debt and money, and the small decisions that compound. It is free, I sell nothing, and I take no money from any company I write about.



