

A Get Out of Debt series · Reading the filings so you don’t have to
What They Told Wall Street
FORM 10-QAMERICAN EXPRESS COMPANY (AXP)FILED 07/24/2026Q2 ENDING 06/30/2026CIK 0000004962
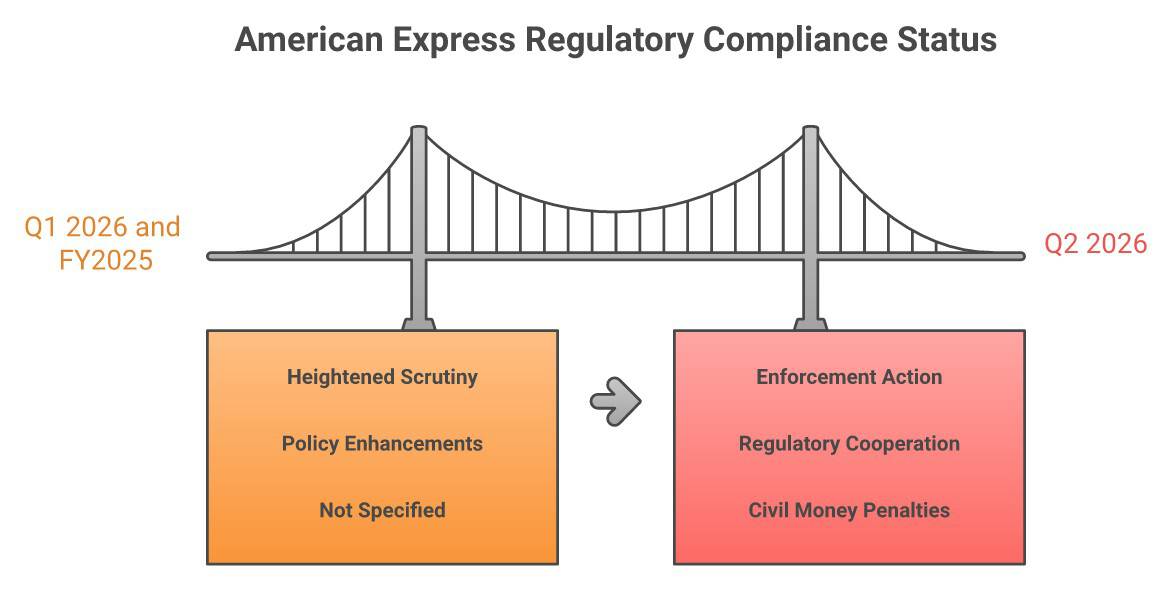
In the “Other Matters” section of American Express’s quarterly report to the SEC is a sentence that does not appear in either the immediately prior quarterly report (Q1 2026) or the most recent annual report (FY2025): it now expects to face an enforcement action in relation to certain aspects of its anti-money-laundering programs — an action that could include civil money penalties. It arrived the ordinary way — in a quarterly filing, which is exactly where a disclosure like this belongs.
I’ve written before about what to do if you can’t pay American Express, and about how quietly your bank can work against you. This series has already read what SoFi told the SEC about student loans and what Synchrony told the SEC about your credit card. This time it’s one of the biggest, most trusted names in consumer finance, filing something new about itself.
American Express is a global payments company and a bank holding company, supervised at the federal level by the Board of Governors of the Federal Reserve System — by its own account in this filing. On July 24, 2026, Amex filed its second-quarter report with the SEC. In a section called “Certain Legislative, Regulatory and Other Developments” — which is where a disclosure like this belongs — is language that does not appear in the immediately prior quarterly report (Q1 2026) or the most recent annual report (FY2025). In this filing it says it expects to be subject to an enforcement action in relation to certain aspects of its anti-money-laundering programs.
Q2 2026
Q2 2026
June 30, 2026
Source: American Express Company Form 10-Q for the quarter ended June 30, 2026, filed with the U.S. Securities and Exchange Commission on July 24, 2026.
What’s old vs. what’s new in this filing
What Amex has said for a while
Its anti-money-laundering programs have “become the subject of heightened scrutiny” and it is “working to make enhancements” — language that has appeared, in some form, in its recent annual report and prior quarterly filings.
What’s new this quarter
In this filing, Amex says it expects to be subject to enforcement action in relation to certain aspects of those programs — and that the action “could include civil money penalties.”
I checked. I read Amex’s prior quarterly report (filed April 23, 2026, for the quarter ending March 31) and its most recent annual report (filed February 6, 2026, for fiscal year 2025) side by side against this one. Neither one contains this sentence, or anything like it. The “heightened scrutiny” language is old. The expectation of enforcement action is not.
The disclosure — what Amex told the SEC
“We have also been subject to regulatory actions and may continue to be the subject of such actions, including governmental inquiries, investigations, enforcement proceedings and the imposition of fines or civil money penalties, in the event of noncompliance or alleged noncompliance with laws or regulations. For example, as previously disclosed, we have been engaging with regulators in relation to certain aspects of our anti-money laundering (AML) programs and as a result, we expect to be subject to enforcement action, which could include civil money penalties and lead to further regulatory inquiries. We are cooperating with ongoing reviews and have continued to make enhancements to our existing programs, policies and procedures and to identify and remediate deficiencies.”
One note on how I describe the scope. Read Amex’s sentence closely and you’ll see the phrase “in relation to certain aspects of our anti-money laundering (AML) programs” attaches, grammatically, to the engagement with regulators — and the expected enforcement action follows from that engagement (“and as a result”). Throughout this piece I describe the expected action as being in relation to certain aspects of those programs. That is my reading, and it is deliberately the narrower one. I want to be straight that the filing leaves the question genuinely open: an action that grows out of an engagement about certain aspects could end up tracking those same aspects, or could turn out broader. Where a company’s own words leave that much room, I would rather describe it too narrowly than too broadly — and tell you plainly that I am doing it. The verbatim quote is right above so you can judge the difference yourself.
One honest caveat about that word “previously.” Amex’s own sentence starts “as previously disclosed,” so the company is telling you it has said some version of this before. What I can verify is narrower and worth stating precisely: this specific language — that it expects to be subject to enforcement action in relation to certain aspects of those programs — is not in the immediately prior quarterly report (Q1 2026) or the most recent annual report (FY2025), which carried only general “heightened scrutiny” wording. Amex filed several 8-K current reports between those two quarterly filings, and I have not read every one of them, so I am not going to tell you this is the first time the company has ever said it. I am telling you it is new to the quarterly and annual filings most people would actually look at.
What I think they’re really saying
Companies don’t write “we expect to be subject to enforcement action” for fun. Securities law requires a public company to disclose a material risk to its business — and Amex is telling investors, in plain terms, that it has been engaging with a regulator (or regulators — the filing doesn’t say which) in relation to certain aspects of its anti-money-laundering programs, and that Amex now expects an enforcement action in relation to certain aspects of those programs — an action that could carry civil money penalties. Notice what’s not here: no dollar figure, no named agency, no consent order, no timeline. This is Amex getting ahead of its own bad news before a regulator announces it — which is exactly what securities law is designed to force a public company to do. That’s my read of why this paragraph exists.
Anti-money laundering (AML) compliance program
In plain English
Every U.S. bank is legally required — under the Bank Secrecy Act as amended by the USA PATRIOT Act, and the FinCEN regulations written under them — to run a program that verifies who its customers are, watches for suspicious transactions, and reports certain activity to the federal government. This is why banks sometimes ask you unusual questions about a large deposit, put a temporary hold on a transfer, or ask you to explain the source of funds — it’s rarely about you personally; it’s the bank following a legal box-checking process it cannot skip. When a bank’s AML program has “deficiencies,” it means regulators believe the bank isn’t running that box-checking process well enough — not that the bank’s customers did anything wrong.
Civil money penalty / enforcement action
In plain English
A civil money penalty is a fine a bank regulator can impose on a bank for violating banking law or regulation — separate from, and usually much larger in scale than, anything an individual customer would ever pay. An “enforcement action” can range from a private supervisory letter all the way to a public consent order requiring the bank to fix specific problems on a deadline, sometimes with an independent monitor. None of that has happened yet here. Amex is disclosing that it expects an enforcement action in relation to certain aspects of its AML programs — not announcing that one has been issued.
Who actually enforces this — and why the filing doesn’t say
It’s worth being precise here, because this same filing separately notes that Amex’s U.S. consumer card marketing and servicing are “supervised and examined by the Consumer Financial Protection Bureau (CFPB).” That sentence is standing boilerplate — it appears in Amex’s prior quarterly filing in nearly identical form, and it is not connected to the AML disclosure above. The CFPB is Amex’s consumer-complaint regulator. Anti-money-laundering enforcement against a bank holding company like Amex more typically comes from banking regulators — the Federal Reserve (Amex’s own filing names the Fed as its primary federal regulator) and the U.S. Treasury’s Financial Crimes Enforcement Network (FinCEN) — not the CFPB. Amex’s filing doesn’t name which regulator it’s “engaging with.” I’m not going to guess. What I can tell you is that conflating the two would be inaccurate, and a company’s own SEC filing is exactly the kind of document where precision matters.
What this means for you
This disclosure isn’t about a specific fee, a specific lawsuit, or a specific refund — it’s a company telling Wall Street that a regulatory hammer may be coming, without saying when, how big, or from whom. It matters to you for a more general reason: anti-money-laundering pressure on big banks is exactly what sits behind a practice regulators call “de-risking” — when a bank closes or restricts accounts to avoid compliance risk, often with little explanation to the customer. If you’ve ever had an Amex (or any bank) account frozen, held, or closed and gotten a vague answer about “compliance” or “risk review,” broad anti-money-laundering pressure of that general kind is often what sits behind it. Let me be exact about what this filing does and does not say, though: it says nothing about consumer accounts, closures, or de-risking, and I am not suggesting it caused anything that happened to yours. I am explaining the category of regulatory pressure this disclosure belongs to, not drawing a line from it to your account.
What I’d do — If your own Amex account is ever frozen, held, or closed and you’re told it’s for “compliance” reasons, ask in writing for the specific reason and keep every document a bank gives you. Banks generally have wide contractual latitude to close accounts, so a closure by itself usually isn’t illegal — but you’re entitled to ask, and a paper trail matters if you ever need to dispute it. If you believe you were treated unfairly or discriminated against, you can file a complaint with the CFPB (for consumer card and servicing issues) or with the Federal Reserve (Amex’s primary bank regulator). And regardless of this filing: if Amex debt itself is what’s weighing on you, look at all your options before assuming the balance or the relationship is something you’re stuck with.
Steve’s bottom line
American Express told Wall Street in this filing that it expects to be subject to an enforcement action in relation to certain aspects of its anti-money-laundering programs, and that the action could include civil money penalties. No amount, no agency, no timeline — just a disclosure, filed in the ordinary place for one, in a quarterly report most people will never read.
Nothing here says Amex did anything wrong, and nothing here is about your specific bill or your specific account. Amex’s own filing doesn’t allege consumer harm, doesn’t name a dollar figure, and doesn’t identify which regulator it’s dealing with. What it does show is a pattern this whole series keeps finding: the words a company files with the SEC under securities law are more candid than anything it will ever put in a commercial. Read the filing. That’s the whole point of this series.
Frequently asked questions
What did American Express disclose about anti-money-laundering enforcement?
In its Form 10-Q filed with the SEC on July 24, 2026, American Express Company disclosed that it has been “engaging with regulators” in relation to certain aspects of its anti-money laundering (AML) programs and, as a result, “expects to be subject to enforcement action, which could include civil money penalties and lead to further regulatory inquiries.” The filing does not name a specific regulator, a dollar amount, or a timeline.
Is this language new, or has Amex said this before?
The specific statement that Amex “expects to be subject to enforcement action” in relation to certain aspects of its AML programs is new to this filing. It does not appear in Amex’s prior 10-Q (filed April 23, 2026, for the quarter ended March 31, 2026) or in its most recent annual report (Form 10-K filed February 6, 2026, for fiscal year 2025), both of which were compared directly against this filing’s language. Those earlier filings describe the AML programs as being under “heightened scrutiny,” but stop short of saying Amex expects an enforcement action in relation to certain aspects of them.
Does this mean American Express refunded or owes customers money?
No. This disclosure does not mention customer restitution, a refund program, or a specific consumer-harm finding. It’s a forward-looking risk disclosure about Amex’s own anti-money-laundering compliance program, not a settled enforcement action or a consumer relief program. Separate, standing boilerplate elsewhere in the same filing about “restitution to our customers” is generic risk-factor language common across the banking industry and is not specific to this AML matter.
Is the CFPB the regulator bringing this enforcement action?
The filing doesn’t say. Amex’s filing separately notes that its U.S. consumer card business is supervised by the Consumer Financial Protection Bureau (CFPB) — language that is standing boilerplate, not new, and not tied to the AML disclosure. Anti-money-laundering enforcement against a bank holding company like Amex more typically involves the Federal Reserve (Amex’s own filing names the Fed as its primary federal regulator) and the U.S. Treasury’s Financial Crimes Enforcement Network (FinCEN), rather than the CFPB. Amex’s filing does not identify which regulator it is dealing with on this specific issue.
What is a “civil money penalty”?
It’s a fine a bank regulator can impose on a bank for violating banking law or regulation. It is distinct from — and typically far larger in scale than — any fee or charge an individual customer would ever be assessed. An enforcement action can range from a private supervisory directive to a public consent order requiring specific fixes on a deadline.
Should I be worried about my own American Express account?
This disclosure is about Amex’s institutional compliance program, not about any individual customer’s account or balance. It doesn’t allege that customers were harmed. If your own account has ever been frozen, held, or closed with a vague “compliance” explanation, broad anti-money-laundering risk management of that general kind is often what sits behind those decisions — but nothing in this specific Amex filing says so, and I am not suggesting this disclosure caused anything that happened to your account. Ask the bank in writing for specifics, and if you believe you were treated unfairly, you can complain to the CFPB or the Federal Reserve.
Read it yourself — the primary sources
American Express Company — Form 10-Q, quarter ended June 30, 2026 (SEC.gov) →
Filed with the SEC on July 24, 2026. The AML disclosure is in Part I, Item 2 (MD&A), “Other Matters — Certain Legislative, Regulatory and Other Developments — Supervision & Regulation.”
Filing index — Form 10-Q, Accession No. 0000004962-26-000322 →
American Express Company — prior Form 10-Q, quarter ended March 31, 2026 (used for comparison — no matching AML enforcement-expectation language) →
To find any company’s SEC filings yourself: sec.gov/edgar/search → type the company name.
How to read this
Two different things appear above, kept separate on purpose. The quote in the gray box is fact — American Express’s own words, from its own SEC filing, public record filed under penalty of law, quoted verbatim and linked above so you can verify it yourself. The plain-English explanations and the amber note are my interpretation — offered to help you understand what this disclosure means, not American Express’s position, and not a statement about your specific account.
Nothing here says American Express has done anything wrong. A disclosure that a company expects to be subject to enforcement action is not itself an enforcement action, a finding of wrongdoing, or proof of consumer harm — and no dollar figure, agency, or timeline has been disclosed. I’m using this filing to explain what an AML compliance disclosure means and why regulators watch it, not to make a claim about American Express’s conduct beyond what its own filing says. This is general information and my opinion after more than 30 years helping people with debt, not legal or financial advice. If you have a specific dispute with American Express about your account, talk to a consumer attorney or file directly with the CFPB.
Know someone who carries an American Express card? Please forward this to them. Most people never see what’s in these filings unless someone reads them first.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research shows bankruptcy filers recover faster than those who don’t file.
“What They Told Wall Street” reads the SEC filings of the companies that handle your money and translates what they disclosed — one filing at a time. Sourced entirely from public SEC records. · See the whole series →



