

Fact-checked by Steve Rhode, consumer debt expert since 1994 • Last reviewed July 31, 2026 • Every claim below links to a primary source.
The verdict: Myth. Signing your deed over to an investor or “rescue” company — even if they promise you can stay and rent-to-own your way back — does not save your home from foreclosure. Transferring the deed hands over ownership; it does not transfer the mortgage. You still owe the loan, the new owner controls your house, and there is no requirement that they ever sell it back to you. The FTC documents this as one of the most common mortgage relief scams in the country.
I have to tell you about this. The FTC’s own consumer alert on mortgage relief scams spells out, almost word for word, the pitch that gets used on people who are terrified of losing their home. Here’s exactly how the FTC says the scammers say it:
“If you give us the deed to the home, we’ll get our own financing to save the home from foreclosure.” — FTC, “Mortgage Relief Scams”, describing the “Rent-to-Buy Ripoff” pattern
I’ve watched people in foreclosure make exactly this trade — sign over the one asset they still have — because it sounds like a lifeline. It isn’t. Let me walk you through what actually happens after you sign.
Well, Actually…
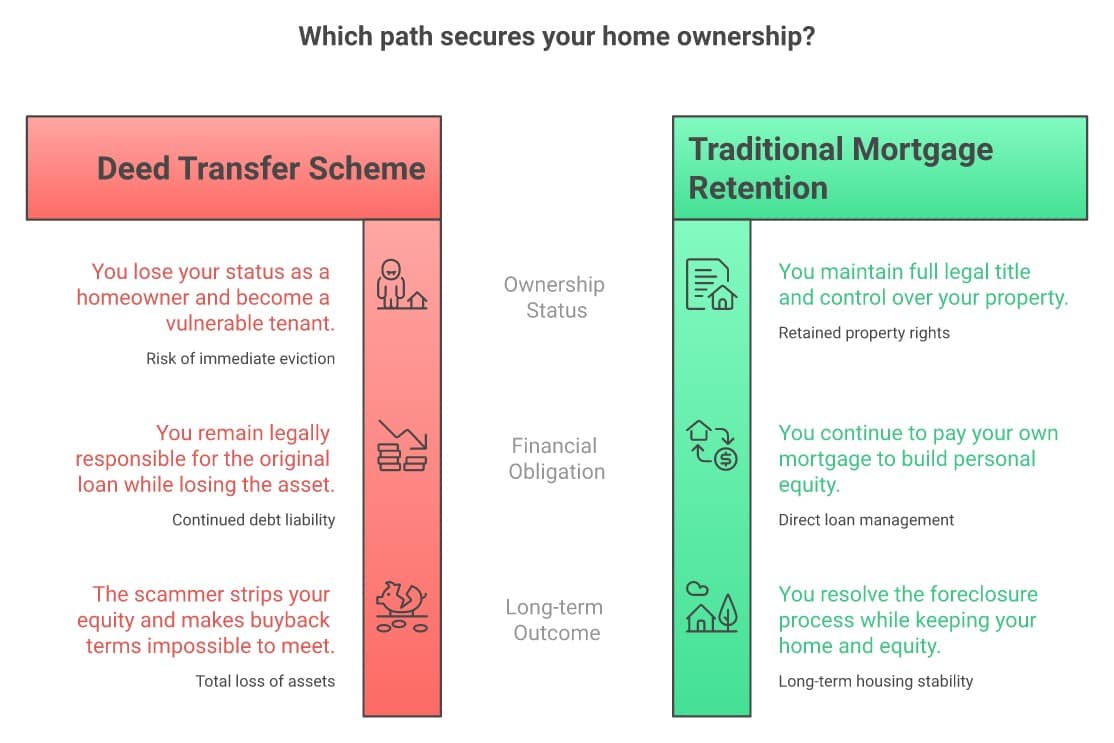
Here’s the part the pitch leaves out: a deed and a mortgage are two completely different legal documents. The deed says who owns the property. The mortgage note is a separate promise to repay a debt. Signing over the deed transfers ownership — it does not transfer, cancel, or forgive your obligation to pay back the loan. The FTC says this in plain language: “Transferring the deed does not transfer the mortgage, so you’ll still owe payments on your mortgage loan.” You can lose the house and still owe the debt on it — at the same time.
Once the “rescuer” has the deed, the FTC’s documented pattern is depressingly consistent: they rent the house out (often to you, as the former owner turned tenant), collect the rent, and let your original mortgage go straight into foreclosure anyway — because nothing in the deal actually required them to pay it. If they do offer to sell the house back to you later, the terms are frequently priced so buying it back is impossible, and the FTC notes some operators simply raise the rent until you fall behind and get evicted. At that point the scammer is free to sell your former home and keep every dollar — the sale proceeds, your years of built-up equity, and the rent you already paid them.
There’s a second trap buried in the fine print that almost nobody asks about: most mortgages contain a “due-on-sale” clause, and federal law (the Garn-St. Germain Depository Institutions Act, codified at 12 U.S.C. §1701j-3) gives your lender the right to enforce it. The instant you transfer title to someone else, your lender can typically declare the entire remaining loan balance due immediately — the opposite of relief. A deal marketed as “saving” your home from foreclosure can be the very thing that triggers full acceleration of the debt.
And here’s the legal status flip that matters most: as the homeowner, you have real protections before a foreclosure sale — a right to reinstate the loan by catching up what’s owed, formal notice requirements, and (in many states) time before a sale can even be scheduled. The moment you hand over the deed, you’re not the homeowner anymore. You’re a tenant in a lease you probably didn’t negotiate, in a house someone else now owns, and tenants can be evicted through landlord-tenant law — a much faster, much thinner set of protections than the ones you gave up.
Sign the deed over to us. We’ll get our own financing to stop the foreclosure, and you can rent from us until you buy the house back.
Transferring the deed conveys ownership of the property — not the mortgage debt, and not a promise to pay it. Once you sign, the new “owner” controls the home. There is no legal requirement that they ever make your mortgage payments, sell the home back to you, or refund a cent of your equity. The FTC documents this under “Rent-to-Buy Ripoffs” — and a closely related scheme, where you’re talked into selling rather than leasing back, under “Equity-Skimming Scams.”
Since I don’t own the house anymore, I’m not responsible for the mortgage.
You remain personally liable on the promissory note unless your lender formally releases you through an approved loan assumption — something lenders rarely agree to and a deed-transfer scammer never arranges. Worse, transferring title can trigger the mortgage’s due-on-sale clause, which federal law lets your lender enforce, making the entire loan balance due immediately.
12 U.S.C. §1701j-3, Garn-St. Germain Depository Institutions Act
This is basically the same as getting help from a HUD housing counselor or a real loan modification — just faster.
Real mortgage assistance — from your own servicer, a HUD-approved counselor, or a legitimate paid provider — never requires you to sign over your deed as the price of admission, and it’s free through HUD. Most companies that charge a fee to help stop a foreclosure are legally a “mortgage assistance relief service” under federal Regulation O, which bans misrepresenting the results you’ll get and bans collecting any fee before your lender actually approves a real, written modification. But Regulation O has real exemptions, so not every company that offers foreclosure help is covered: your own loan servicer or lender isn’t reached by the rule to begin with, and 12 CFR §1015.7 exempts a licensed attorney who is providing the help as part of practicing law and meets the rule’s conditions. Free HUD-approved housing counselors fall outside the fee-based scheme the rule is built to police. None of those exemptions cover a company that asks for your deed as the price of “stopping” your foreclosure.
12 CFR §1015.3 (misrepresentation ban), §1015.5 (advance-fee ban) & §1015.7 (exemptions), Regulation O
Why You Were Told This
Follow the money and this stops being confusing. If someone convinces you to sign over a house that may have $100,000, $200,000, or more in built-up equity — in exchange for nothing but a verbal promise — they’ve effectively acquired that asset for free. They can rent it out, sell it, or simply let your original foreclosure run its course while they walk away with whatever equity existed. You’re left with the house gone and, in many cases, still owing money on it. The math only works for the person on the other side of the signature.
The pitch also works because it exploits real fear at the worst possible moment. Someone facing a scheduled foreclosure sale is often out of options they know about, ashamed to ask for help, and desperate enough to sign whatever gets put in front of them. Scammers specifically tell people not to contact their lender, their own attorney, or a housing counselor before signing — because any of those calls would likely stop the deal.
Regulators have recognized this pattern for decades, which is exactly why it’s regulated at both the federal and state level: the Consumer Financial Protection Bureau’s Regulation O (the “MARS Rule”) defines any paid service that claims it will “stop, prevent, or postpone” a foreclosure sale or otherwise “save the consumer’s dwelling from foreclosure” — exactly how a deed-transfer “rescue” pitches itself — as a mortgage assistance relief service subject to strict disclosure and anti-misrepresentation rules, and multiple states go further. California’s Home Equity Sales Contracts Act, on the books since 1979, and Florida’s foreclosure-fraud statute (Fla. Stat. §501.1377) both specifically regulate “equity purchasers” who buy homes in foreclosure — requiring a plain-language written contract and, in California, a 5-business-day right to cancel. A legitimate deal can meet those requirements. A scam almost never does.
What to Actually Do
If your foreclosure sale date is only days away, treat this as an emergency. Call a HUD-approved housing counselor and an attorney the same day — don’t wait on the mail or a callback.
- Call a HUD-approved housing counselor today — it’s free. Dial 800-569-4287 (TTY 202-708-1455) or use the CFPB’s Find a Housing Counselor tool. These counselors are government-vetted and never ask for your deed.
- Call your loan servicer directly — before you sign anything with anyone else. Ask about forbearance, repayment plans, or a loan modification. You lose nothing by asking, and your servicer is the only party who can actually change the terms of your loan.
- Never sign a deed over to a third-party “rescue” company or investor — that’s different from a deed-in-lieu with your own lender. A deed-in-lieu of foreclosure negotiated directly with your OWN servicer can be a legitimate last-resort option, but get any deficiency waiver in writing first (see the FAQ below). Signing your deed over to an unrelated company that showed up offering to “save” your home is not the same thing and carries none of those protections. Also never sign a power of attorney or any document you haven’t read line by line — ideally reviewed by an independent real-estate attorney you hired yourself. If someone hands you a stack of papers and rushes you to sign, that pressure is itself the warning sign.
- The same scam pressure shows up around property tax lien sales, too. If an investor bought a tax lien on your home instead of your mortgage lender foreclosing, see what to do if your property tax lien was sold — the deadlines and the recovery-scam pattern are different.
- Ask about bankruptcy before you assume the house is already gone. Filing bankruptcy triggers the automatic stay under 11 U.S.C. §362, which halts most foreclosure sales the moment your case is filed, and a Chapter 13 can let you catch up on missed mortgage payments over time instead of losing the house. It isn’t automatic protection in every situation — the stay has exceptions, and if you had a bankruptcy case dismissed within the past year the stay may only last 30 days unless a court extends it, or may not arise at all if two or more of your cases were dismissed within that same one-year window. A bankruptcy attorney can tell you in one conversation whether this helps your situation; the National Association of Consumer Bankruptcy Attorneys has a directory of member attorneys.
- Get everything in writing and know your right to cancel. If a state-regulated “equity purchaser” contract is involved, you may have a legal cooling-off period (5 business days in California, for example) to cancel — use it, and never let anyone talk you out of it. Compare against your full range of foreclosure options before you decide anything.
- Already signed a deed over to a rescue company or investor? Call a real-estate litigator or a legal-aid attorney today — don’t wait. In many states, a deed obtained through a noncompliant equity-purchase or foreclosure-consultant transaction is voidable, meaning you may be able to rescind it, record a notice of rescission, and pursue a quiet-title action to get ownership back. California’s Civil Code §1695 et seq., cited below, is one example of this kind of statute — ask an attorney whether your state has something similar. This isn’t guaranteed everywhere, but speed matters: the longer you wait, the more likely the buyer is to resell or borrow against your former home, which makes undoing the transfer much harder.
- Report it. If you were pitched a deed-transfer or rent-to-own foreclosure “rescue,” file a complaint at ReportFraud.ftc.gov and with the CFPB, and contact your state attorney general.
Steve’s Take
I’ve been doing this since 1994, and the foreclosure-rescue deed transfer is one of the oldest, cruelest tricks in the book because it targets people at the exact moment they have the least capacity to scrutinize a contract. You’re scared, you’re ashamed, and someone is offering you a way to keep living in your own house. That combination shuts down good judgment faster than almost anything else in personal finance.
Here’s the thing that makes me angriest about this one: it doesn’t just cost people their home. It routinely leaves them still owing the mortgage debt on a house they no longer live in and don’t own — the single worst financial outcome I can think of short of actual fraud charges against the homeowner themselves. And to be clear, this IS fraud — just aimed at you instead of by you.
If you take away one thing from this: the free help is real, and it comes with no strings, no deed transfer, and no rush. A HUD-approved counselor will spend an hour with you for nothing. A scammer wants your signature in ten minutes. That contrast alone should tell you everything you need to know about which one is actually trying to help you.
Free Tool — Contract Decoder: Have a contract from a debt relief company? The free Contract Decoder analyzes it for red flags, hidden fees, and problematic terms — before you sign anything. Decode My Contract →
Frequently Asked Questions
Is transferring my deed to a company ever a legitimate way to stop foreclosure?
No legitimate foreclosure-assistance path requires you to sign over your deed to a private company or investor. Legitimate options — forbearance, repayment plans, loan modification, refinancing, or a short sale you control — work through your own lender or a HUD-approved counselor, and none of them require you to give up ownership as a condition of getting help. The FTC lists deed transfer as a defining warning sign of a mortgage relief scam. One thing worth separating out: a “deed-in-lieu of foreclosure” handed directly to YOUR OWN lender is a real, sometimes sensible last-resort workout — but it does not automatically erase the debt. Your lender can still pursue you for any deficiency (the gap between what you owed and what the home is worth) unless the lender expressly waives that deficiency in writing, and forgiven mortgage debt can carry tax consequences. Get the deficiency waiver in writing before you sign anything. What this post debunks is different: handing your deed to an unrelated third-party investor or “rescue” company, which does not extinguish your mortgage debt at all and comes with none of the protections a direct deed-in-lieu with your own lender can have.
What happens to my mortgage after I transfer the deed?
You still owe it. A deed transfer changes who holds title to the property; it does not change who owes the debt on the promissory note. You would need your lender to formally approve a loan assumption and release you from liability — something scammers never arrange — or your lender could instead enforce a due-on-sale clause and demand the full balance immediately under 12 U.S.C. §1701j-3.
Can I get my house back after I sign the deed over?
Rarely, and it’s not something you can count on. The FTC reports that the scammer usually doesn’t sell the home back at all, and when a buyback is offered, the terms are frequently priced to make it unaffordable. Meanwhile you’re now renting from the person who owns your former home, and missed rent payments can lead to eviction.
But a buyback isn’t your only route. Separately from anything the company offers you, many states make a deed obtained through a noncompliant foreclosure-rescue or equity-purchase transaction voidable — see “Already signed a deed over?” above. That is a legal remedy you pursue through an attorney, not a favour you ask the buyer for, and it is time-sensitive: the longer you wait, the more likely the buyer has resold or borrowed against the property.
What are the warning signs of a foreclosure rescue scam?
Any request to sign over your deed; pressure not to contact your lender, attorney, or a housing counselor; demands for an upfront fee; promises to definitely “save your home”; refusal to put the deal in writing in plain language; and rushing you to sign without time to review the documents or consult your own attorney.
Does my state have any specific protection against this kind of scheme?
Many do. California’s Home Equity Sales Contracts Act (Civil Code §1695 et seq.) requires a written contract with an equity purchaser and gives you a 5-business-day right to cancel (§1695.4). Florida’s Fla. Stat. §501.1377 specifically regulates “equity purchasers” buying homes in foreclosure. Check your own state attorney general’s site for similar foreclosure-consultant or equity-purchaser laws, and treat any deal that skips these protections as a red flag.
What should I do instead if I’m behind on my mortgage?
Call your loan servicer first — ask about forbearance, a repayment plan, or a loan modification. Then call a free HUD-approved housing counselor at 800-569-4287 or use the CFPB’s counselor search tool. Do this before you sign anything with anyone who contacted you first.
Is it illegal for a company to offer to help me save my home from foreclosure?
No — legitimate mortgage assistance relief services exist and are legal. And where federal Regulation O applies, the provider is barred from misrepresenting your odds of success, your affiliation with the government, or the terms of the deal, and barred from collecting a fee before your lender actually approves a real, written result. Remember the limits I set out above though — the rule doesn’t reach your own servicer, and §1015.7 exempts a licensed attorney who meets its conditions — so “Regulation O covers them” isn’t automatic. A company that asks for your deed instead of a written, lender-approved agreement is not operating within these rules.
This post is meant to give you information, not legal advice. Foreclosure law varies significantly by state, and what I write here is one informed perspective from someone who has spent over 30 years in this space — not a substitute for advice from a real-estate attorney or HUD-approved counselor who knows your full situation. Take this as input, not instruction, and make the decision that’s right for you.
The bottom line: Signing your deed over to a “rescuer” doesn’t erase your mortgage debt — it just adds losing your home outright to the list of things that can go wrong. Free, no-strings help exists through your loan servicer and HUD-approved counselors. If someone you know is facing foreclosure and considering a deed transfer, send them this first.
Related: If you’re facing foreclosure right now, start with my full foreclosure crisis guide and the complete rundown of your real options before anyone asks you to sign anything.
Dealing With Debt? Understanding your options is the first step. See how all your debt relief options compare — including ones most sites won’t tell you about. The Find Your Path quiz gives a recommendation based on your actual numbers, and the Scam-O-Meter checks any company’s complaint history before you sign. Federal Reserve Bank of New York research show bankruptcy filers recover faster than those who don’t file.



